Let’s Be Real. For Most Retirees, Only One Caribbean Island Actually Works
Every Caribbean island looks promising until Medicare, currency risk, and hurricane season start collapsing the spreadsheet. One territory survives the stress test, but the math is tighter and the hidden costs are stranger than most retirement calculators ever show.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A couple in their early sixties wants sun, warm water, a slower pace, and a lower cost of living, so they start researching the Caribbean. Then reality sets in. Medicare does not travel. Foreign residency permits carry income floors. Local healthcare is uneven. Currency risk, hurricane exposure, and murky property titling can turn a dream into a project with no clear end date. Stack the practical constraints against the financial ones, and there is really only one Caribbean island where the math works for a typical American retiree: Puerto Rico.
Why Puerto Rico Is the Only One That Actually Pencils
Puerto Rico is a US territory, and that status carries enormous practical weight. Social Security deposits directly into a mainland bank without currency conversion. Medicare Parts A, B, C, and D all function normally. The currency is the dollar. You can drive on a US license and fly to Miami without a passport. Every other island forces a retiree to self-insure healthcare, buy a foreign expat policy, or fly back to the mainland for anything serious. That single fact eliminates Aruba, the Caymans, the Dominican Republic, and every other candidate for the median retiree.
One procedural detail deserves attention early in the planning process. Puerto Rico residents who receive Social Security are automatically enrolled in Medicare Part A at 65, but Part B enrollment is not automatic and must be actively elected. The standard Part B premium runs $202.90 a month in 2026. Overlooking the enrollment step creates a coverage gap that becomes expensive to fix later.
Your IRA and 401(k) distributions, pension income, and Social Security all remain under the same federal rules you already know. The Act 60 tax incentives apply to active investors and business owners, not to retirees drawing down portfolios, so plan around ordinary retiree tax rules.
The Real Cost Picture for a Couple Around Age 65
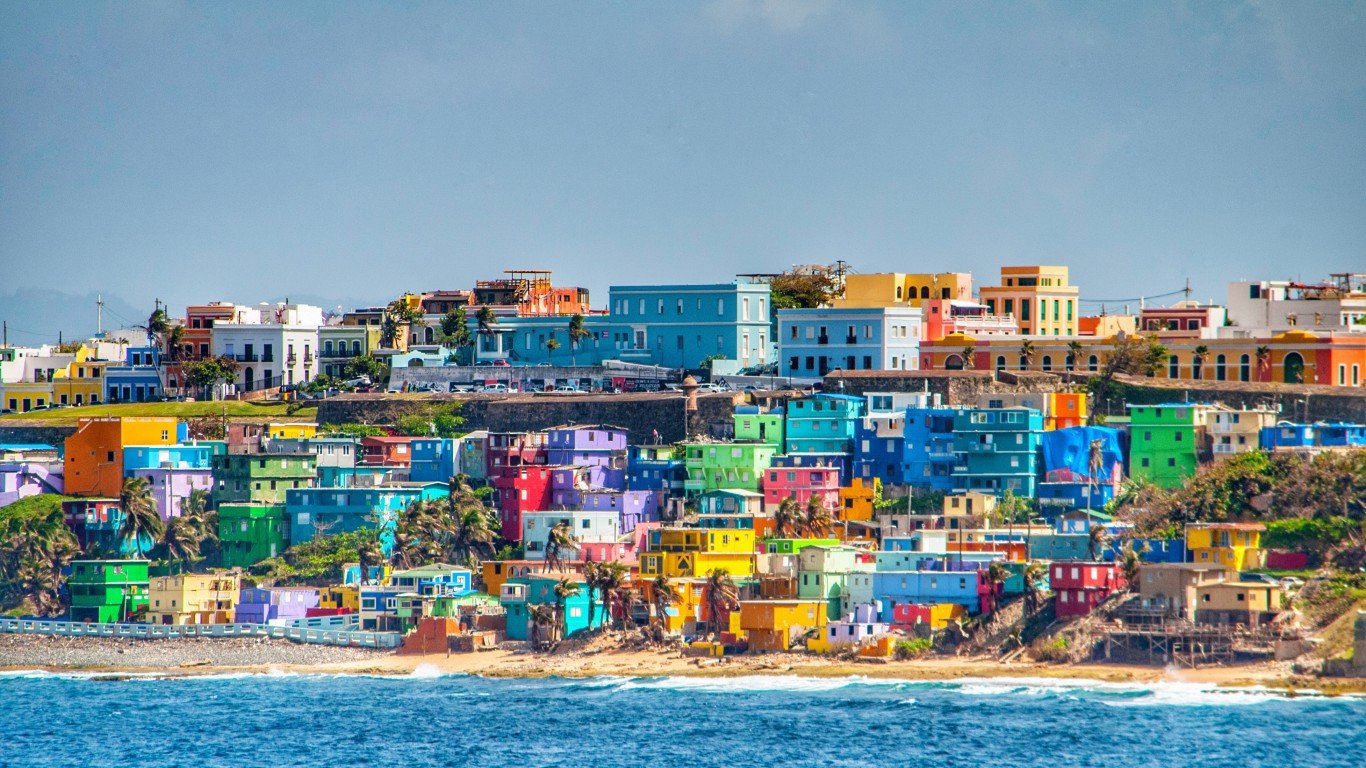
Skip San Juan proper unless you want mainland-metro prices. The retiree sweet spots are the west coast around Rincon and Aguadilla, the south coast around Ponce, and smaller east-coast towns. A comfortable two-bedroom condo with an ocean view runs roughly $275,000 to $375,000 to purchase, or $1,600 to $2,200 a month to rent. Property taxes on a modest condo often come in under $1,200 a year.
Annual budget in current dollars for a couple who own outright:
- HOA, wind and hazard insurance, property tax: $9,000
- Electricity, water, internet, phones: $5,400
- Food and household: $11,500
- Medicare Part B, Medigap or Advantage premiums, dental, out of pocket: $8,400
- One vehicle, fuel, insurance, maintenance: $5,500
- Travel back to the mainland twice a year: $4,500
- Miscellaneous, gifts, entertainment, restaurants: $7,000
- Home reserves, vehicle replacement, income taxes: $6,700
That totals about $58,000 a year. Renters should add roughly $12,000 and drop the HOA and insurance line, landing near $61,000. For context, the BLS puts average US household spending at $78,535 for 2024, so the island delivers a real discount but not an enormous one.
The Math From Budget to Portfolio
Assume a couple claiming at full retirement age and generating combined Social Security of about $44,000 a year. The 2.8% COLA for 2026 keeps that income moving with prices, which matters as core PCE continues its slow grind higher.
Subtract $44,000 from a $58,000 budget and the annual portfolio gap is $14,000. At a 4% withdrawal rate, covering that gap requires a nest egg of $350,000. Add a $60,000 buffer for a generator, solar panels, and roof reserves, and the realistic target is $410,000 of investable assets on top of a paid-off condo. Renters face a wider gap of about $17,000, pushing the target to roughly $425,000 plus a rent reserve. A Treasury ladder yielding near the current 5.27% on the ten-year note, paired with a broad index fund sleeve and a dividend ETF sleeve, covers the withdrawal without heroics. By contrast, the national average 12-month CD yields just 1.73%, a rate that loses ground to inflation and belongs nowhere in this plan.
The Line Item Nobody Prices Correctly
Wind and hazard coverage on a coastal condo can run $2,500 to $4,500 a year, and premiums climb after every named-storm season. A whole-home generator or solar-plus-battery setup is essential, not optional: it keeps insulin cold and the AC running during multi-day outages. Budget $18,000 to $35,000 up front and roughly $1,200 a year in maintenance and fuel. Over a thirty-year retirement, that stack quietly consumes an extra $80,000 to $120,000 that mainland budgets never see.
Medicare Advantage networks in Puerto Rico cover routine care, but the market recently thinned. Humana exited Puerto Rico entirely effective January 1, 2026, leaving enrollees to choose among local carriers. MCS Classicare, Triple-S Advantage, MMM Healthcare, First Medical, and Plan de Salud Menonita now lead the market. MCS Advantage holds a 5-star CMS rating for the 2027 plan year, one of only 18 contracts nationwide to earn that distinction out of 516 evaluated. That said, CMS reimbursement rates for Puerto Rico run roughly 41% below the national average, a structural gap that keeps sustained pressure on plan sustainability and network breadth. Skilled nursing capacity on the island remains thin. Plan on a mainland exit option in your late seventies or a dedicated long-term care reserve of $150,000 per spouse.
What It Actually Takes
For a couple around 65 who own a modest condo outright, Puerto Rico works on roughly $410,000 to $500,000 of investable assets, drawn at 4%, alongside average Social Security. Renters need closer to $550,000 to $650,000. Add a hurricane and power reserve of $30,000 and an LTC reserve of $150,000 per person, and the realistic all-in target lands between $750,000 and $950,000 plus the home. Anything below that threshold and you are one storm, one hospitalization, or one bad year away from moving back.
Editor’s note: The 10-year Treasury yield cited in the portfolio section has been updated to approximately 5.27%, reflecting FRED and USDT data as of October 7, 2026, up sharply from the 4.79% referenced in the prior version. The national average 12-month CD rate has been revised to 1.73% per FDIC data as of September 21, 2026. The MCS Advantage 5-star rating reference has been updated from the 2026 to the 2027 CMS star ratings cycle, and the Medicare Part B standard premium of $202.90 per month for 2026 has been added.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.