The Retirees Who Moved to Puerto Rico for the Tax Break Say the Tax Break Was Never the Point
Puerto Rico's Act 60 tax break sounds like a retiree's dream, but most retirement income never qualifies for it. Here is what the move actually costs, who it genuinely helps, and what happens when the math does not work out…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
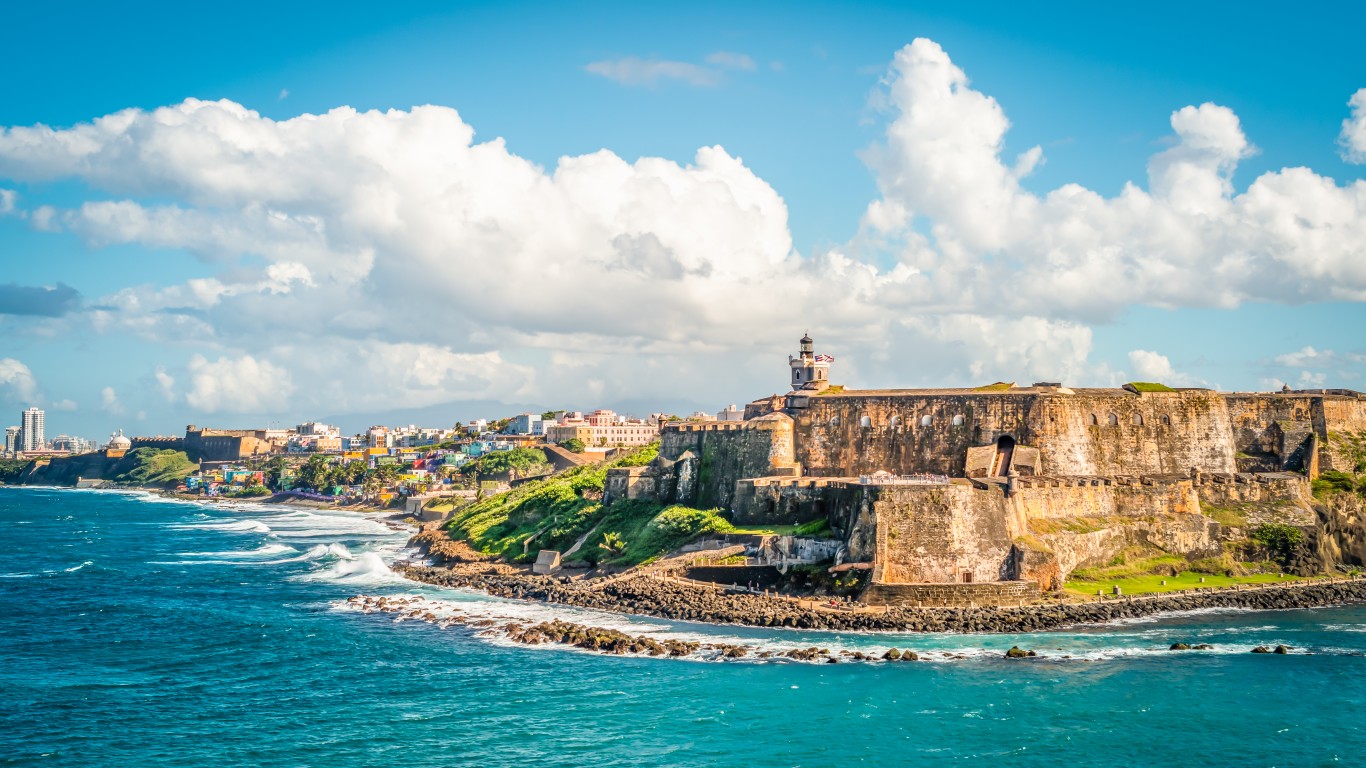
One of the most important recent moves for anyone considering a retirement in Puerto Rico is that it passed Act 38-2026 on March 10, 2026. Anyone applying for Act 60 investor status on or after January 1, 2027, will pay a 4% preferential rate on qualifying interest, dividends, and capital gains earned after the move. Under the old terms, that rate was zero. Research on retirees who relocate shows that about 60% moved somewhere more affordable, typically freeing up around $100,000 in home equity.
What a Comfortable Island Retirement Actually Costs
Consider that a typical American household spends $78,535 a year. In San Juan, rent averages $1,722 a month, or $20,664 annually. Home prices average around $480,040, though Dorado condos range from $136 to $3,110 per square foot. For a couple, Medicare Part B costs $202.90 per person per month, or about $4,870 a year, plus a $283 deductible per person.
That leaves roughly $53,000 for food, electricity, hurricane insurance, a car, mainland flights, home maintenance, reserves, and federal income tax. Many residents also pay for solar panels and battery backup due to the island’s power grid history.
Turning the Budget Into a Portfolio Target
If both spouses collect the average Social Security benefit of $2,071 a month, that’s $49,704 a year, leaving a $28,831 gap. At a 4% withdrawal rate, it takes about $721,000 to cover it. At 3.5%, suitable for a 30-year retirement, it takes about $824,000. The 2027 cost-of-living adjustment is on track for 3.3%, so waiting past full retirement age to claim reduces the portfolio target.
Why Most Retiree Income Misses the Tax Break
Under Section 933, bona fide residents exclude only income from Puerto Rico. “Income from US sources remains subject to federal tax regardless of where you live.” Most retiree income counts as U.S.-source: Social Security, IRA and 401(k) money, and dividends from U.S. companies. Act 60’s rate applies only to appreciation after the move. If a $2,000,000 position grows to $5,000,000, only the $3,000,000 of growth qualifies.
A $500,000 post-move gain taxed at roughly 20% federal long-term rate costs $100,000. Under the 4% rate, it costs $20,000. A couple pulling about $29,000 a year from an IRA gets little benefit. Failing the presence, tax home, or closer connection tests means income falls back to standard federal rates up to 37%.
Puerto Rico residents enroll automatically only in Part A and must sign up for Part B themselves. The late-enrollment penalty adds 10% for every 12 full months without coverage and lasts for life.
What It Takes to Make the Move Work
The math works for a couple with two average Social Security checks and about $720,000 to $825,000 in investments held in index funds, dividend ETFs, and Treasury ladders, withdrawing roughly 3.5% annually. It assumes a home near the San Juan rent average. Beachfront Dorado raises the housing target and portfolio requirement.
For any retiree serious about moving, applying before December 31, 2026 locks in the older terms, which matters only for households with large taxable accounts expecting big gains. For others, success depends on day-to-day expenses, reliable power, timely Part B sign-up, and wanting island life regardless of tax benefits.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.