Retirees Who Rent in Puerto Rico for a Year Before Buying Will Say It Saved Them the Whole Island
A retired couple eyeing Puerto Rico faces one question that determines whether the move saves money or quietly costs a fortune, and it has nothing to do with the beach or the tax code.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
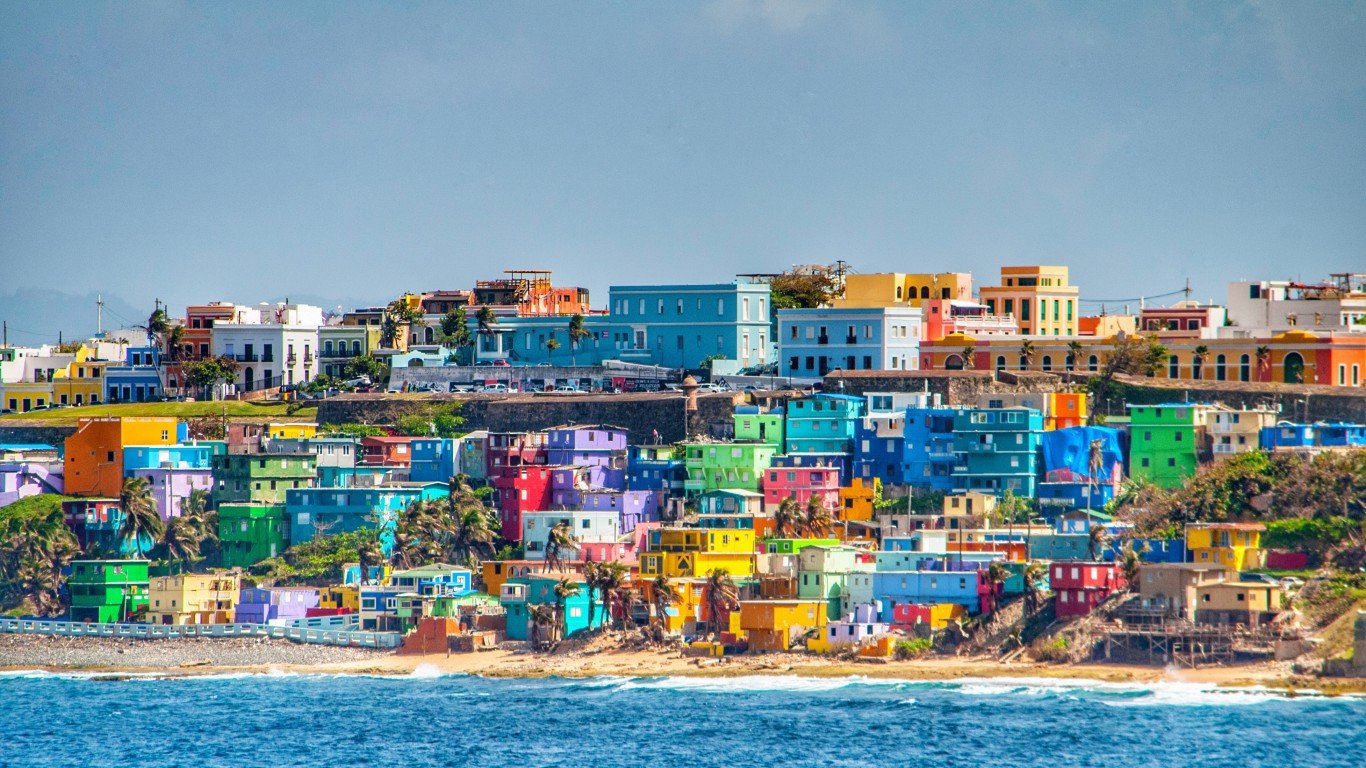
Puerto Rico produces a familiar retirement question. Can a couple trade a mainland ZIP code for the island, keep Social Security along with Medicare, and live well on the same money? A common approach is to rent for a full year in the target area, then buy. The breakdown below covers what that year costs, the portfolio it takes to carry the life that follows, and how the rental year affects taxes.
What a Year of Island Renting Costs a Retired Couple
Rent drives the budget, and a two-bedroom in San Juan averaged $2,400 a month in early 2026. Zillow puts the island-wide two-bedroom average at $1,950. In Dorado, single-family rentals run from $2,100 to $30,000 a month. That spread is the reason to rent first, because towns a short drive apart can price very differently. Electricity is a significant line item. Regulators set the rate at $0.26 per kWh for early 2026, and air conditioning runs most of the year.
| Annual Line Items (Couple, 65+) | Sample Estimate |
|---|---|
| San Juan two-bedroom rent | $28,800 |
| Electricity, water, internet, phones | $6,000 |
| Medicare Part B for two, supplemental coverage, drugs, out-of-pocket | $11,000 |
| Food (mostly imported, so above mainland prices) | $13,000 |
| Car, insurance, fuel | $7,000 |
| Flights to the mainland and family visits | $6,000 |
| Personal spending, gifts, emergency reserve | $8,000 |
| Income tax on withdrawals | $5,000 |
| Total | $84,800 |
Part B alone costs $202.90 a month per person, or about $4,870 a year for two before any supplemental coverage.
Turning an $85,000 Budget Into a Portfolio Target
The SSA estimates the average aged couple both receiving benefits will collect $3,355 a month after the 3.6% cost-of-living adjustment for 2027. The total works out to $40,260 a year, leaving a $44,540 gap. Taking 4% annually, the portfolio target is about $1.11 million. A couple retiring in their early 60s who wants a 3.5% rate to cover a longer horizon needs roughly $1.27 million. Under SSA rules, delaying the higher earner’s claim past the age for full benefits adds 8% a year until 70 and increases the survivor benefit, which closes part of that gap for good.
Buying after the rental year changes the line items without removing the housing cost. Condo and gated-community fees run from $75 to $500+ monthly. Windstorm deductibles typically sit at 2% of coverage, so a $400,000 home leaves about $8,000 out of pocket per storm. Some couples hold the purchase money in a treasury ladder during the rental year to limit its exposure to a market drop before closing.
Why the Rental Year Decides the Tax Outcome
Federal law excludes only “income derived from sources within Puerto Rico” for someone who is a bona fide resident for the entire taxable year, under 26 U.S.C. § 933(1). Distributions from a mainland IRA or 401(k) stay federally taxable. Puerto Rico’s income tax reached a top rate of 33% on income over $61,500 in 2024, while Hacienda lists an exclusion of $11,000 for pensioners 60 or older. Social Security is generally not taxed by Puerto Rico.
Residency under 26 U.S.C. § 937(a) requires at least 183 days on the island, no tax home elsewhere, and no closer connection to the mainland. A couple who keeps the old house “just in case” during the rental year undermines that closer-connection position.
Act 60 adds a timing question. Decrees obtained by December 31, 2026 keep 0% Puerto Rico tax on interest, dividends and post-move gains until January 1, 2036. Applications filed from 2027 on face a 4% rate, and holders must buy a primary residence within two years of the decree. A one-year rental fits inside that window. For a retired person living mostly on IRA withdrawals, the gap between 0% and 4% touches only taxable-account income, so it carries little weight in the purchase decision.
What It Takes to Make the Island Work
For a couple, the working numbers are about $85,000 a year in spending, roughly $40,000 from Social Security, with a portfolio of $1.1 million to $1.3 million drawn at 3.5% to 4%. A balanced mix of index funds, dividend ETFs and staggered Treasury bonds is one way couples structure that draw (we laid out the case for an income-first alternative to the 4% rule in a free guide). If the portfolio comes in short, the options are a cheaper town than San Juan, a later Social Security claim or a smaller home after the rental year.
The rental year tests residency as much as it tests neighborhoods. Selling or leasing out the mainland house improves the residency position, and the decree’s two-year purchase window, rather than the year-end deadline, sets the latest purchase date.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.