Could a Retired Couple Live in Tulsa on Social Security Plus $2,000 a Month From Savings? Here’s the Budget
Tulsa offers a riverfront, a lively downtown, and a cost of living well below the national average. But one line on a retiree's budget can swing wildly, and over 30 years it may matter more than every other expense combined.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Take a couple in their late 60s with modest savings. They want a real city with a riverfront, a downtown with some life in it and good restaurants, at a lower cost than a big city. Tulsa keeps coming up.
So can Social Security plus $2,000 a month from savings support two people there? Yes, and there’s some room left over. One bill, though, can use up that surplus quickly.
Income Lands Near $5,200 a Month, and Taxes Barely Touch It
According to the SSA, the average benefit for a senior couple where both spouses collect is $3,208 a month after the 2.8% COLA. Add the savings draw, and the couple has $5,208 a month. For 20207, the SSA estimates that a retired worker and aged spouse will receive $3,354 monthly for a retired worker and aged spouse in 2027.
Taxes come out close to zero. The IRS counts half your benefits plus your other income. For this couple, that’s $43,248, which is above the $32,000 joint threshold.
That makes about $5,624 of benefits taxable, so adjusted gross income comes to roughly $29,624. That’s under the $32,200 joint standard deduction for 2026, so they owe no federal tax.
Social Security is exempt from Oklahoma income tax, and each spouse can also exclude up to $10,000 a year of IRA or 401(k) withdrawals. The top rate is 4.5%, and the joint standard deduction is $12,700.
If the draw comes from accounts in both names, the state bill is zero as well. Sales tax is where Oklahoma does collect. The combined minimum rate in Tulsa County is 8.517%, although the state’s sales tax on groceries was eliminated.
Tulsa Budget for Renters and Owners
Two-bedroom apartments in Tulsa run $1,100 to $1,200 a month, with downtown and midtown on the higher end. For owners, the median house price in Tulsa County is $200,476, and the median property tax bill is $1,970. Medicare Part B costs $202.90 per person. Food, utilities, the car, supplemental coverage, and reserves are example planning estimates, so substitute your own.
| Monthly Line | Renting | Owning, No Mortgage |
|---|---|---|
| Housing | $1,200 rent | $164 tax, $448 insurance, $167 maintenance |
| Medicare Part B, two people | $406 | $406 |
| Medigap/Part D estimate | $450 | $450 |
| Groceries/household estimate | $850 | $850 |
| Utilities/phone/internet estimate | $375 | $375 |
| Car/replacement fund estimate | $650 | $650 |
| Medical/dental out-of-pocket estimate | $200 | $200 |
| Gifts/personal/emergency reserve estimate | $550 | $550 |
| Income taxes | $0 | $0 |
| Total | $4,681 | $4,260 |
| Left over | $527 | $948 |
On these numbers, both versions run a surplus. Renters pay more each month but support no property tax or insurance bill. Owners keep more each month, but more of their budget depends on one volatile bill.
What Tulsa Delivers and What It Asks in Return
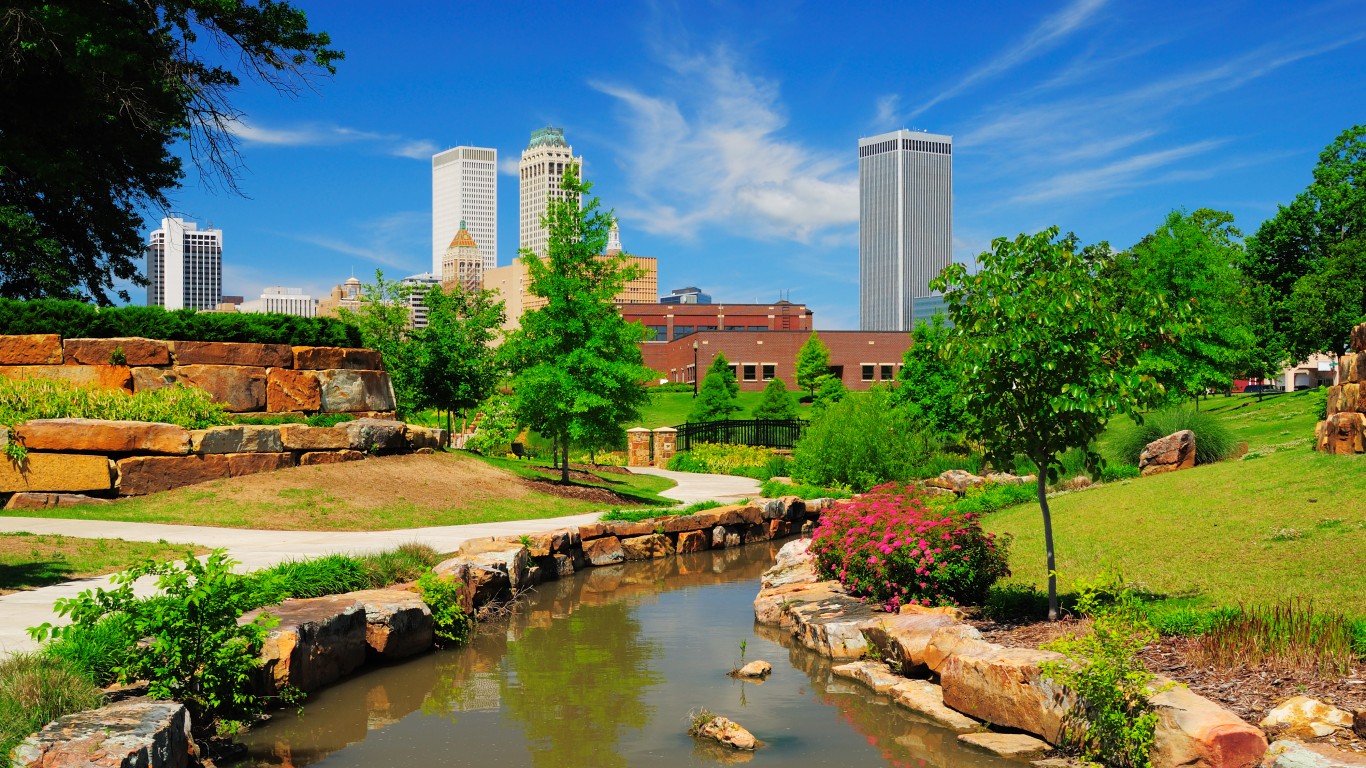
Oklahoma’s price level is 87.843 against a national benchmark of 100. Gathering Place is a free park covering 66.5 acres along the Arkansas River. The city also has a walkable Arts District and an Art Deco skyline.
Oklahoma’s average homeowners premium is $5,378 a year, driven by tornadoes and large hail. That’s about 2.7 times the median property tax bill. The senior valuation freeze locks a home’s assessed value, but it does nothing to stop premiums from rising.
With a gross household income of $62,496, this couple misses the additional homestead exemption, which has a $30,000 income cap. They also miss the senior sales tax credit, capped at $50,000. A buyer coming in now also pays more, since metro home prices are up 45.5% over five years.
Survivorship is the other risk. When one spouse dies, the household keeps only the larger of the two checks. The average widow(er) gets $1,919 a month. If the higher earner waits to claim, that bigger check becomes the survivor’s floor for life.
Verdict: Insurance Decides It
Drawing $24,000 a year takes about $600,000 if you pull out 4% annually, which suits a 25- to 30-year horizon, assuming the money comes from a fully taxable traditional IRA withdrawal. At 5% it takes about $480,000, which only makes sense if they can cut spending when markets fall (we laid out the income-first alternative to the 4% rule in a free guide).
One common approach is a balanced mix of index funds plus a short Treasury ladder holding two years of withdrawals, earning a modest real return. Splitting the draw between both spouses’ IRAs keeps state tax at zero, and the owner’s surplus could fund a deductible reserve. Over 30 years, the homeowners insurance line will do more than anything else on this budget to decide whether Tulsa stays affordable.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.