Savannah Has Squares, Spanish Moss and a Big Georgia Tax Break for Retirees. What It Takes to Retire There at 66 on $1 Million

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
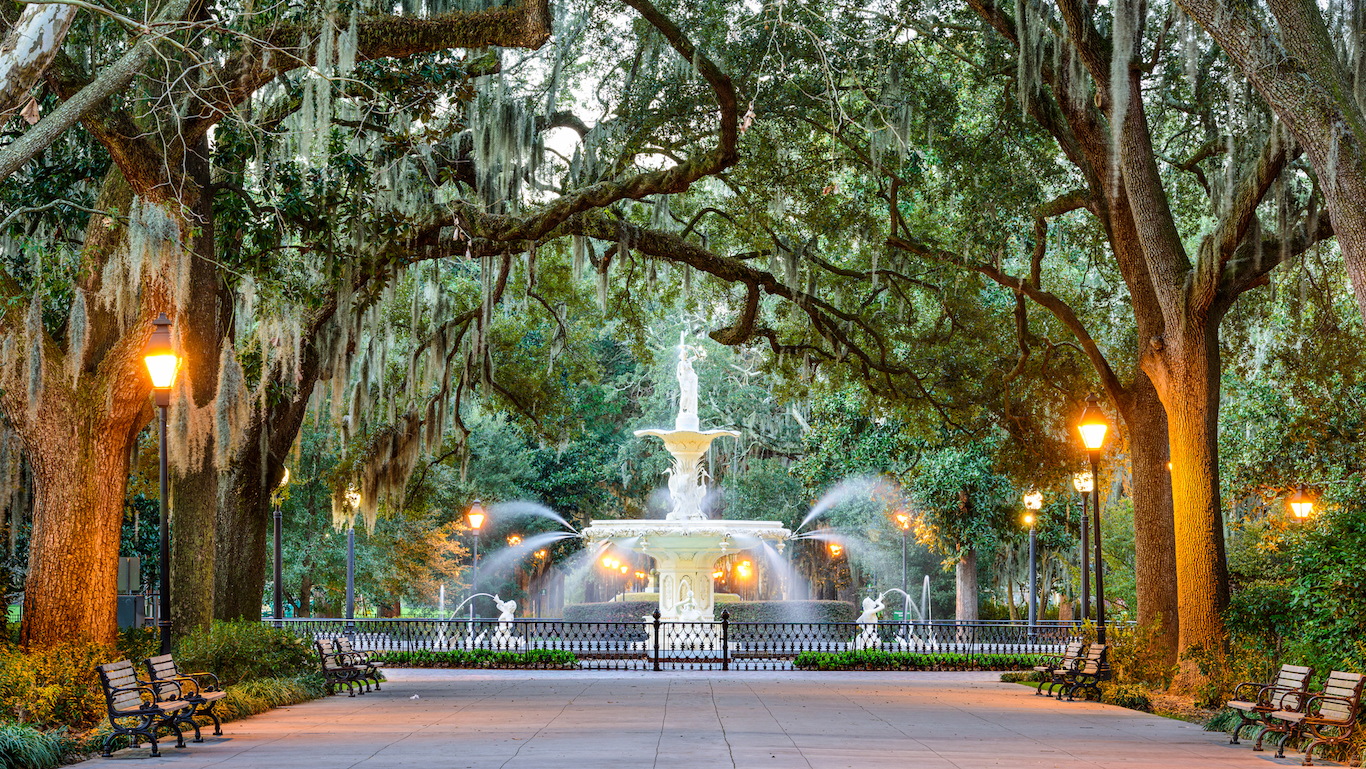
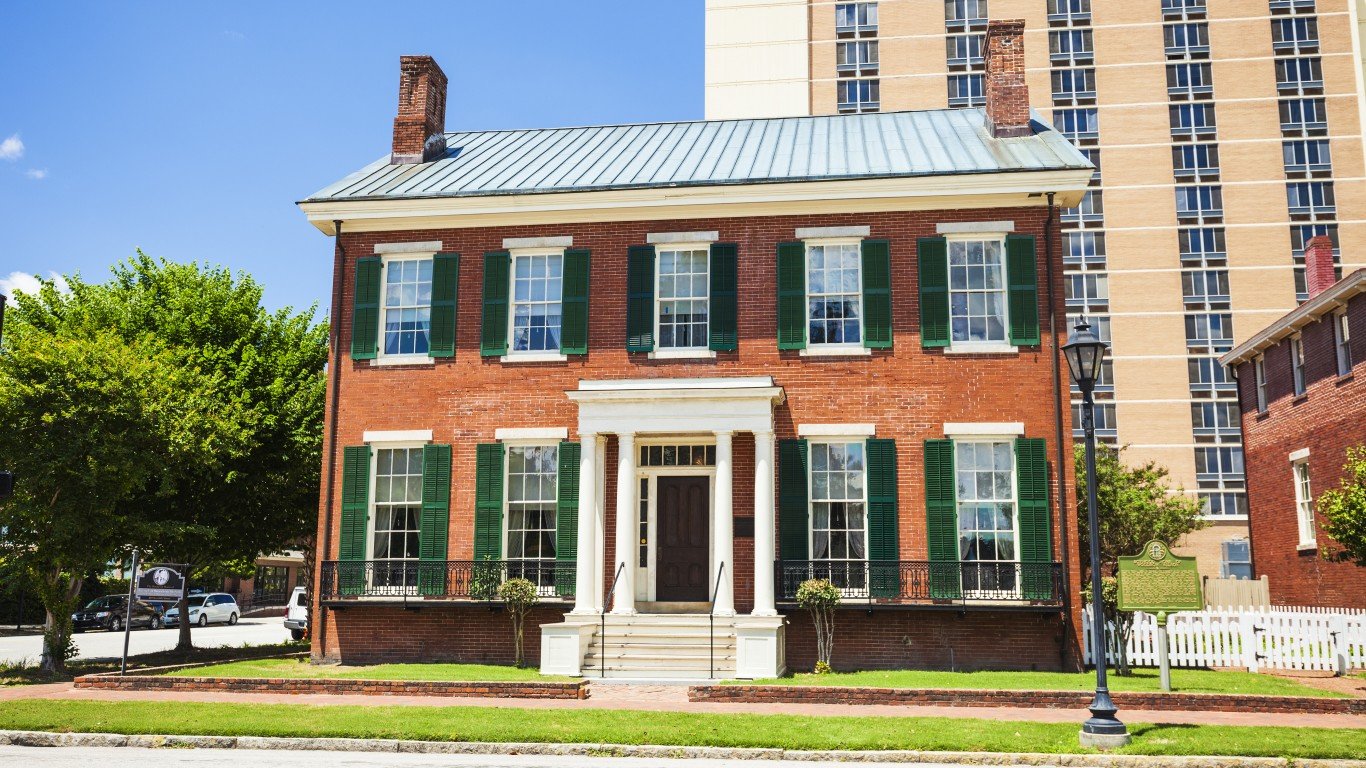
Savannah, Georgia, is known for its historic squares and live oaks, but what does a retirement budget there actually look like? Can two 66-year-old spouses just starting Medicare retire in Savannah on $1 million in savings plus Social Security? The answer depends on Georgia’s tax rules, the cost of insuring a coastal home, and a withdrawal rate that has to last 25 or 30 years.
What Georgia’s Retiree Tax Break Really Covers
On the one hand, Georgia offers a tax break for retirees. The Department of Revenue tells filers to leave Social Security out of the retirement exclusion calculation because it’s not taxable to Georgia. The state also provides a maximum retirement income exclusion of $65,000 for taxpayers age 65 or older. Each spouse claims it separately, and up to $5,000 can be counted as earned income. Anything left over is taxed at a flat 4.99%, after a standard deduction of $30,000 when filing jointly.
Property tax relief is narrower, with the state’s $2,000 homestead exemption coming off the home’s 40% assessed value. The $4,000 exemption at 65 and the school tax exemption at 62 both cap prior-year income at $10,000, but retirement income doesn’t count toward the $96,432 limit. Chatham County adds its own exemptions, and the assessor’s office can confirm which ones apply. The combined sales tax in Chatham County is 7%.
Building a Monthly Budget on $1 Million in Savannah
At 4%, $1 million yields $40,000 a year. A senior couple where both spouses collect Social Security averages $3,208 a month in 2026, or $38,496 a year. Combined, that comes to about $6,541 a month. The budget below assumes they buy a house near Savannah’s median value of about $344,551 with money from selling their old home, so the $1 million stays invested.
| Monthly item | Cost |
|---|---|
| Property tax at Georgia’s 1.00% median rate | $287 |
| Homeowners insurance, $2,136 a year | $178 |
| Flood insurance, $1,000 a year | $83 |
| Medicare Part B, two people at $202.90[1] each | $405.80[1] |
| Medigap Plan G, two people | $400 |
| Electricity | $134 |
| Federal income tax | $226 |
| Georgia income tax | $0 |
| Subtotal | $1,714 |
| Left for food, water, car, maintenance, travel, reserves | $4,827 |
The federal figure is a high estimate. It taxes about $18,961 of Social Security and applies the $32,200 deduction married couples take, before the extra deductions for people 65 and older. The Part B premium stays at the base rate as long as joint income stays under $218,000[1]. The average household spent $81,905 in 2025, for reference. Covering that much spending at 4% with the average couple’s benefit would take about $1,085,225, compared with $1 million in savings. The 4% figure is based on older research for a different market, and a free guide lays out the case for an income-first alternative here.
History, Beaches and Hurricane Season
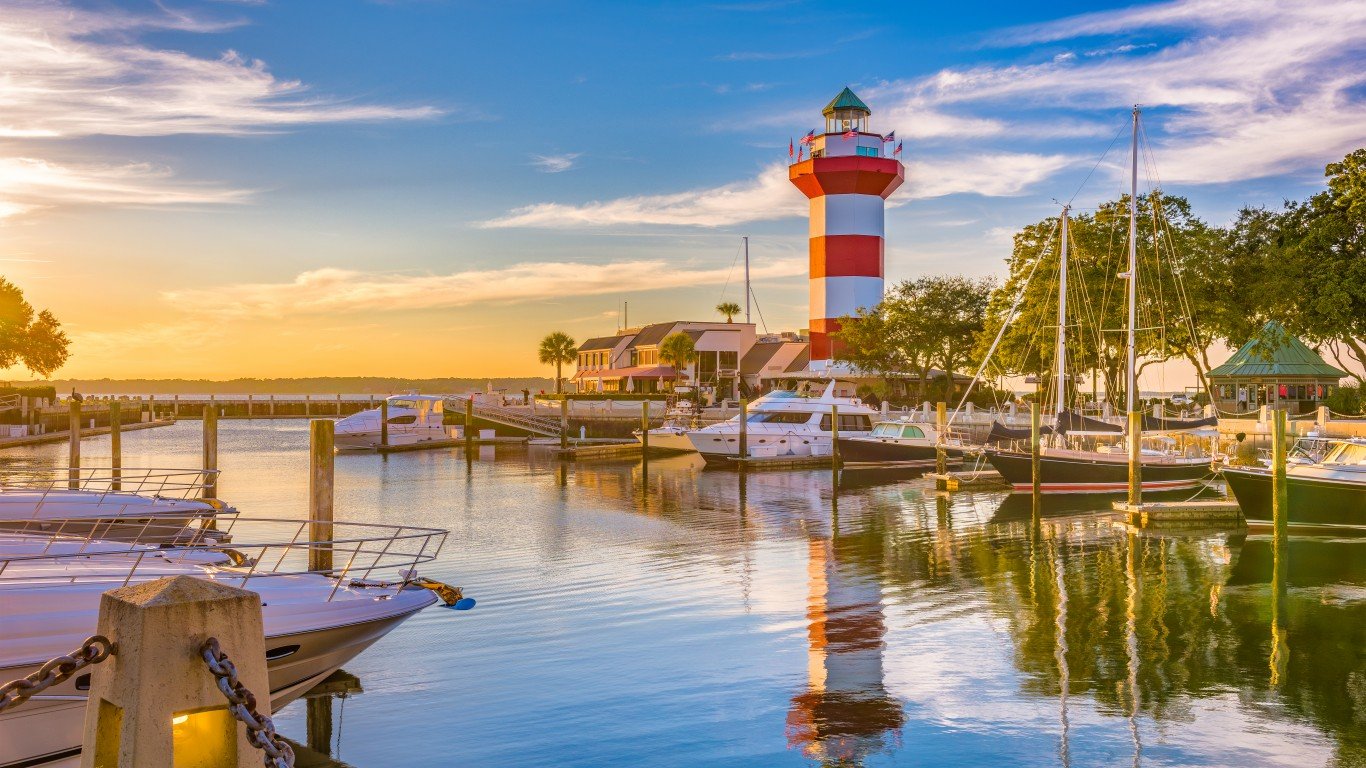
Savannah has a walkable historic district, a restaurant scene, the beaches at Tybee Island, an international airport, and regional hospital systems. Hilton Head, just across the South Carolina line, is a nearby alternative. Drawbacks include long, humid summers, tourist crowds downtown, and hurricane season. Local home prices rose 63.5%[2] over five years, then slowed to 3.37% over the latest year. Social Security’s COLA is 2.8% for 2026 and 3.6% for 2027.
Whose Name Is on the IRA Matters
Georgia gives each spouse a separate exclusion, and an IRA belongs to just one person. Income from jointly owned assets gets split 50% between spouses, but an IRA can’t be held jointly. If most of the $1 million sits in one spouse’s IRA, a big withdrawal year for a new roof or a car could push that spouse past $65,000. The amount above that spouse’s $65,000 exclusion remains subject to Georgia tax after any applicable deductions, even if the other spouse’s exclusion goes unused.
Withdrawals split between both spouses’ accounts can keep the state tax near zero. Required minimum distributions don’t start until age 75 for people born in 1960.
Getting the Flood Quote Before the Offer
The plan may hold up if the house is bought with outside money, the $1 million stays invested in index funds and a treasury ladder, withdrawals are split between both spouses, and spending stays near $6,541 a month. The flood line in the budget varies the most by property. Policies through the federal flood program cap home coverage at $250,000, and rates depend on the flood zone and each house’s elevation. A written flood insurance quote for the exact address provides the actual figure for that line of the budget.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.