Hilton Head Island Draws Golfers and Boaters. What It Takes to Retire There at 65 on $1.2 Million

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
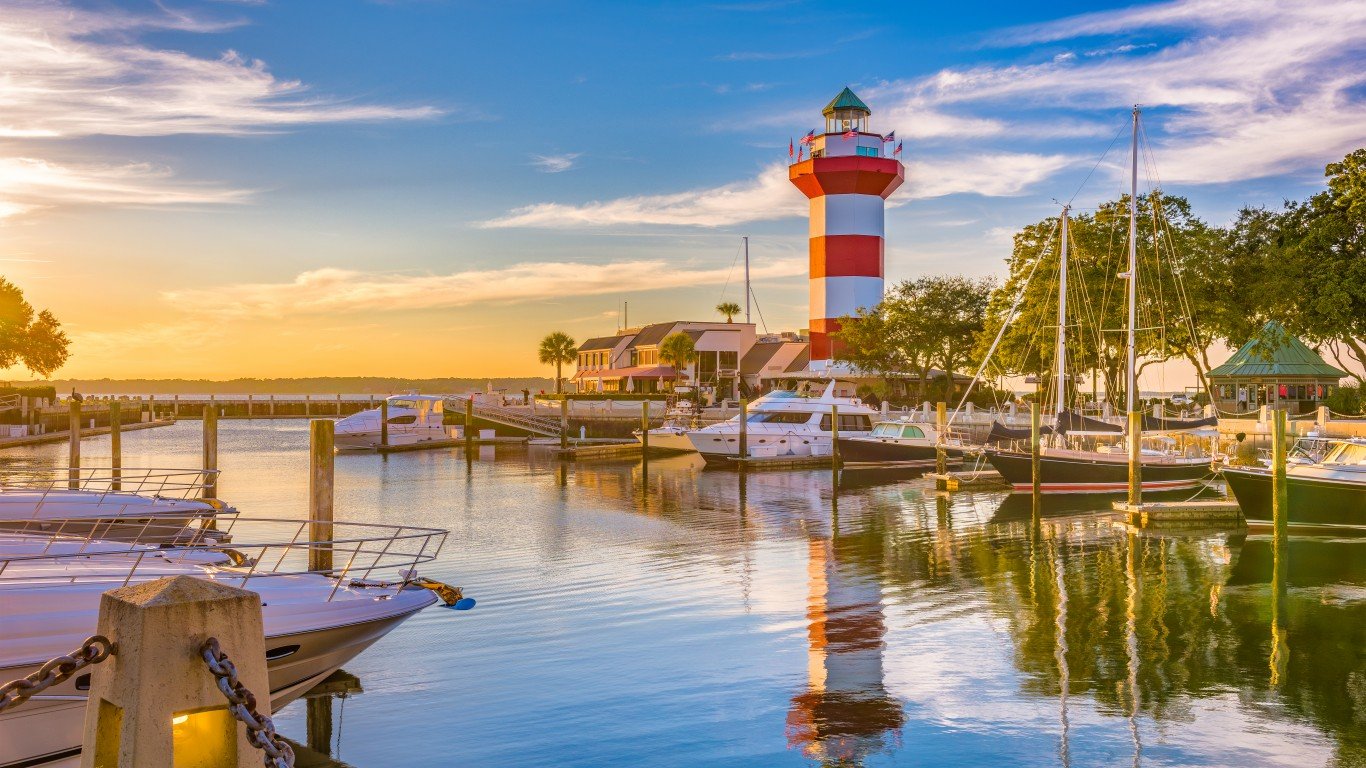
This article examines the cost of retiring on Hilton Head Island on South Carolina’s coast, including golf, boating, and biking. The key question is whether $1.2 million in savings can cover it for a couple who turn 65 and start Medicare the same year.
Housing prices rank first among the budget items to consider. In the Federal Housing Finance Agency’s House Price Index, the Hilton Head Island-Bluffton-Port Royal metro rose 2.66%[1] over the year to the second quarter of 2026 and 63.76% over five years. Redfin put the island’s median sale price at $814K over a recent three-month stretch. The math assumes the couple buys a home near that median with proceeds from selling a previous one, so the full $1.2 million stays invested. If the house comes out of the savings, the figures below no longer apply.
South Carolina’s Tax Rules Carry Much of the Load
South Carolina exempts Social Security benefits[2] from state income tax. Starting at 65, each taxpayer can deduct up to $10,000[2] a year of qualifying retirement income. Residents 65 and older also get a $15,000[2] deduction against any South Carolina income, reduced by whatever retirement deduction they claim. For 2026, income under $30,000 is taxed at 1.99%[3], and income above that is taxed at 5.21%, minus $966. South Carolina also introduced a deduction of up to $30,000 for joint filers in 2026, reduced as income rises.
With those deductions applied to both spouses, a couple living on IRA withdrawals and Social Security can owe very little state income tax.
Sales tax is 7% across Beaufort County, including a 1% Green Space Tax. The town adds a 4% layer on accommodations, and that mostly lands on visitors. Our earlier Charleston coverage explained why full-time residence matters: primary homes are assessed at 4% of market value, compared with 6% for second homes. Owners over 65 also get a homestead exemption on the first $50,000[4] of their residence’s fair market value.
Golf, a Boat and the Basics Come to About $91,800 a Year
| Annual line item | Estimate |
|---|---|
| Property tax (county median effective rate) | $3,700 |
| Homeowners, wind and flood insurance | $9,000 |
| HOA (Sea Pines improved lot) | $2,100 |
| Utilities, maintenance, repairs | $12,000 |
| Health care for two | $12,000 |
| Food and dining | $14,000 |
| Two vehicles | $6,500 |
| Golf and boating | $20,000 |
| Reserves, gifts, replacements | $8,000 |
| Federal income tax | $4,500 |
| Total | $91,800 |
Part B costs $202.90[5] a month per person, about $4,870 a year for two. That falls under the health care line along with a supplement, drug coverage, and dental. The property tax figure applies the county’s median rate, $1,319 on a $290,900 home, to an island-priced house. The federal estimate is based on the $32,200 joint standard deduction and comes in a little lower once the extra deductions for taxpayers 65 and older are included.
Where $1.2 Million Lands
The average aged couple receives $3,355[6] a month after the 2027 COLA, or $40,260 a year. That leaves a $51,540 gap, equal to a 4.3% starting withdrawal. Withdrawing 4% from $1.2 million provides $48,000. Filling the entire gap at 4% would take about $1.29 million.
A 28-year retirement horizon is a reasonable planning assumption, though a 4.3% withdrawal rate carries more risk than the traditional 4% benchmark. Cutting about $3,540 a year closes the difference. Waiting to claim Social Security increases the monthly check, but it also means larger portfolio withdrawals in the early years.
Hurricane Insurance Can Undo the Budget
Other drawbacks include tourist-season traffic on the island’s few main roads, strict HOA design rules, and fewer specialists on the island, which means trips to Savannah’s hospitals across the state line. Hurricane risk also affects insurance costs in the budget. South Carolina homeowner premiums are expected to rise 8% in 2026 and another 8% in 2027. A $9,000 premium that grows 8% a year would reach about $19,400 in ten years. Social Security’s latest COLA is 3.6%[6]. Hilton Head homeowners do get a 25% discount on federal flood insurance.
The math assumes a paid-off home bought without using the savings, a starting withdrawal near 4.3% from a balanced portfolio of index funds and a Treasury ladder, and a lifestyle budget reduced by a few thousand dollars or a buffer of about $1.29 million. CDs average 1.76%, below the 4.3% starting withdrawal rate.
Flood and windstorm insurance quotes are available on a specific house before a contract is signed. Insurance is one of the higher variable costs in the budget. The 4.3% figure also pushes past the old safe-withdrawal benchmark, which is the whole subject of a free report we put together on why the 4% rule wobbles now and what to run instead.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.