She Will Retire in Savannah Short on Savings. Leading Walking Tours a Few Nights a Week Will Cover What Social Security Doesn’t
Moving to Savannah and leading ghost tours a few nights a week sounds like a soft landing into retirement, but the math behind the plan reveals a gap that tips and history lessons alone may not close.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
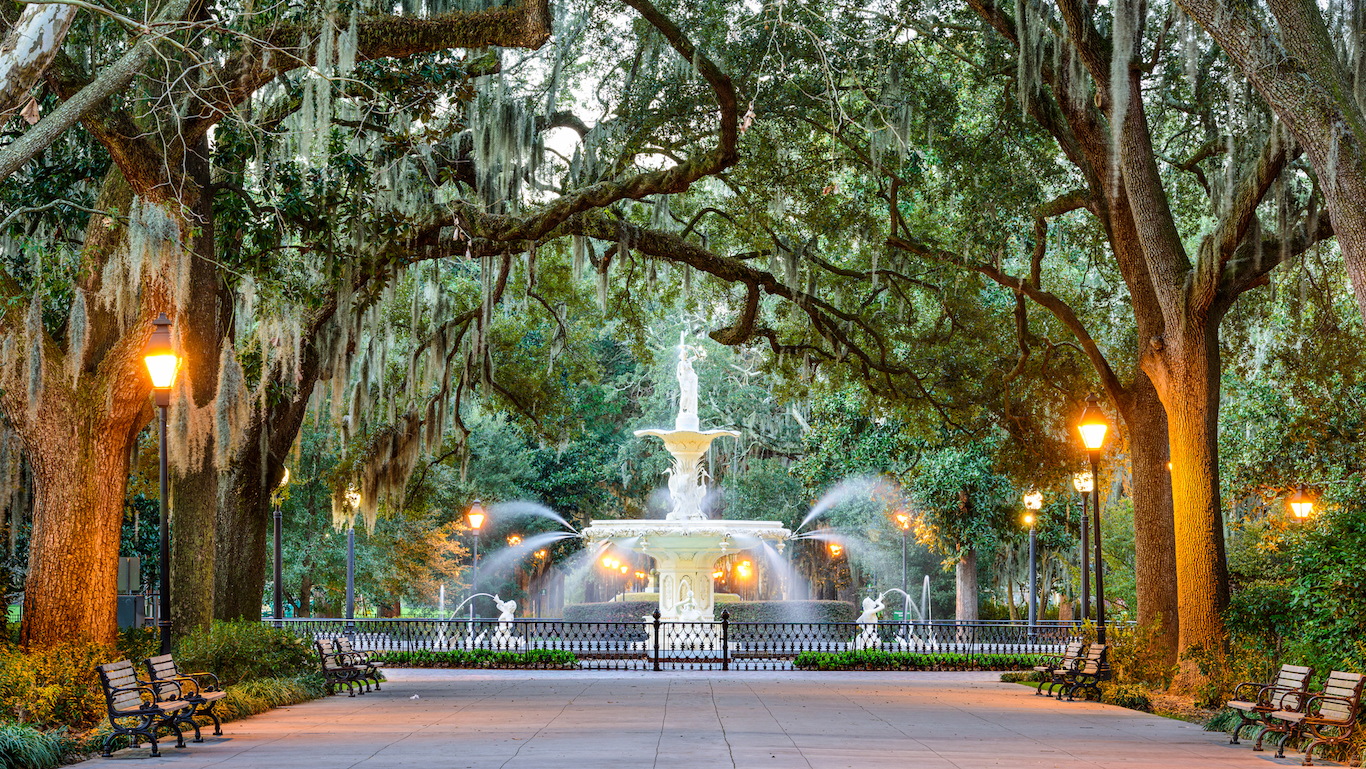
Some retirees who move to Savannah consider working as tour guides, drawing on their knowledge of the city’s history. It’s a common second-act idea. The plan is to move to the city, collect Social Security, and earn the difference by leading tours. This piece works through what that plan costs, what the work pays, and where the rules help or get in the way. It follows our earlier looks at retirees running side businesses from Montana cabins and Tennessee lake houses.
Why Savannah Can Fit a Modest Budget
Georgia’s cost-of-living index is 96.293, compared with a national 100, while Florida’s is 103.414. Savannah’s median rent is $1,800 a month, about 5.3% below the national median, and one-bedroom apartments citywide run around $1,500. Downtown one-bedrooms average $2,080. Buying a home is harder to make work, since Savannah’s FHFA home price index rose 63.5% over five years.
Plenty of visitors can guide the way. Georgia drew a record 175.6 million visitors in 2025, and they spent $46.2 billion.
Running the Budget Against Social Security
Take a single retiree, age 63, collecting the average retired-worker benefit of $2,071 a month. That’s $24,852 a year. Here’s a lean working budget of $40,000:
| Item | Cost |
|---|---|
| Rent, citywide one-bedroom | $1,500/month |
| Medicare Part B, from 65 (until then, budget for marketplace coverage) | $202.90/month |
| Electricity, Georgia average | $155.25/month |
| Subtotal for those three | $22,298/year |
| The remaining expenses include food, supplemental coverage, phone, car, renters insurance, federal tax, evacuation fund, reserves | $17,702/year |
That leaves a gap of $15,148 a year. Covering it with a 4% withdrawal rate would take about $378,700 in savings. That figure is a rough measure of the income the tours would replace.
What Guiding Pays and What the Rules Take
Savannah used to make guides pass a hundred-question history exam, a background check, and a physical. The city dropped that license in 2015, and a federal judge found the old system unconstitutional in 2019. The city still enforces tour rules. For example, Washington Square and the 400 and 500 blocks of East Saint Julian Street are closed to tours from 10:00 p.m. to 10:00 a.m., November 1 through February 28. Guides either work for an established company or run their own tours.
Overall, pay is lower, since tour guides nationally earn a median of $18.33 an hour. A guide who works independently owes 15.3% self-employment tax once net earnings reach $400. That tax covers both halves of Social Security and Medicare. To keep $15,148 after it, she’d need about $17,640 in tour profit. At the median wage, that works out to roughly 18.5 hours a week, all year. That is more than a few evening tours per week. Tips, private groups, or higher prices for independent tours would have to make up the difference.
The Social Security earnings test leaves room. Before full retirement age, the limit is $24,480, and the SSA reduces benefits by $1 for every $2 earned above it. Medicare’s higher-income surcharges don’t start until income passes $109,000 for single taxpayers.
How Georgia’s Tax Rules Work in Her Favor
Georgia does not tax Social Security, as residents aged 62 to 64 can also exclude up to $35,000 of retirement income. The Department of Revenue counts pensions, interest, dividends, and up to $5,000 of earned income toward that exclusion. That means only about $12,640 of her tour income is exposed to state tax.
The 2026 single standard deduction is $15,000, so her Georgia income tax at the 4.99% flat rate likely comes to zero. Federally, some of her benefits become taxable once half her Social Security plus other income passes $25,000, so a small federal bill belongs in the reserve fund.
Physical trade-offs include summer heat and humidity, which push most walking tours into the evening and mean hours on her feet. Hurricane season brings evacuation costs. Georgia homeowners’ premiums have climbed 48% since 2019. Renting keeps that cost off her own bill, though landlords tend to pass it along over time.
What It Takes to Make the Numbers Close
The plan works on roughly a $40,000 budget, a benefit near $2,071, rent at or under $1,500, and about $17,640 a year in tour profit. That’s close to half-time work at median pay, or fewer hours at independent rates. Waiting to claim Social Security, with the tours covering the meantime, would raise the monthly check for life and reduce the gap.
A cash cushion for hurricane season and slow months is part of the plan too. Her first tour usually comes one of two ways. She can take a seasonal spot with an established company that already has bookings, or build her own route and work around the city’s evening restrictions from the start.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.