How to Build $9,400 a Month in Dividend Income Without Selling a Single Share
The capital you need to retire on dividends alone swings by millions depending on one number, and chasing the wrong yield can quietly erode everything you built.
Most retirement advice is either too generic to use or too conflicted to trust. Save 15 percent. Follow the 4 percent rule. Move somewhere warm. Nobody shows you the assumptions underneath those rules or the conditions that break them. Meanwhile the decisions that move the most money get the least attention: which accounts to draw down first, what your tax bill looks like at 73, whether your state taxes your pension, what a year of healthcare costs before Medicare starts. Life After Work covers the whole transition — taxes, withdrawal strategy, healthcare, housing, location, and the rules of thumb that ought to be retired themselves. We work from the tax code, federal data, and real numbers so you can see what your retirement actually costs and what it will take to get there.
The 'Life After Work' desk starts with the rules as written and the data as published. Our editors work from IRS publications and annual limit and required-minimum-distribution guidance, the retirement provisions of the SECURE Act and SECURE 2.0, Department of Labor and Pension Benefit Guaranty Corporation filings, Social Security Administration actuarial and life expectancy tables, Medicare premium and income-related surcharge schedules from CMS, Bureau of Labor Statistics spending and inflation data, Federal Reserve household finance surveys, state revenue department treatment of retirement income, and Treasury yields, alongside peer-reviewed research on safe withdrawal rates. We run the calculations ourselves rather than repeating rules of thumb. Our goal is not simply to describe how retirement works, but to show you what each decision costs or saves you, in dollars, at your age and in your state.
The capital you need to retire on dividends alone swings by millions depending on one number, and chasing the wrong yield can quietly erode everything you built.
Most retirees assume hitting a $68,400 annual income floor demands either a massive nest egg or risky high-yield instruments, but five ordinary dividend stocks across five sectors challenge both assumptions in ways the math…
Most retirees chasing monthly income from covered-call ETFs gravitate toward the same two or three names, but a Goldman Sachs fund quietly running an 8.5% yield tells a more complicated story about how much…
Scottsdale keeps landing on retirement shortlists for real reasons, but the sticker price has quietly turned a solid thesis into an expensive assumption, and one Arizona city nearby keeps almost everything that matters at…
Turning $680,000 into a reliable monthly paycheck sounds straightforward until you discover that one of the three holdings pays quarterly and recently slashed its distribution. Here is how a blended sleeve of two net-lease…
Replacing nearly $47,000 a year in retirement income without touching principal sounds like a math problem, but the real trap is choosing the wrong yield tier and watching either your paycheck or your nest…
In 1983, one small state quietly rewrote the rules that had forced every family trust to eventually dissolve, and the legal structure it created lets you protect generational wealth from estate taxes without ever…
Swapping one covered-call ETF for another in an $890,000 income portfolio cuts your monthly check by roughly $2,000 a year, but the five-year price return tells a completely different story that most yield-chasing investors…
Inheriting a six-figure IRA sounds like a windfall, but one tax rule quietly turned a decade of patience into a single-year tax catastrophe that no amount of hindsight could undo.
A will, a remarriage, and two decades of life changes meant nothing to a 401(k) plan still honoring paperwork filled out before the divorce. The rules governing who actually wins that money are not…
William Randolph Hearst built a media empire, died in 1951, and somehow his trust is still running in 2026 without a single public filing. The legal trick his lawyers used is older than America,…
A little-known label on certain long-term care insurance policies can shield your savings from Medicaid's asset rules and protect your estate from state clawbacks after death, but the mechanics only work under a specific…
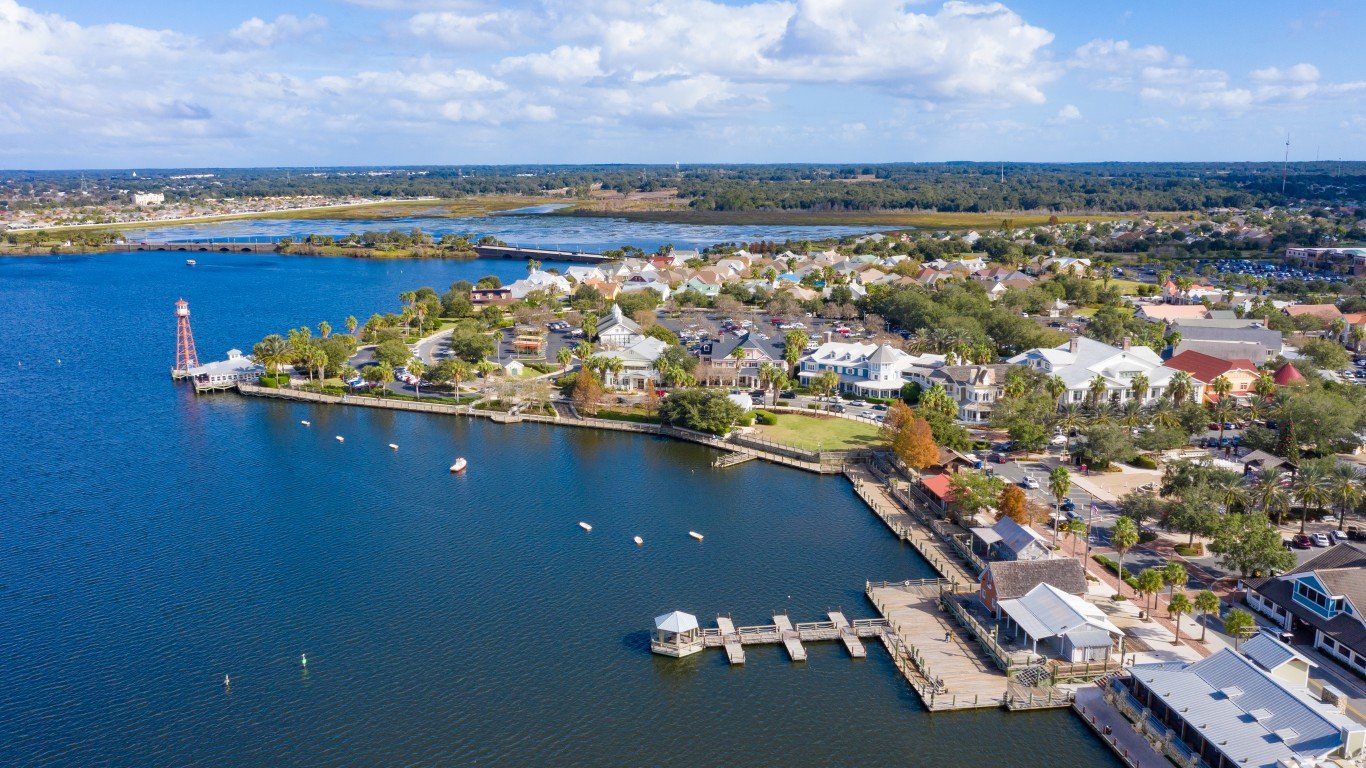
Most Villages homeowners know their amenity fee cold and dread their annual tax bill, but the bond attached to their property quietly waits until closing day to take center stage on the settlement sheet.
Retirees who run the numbers on leaving New York often feel confident they have thought of everything, but the move has a way of surfacing costs that never appear on any spreadsheet.
Retirees who run the numbers on The Villages before moving typically leave out the same three or four line items, and those omissions tend to surface within the first year in ways that force…