This Mag 7 Stock Is Worth Watching for the Next 5 Years
Alphabet just posted a blowout quarter and the stock fell anyway, leaving it trading nearly 15% below its 52-week high while one key growth engine accelerates at a rate that has Wall Street scrambling to keep up with its price…

The 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG | GOOG Price Prediction) is $434.49 over the next 12 months. With shares at $343.65, that works out to 26.43% upside. The stock earns a buy rating with 70% confidence, which is solid but measured conviction.
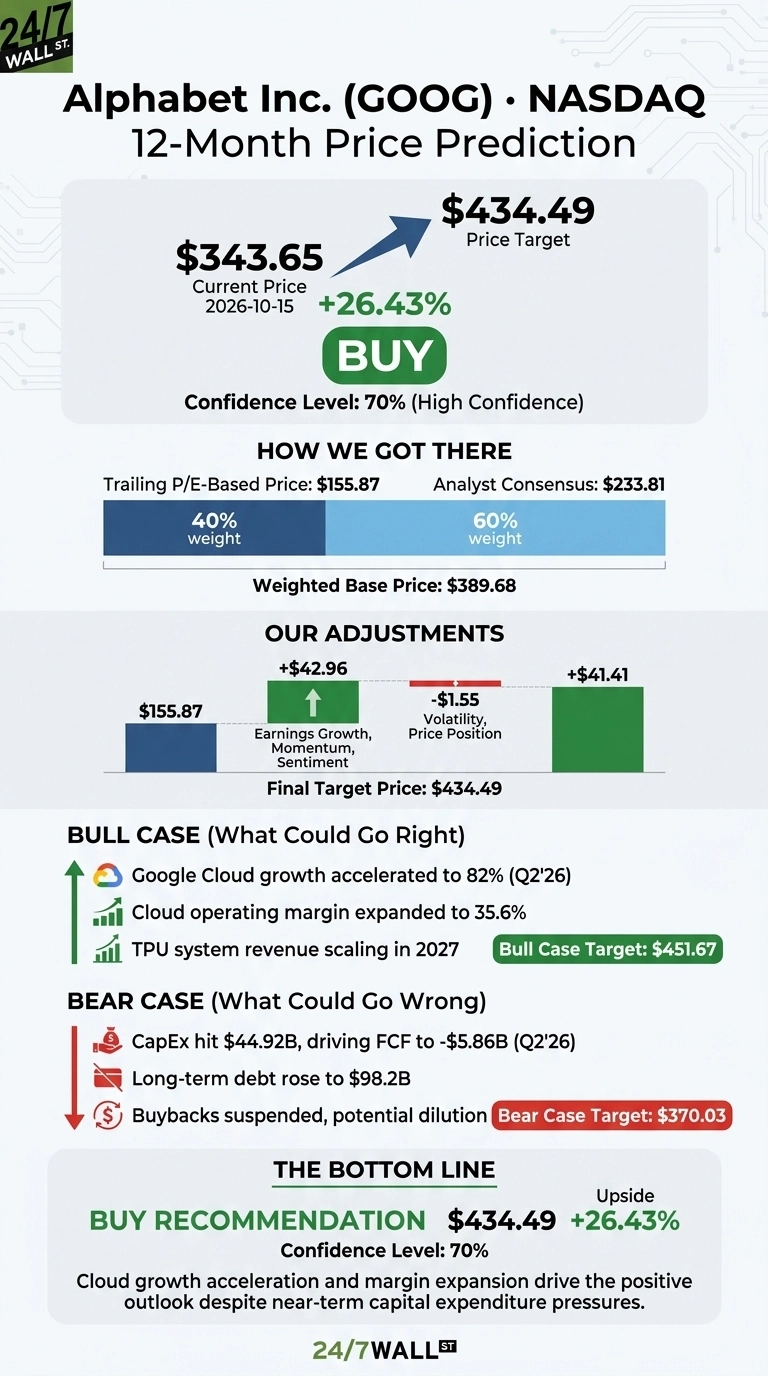

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $343.65 |
| Price Target from 24/7 Wall St. | $434.49 |
| Upside/Downside | 26.43% |
| Recommendation | BUY |
| Confidence Level | 70% |
Three things drive our call. Google Cloud growth sped up to 82% last quarter. Total revenue grew 24.2%. And the stock now sits well below its highs even as the business gets stronger.
A Blowout Quarter That Pushed Shares Lower
In Q2, Alphabet earned $9.11 per share against a $3.0427 estimate. Revenue came in at $119.796 billion, ahead of the $116.907 billion consensus. A $99.03 billion gain on equity securities inflated that EPS figure. The stock still fell 6.89% on earnings day.
Over the past week, shares moved -1.07%. Over the past month they moved -0.6%, and they are about 7.2% below their mid-July level. Year to date, the stock is up 9.73%. It trades 14.9% below its 52-week high of $403.96.
Why Bulls See $450 and Beyond
Cloud backlog reached $514 billion, and management expects to recognize just over half of it as revenue within 24 months. Cloud operating margin expanded to 35.6% from 20.7%. The Gemini app has 950 million monthly users.
The bulk of TPU system revenue is expected to arrive in 2027. The CEO described the opportunity this way: “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.” All of that TPU and cloud expansion has to be powered, cooled, and networked by someone, and we covered seven of those suppliers in a free AI infrastructure report.
Wall Street generally agrees. Analysts count 13 Strong Buys, 44 Buys and 5 Holds, with a consensus target of $420.36. We don’t have price targets from individual firms. Our bull case reaches $451.67.

Capex, Debt and Dilution Are the Risks Worth Watching
Capex hit $44.92B, which drove quarterly free cash flow to -$5.86B. The company’s long-term debt rose to $98.2B from $46.5B. Buybacks are suspended, and a stock sale program of up to $40B could dilute existing shareholders. Regulators also remain a risk, as the $3.5B European Commission fine showed.
Cash flow gives bulls a solid response. Trailing 12-month free cash flow is still $53.3 billion, backed by $185.7 billion in operating cash flow. The bear case still lands at $370.03, which is above today’s price.
Alphabet Trades at a Steep Discount to Microsoft and Meta
| Company | P/E | P/FCF |
|---|---|---|
| Alphabet | 14x | 58x |
| Microsoft | 30x | 59x |
| Meta Platforms | 27x | 35x |
Microsoft (NASDAQ:MSFT) is Google Cloud’s most direct AI infrastructure rival. Azure grew 43% last quarter, well below Google Cloud’s 82% rate. Even so, Microsoft trades at about twice Alphabet’s earnings multiple.
Meta Platforms (NASDAQ:META) competes for the same digital ad budgets and is spending heavily on AI too. Its revenue grew 27.96%, but quarterly free cash flow fell to $784 million. Alphabet’s P/E is lower partly because equity profits inflate its earnings. Even after allowing for that, the gap with both peers makes our target look conservative.
Alphabet Earns Our BUY Rating
The 24/7 Wall St. price target of $434.49 carries a buy rating and 70% confidence. The deciding factor for me is Cloud growth speeding up while margins expanded.
I’d grow more confident if TPU revenue scales on schedule in 2027. I’d turn cautious if capex keeps climbing while backlog growth stalls. On balance, I think the reward outweighs the risk.

The model projects Alphabet could trade at these levels if current growth trends and market conditions hold:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $366.54 |
| 2027 | $435.02 |
| 2028 | $518.10 |
| 2029 | $574.83 |
| 2030 | $642.85 |
The projections rest on Alphabet continuing to carry out its current strategy. The results could land well above or below these figures depending on Gemini 4’s launch, returns on AI spending and antitrust rulings.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.