Jefferies Loves These Chip Stocks to Buy in Automated Driving Space
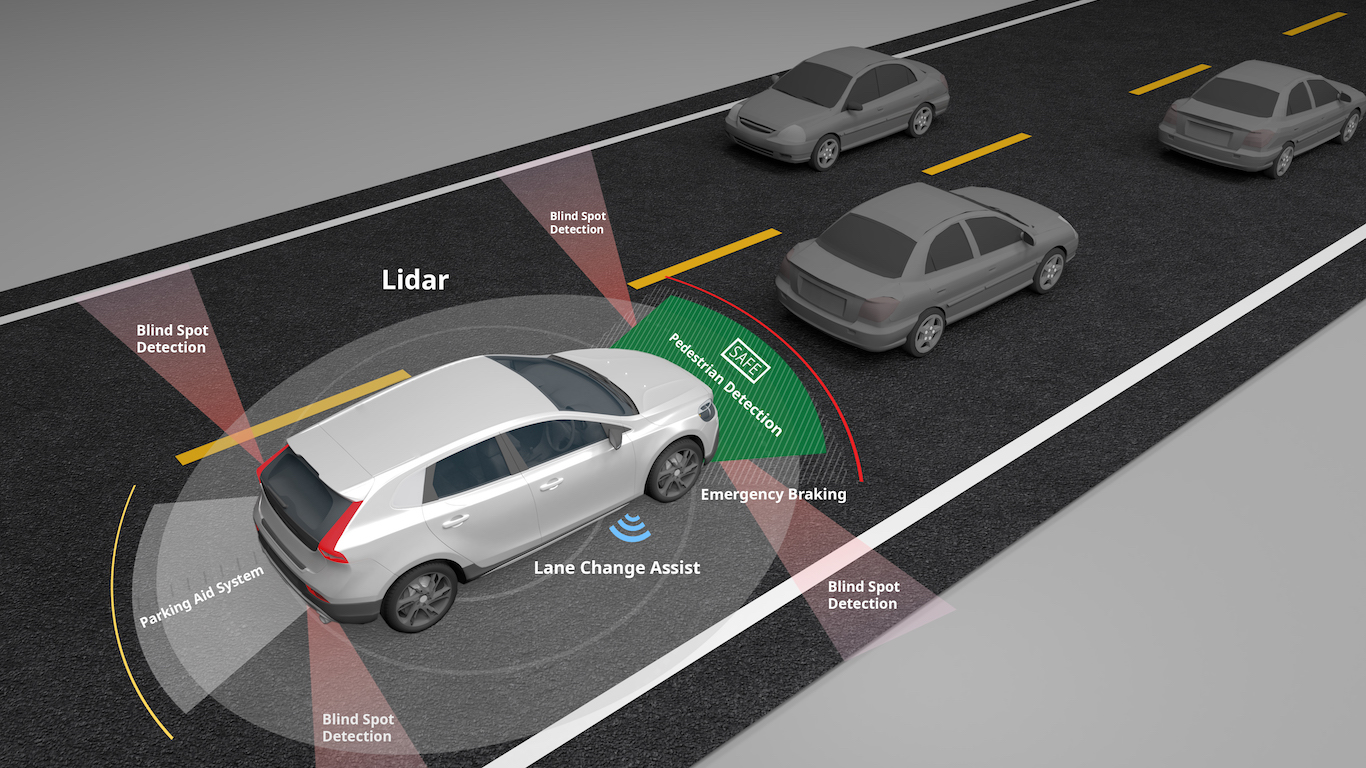
Analysts at Jefferies have named two autonomous driving technology suppliers as probable winners in the race to true self-driving vehicles.
While much of the focus has been on Volvo’s EX90 rollout, Luminar has quietly maintained a broader OEM pipeline. The company’s integrated sensing and perception platform has been validated in RFIs across multiple global automakers.
“We’re now positioned not just as a lidar supplier, but a full-stack solution provider for autonomy readiness.”
If the call includes even one new OEM engagement or production-level LOI, it could provide upside surprise beyond current volume assumptions
Contact [email protected] for any questions or corrections.
Luminar Technologies (LAZR) surged forward in Q1 2025 with a robust update to its strategic roadmap and a strong quarter of operational performance. The company announced a new unified product architecture that consolidates its LiDAR offerings into a single platform, marking a pivotal shift away from custom developments for each OEM. This simplification aims to drive down costs, bolster scalability, and accelerate Luminar’s path to profitability.
Luminar shipped ~6,000 LiDAR sensors in Q1, a 50% increase over Q4 2024, entirely driven by growth in automotive series production. Cumulative shipments now stand at approximately 14,000 units. Alongside production momentum, the company continues to deliver on its promise of cost control—quarterly non-GAAP OpEx is expected to be cut in half by the end of FY’25 compared to early FY’24 levels.
CEO Austin Russell emphasized the company’s operational focus: “This kicks off our new operating plan with a unified product platform, enabling radical focus and streamlining of the business.”
Milestones across Luminar’s 2025 plan—including tripling production volumes, advancing the next-gen Halo LiDAR, and transitioning customers to a singular tech stack—are all reportedly on track.
Despite the upbeat report, Luminar disclosed a late 10-Q filing, citing it will utilize a 5-day extension window and expects to file by May 20, 2025.
Still waiting on published materials detailing its new strategic plan and associated actions, cost savings, quarterly business update, and Q1 financials as promised by management. In a May 4th presser, these items were supposed to be shared by 4 pm Eastern. But should have them by time the webcast starts at 5 pm Eastern.
Luminar doesn’t segment revenue yet — it’s still early-stage — but its results hinge on two levers:
Series Production Lidar: Volvo EX90 and other OEM integrations now in revenue ramp phase
Perception Software & Sentinel Platform: Bundled autonomy stack in early-stage testing with key automakers
Shipment volume and contract conversion are what matter here. Any signal of >10K units shipped or expanded partner deployments could flip the revenue trajectory.
Luminar’s shares are still down 29% year-to-date even after a recent rally. However, it is notable that many stocks have seen even more robust rebounds in recent weeks.
For example, CoreWeave has jumped 84% from recent lows as investors flooded back to stocks that were sold during a rotation out of riskier stocks in late February through early April.
If Luminar can impress tonight, there’s a chance it could springboard the stock as its performance this year still badly lags the broader market.
Analysts expect Luminar to post EPS of –$1.63, a narrower loss compared to previous quarters, and revenue around $22 million. That would mark the second consecutive quarter of improved margins and year-over-year revenue growth.
Key modeling inputs:
Volvo EX90 lidar integration now underway
ASP improvement from contracted programs
SG&A scaling with production support
Luminar surprised to the upside in Q4 2024. For a repeat, the Street wants visibility on shipment volume and gross margin trajectory. Cash burn and order book disclosures could shape sentiment.
Analysts at Jefferies have named two autonomous driving technology suppliers as probable winners in the race to true self-driving vehicles.
Luminar Technologies (Nasdaq: LAZR) will report Q2 results after the market close, with revenue growth expected to remain muted amid a sharp narrowing of EPS losses. The report comes just one quarter after founder…
Mobileye (NASDAQ:MBLY | MBLY Price Prediction) and Luminar Technologies (NASDAQ:LAZR) both bet their futures on autonomous driving. One is building a real business around that bet. The other is fighting for survival. Their most…
A reverse merger between Luminar Technologies and a SPAC has added another entry into the race to bring fully autonomous driving to market.
J.P. Morgan has a positive view on the revenue opportunities in multiple end-markets for the LiDAR (light detection and ranging) industry.
Goldman Sachs has downgraded its outlook for Luminar Technologies to Sell.
After markets close on Tuesday, Warren Buffett's favorite oil company is scheduled to report quarterly results, along with a couple of electric vehicle firms, a vacation rental firm and a buy-now-pay-later company.
Editor’s note: Luminar Technologies filed for Chapter 11 bankruptcy and was delisted from Nasdaq. Its lidar business assets, including the Iris and Halo product lines, were subsequently acquired by MicroVision (NASDAQ:MVIS) in a bankruptcy…
Ford has abandoned its self-driving vehicle investment and taken a huge write-down. Will self-driving cars ever be all over the world's roads?