This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Live coverage has ended. The full story is below.
Palo Alto Networks (NASDAQ: PANW | PANW Price Prediction) enters earnings up +21% over the past month and +7.5% year-to-date, reflecting renewed optimism following a surprise guidance reset last quarter. Analysts expect EPS of $1.32 GAAP / $2.86 non-GAAP on $2.49 billion in revenue, which would mark a 12% YoY decline in revenue and a near-40% drop in EPS compared to last year’s $4.75 blowout Q3.
The company has beaten EPS in 3 of the past 4 quarters but missed sharply last quarter, sending shares down –15%. FY25 EPS consensus is $13.72 (non-GAAP), slightly below FY24, and investors are focused on a second-half reacceleration. A soft quarter could reinforce bear concerns that AI-led cybersecurity tailwinds are overstated.
Cybersecurity in the Crosshairs of AI and Budget Cycles
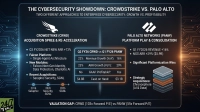
The cybersecurity sector continues to straddle two opposing forces: sustained long-term demand from cloud, AI, and zero-trust adoption, and near-term budget rationalization across enterprise and government customers. Peer results have been mixed — CrowdStrike beat and raised, Fortinet issued cautious commentary, and Zscaler warned of elongating deal cycles.
Palo Alto’s exposure to federal and large enterprise deals means it’s particularly sensitive to macro-driven delays. The broader security market remains in transition from platform consolidation (XDR, SASE) to AI-enhanced threat detection, and investors want clarity on whether those shifts are monetizing today or still aspirational.
Contact [email protected] for any questions or corrections.