Live coverage has ended. The full story is below.
Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) reports Q1 fiscal 2026 earnings on May 4, 2026, after market close. Shares trade at $147.83, down 18.95% year to date despite a 23.98% one-year gain. Here is what investors should keep an eye on.
The Numbers That Matter
- EPS consensus: $0.28 non-GAAP
- Revenue consensus: $1.54 billion; Management guidance of $1.532B to $1.536B
- Adjusted income from operations guidance: $870 million to $874 million
Prediction markets price 66.0% odds of exceeding 1,000 customers, up from 954 at year-end
What Happened Last Quarter
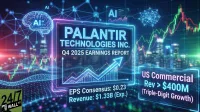
Q4 2025 delivered $1.406 billion in revenue (70% YoY) and adjusted EPS of $0.25, beating estimates by 38.89%. Three takeaways:
- U.S. commercial revenue grew 137% YoY to $507 million, with remaining deal value up 145%.
- CEO Alex Karp said “Palantir’s Rule of 40 score is now an incredible 127%” and guided FY2026 revenue to $7.182 billion to $7.198 billion (61% YoY growth).
- The reaction was harsh, with shares dropping 11.62% the day after the release due to valuation concerns.
Management promised U.S. commercial revenue in excess of $3.144 billion (at least 115% growth) for FY2026.
The Sector Setup
AI software peers have set a high bar this season, with hyperscaler capex commentary supporting demand for enterprise AI platforms. Palantir’s Q4 net dollar retention of 139% and $4.262 billion total contract value (138% YoY) suggest AIP adoption is widening.
However, Palantir continues to trade at a steep valuation, with current multiples of 112x forward earnings and 77x sales.
What Could Move the Stock
Bull case triggers:
- Revenue above the $1.536 billion guide high end
- U.S. commercial growth above 130% YoY
- FY2026 revenue guide raised above $7.20 billion with operating margin commentary near 45%
Bear case triggers:
- Revenue below the $1.532 billion floor
- U.S. commercial deceleration
- Operating margin compression
Wild cards: rising stock-based compensation, which hit $684 million in FY2025; a streak of 72 recent insider transactions trending toward selling; and tariff/trade exposure cited in management risk factors.
What to Watch
Last quarter’s blowout was met with an 11.62% next-day decline, a reminder that beats alone do not satisfy this multiple. The pressing questions for tonight are whether U.S. commercial can sustain triple-digit growth, whether management will raise the FY2026 guide on the back of $11.2 billion in remaining deal value, and whether adjusted operating margin pushes back toward the Q4 high of 57%? Answers will shape whether Palantir grows into its valuation or tests support near the 200-day moving average of $164.30.
Contact [email protected] for any questions or corrections.