Price Prediction: Intel Stock Surge Hides Risk of Sharp Drop Ahead
I’ll cut to the chase. Intel (NASDAQ: INTC | INTC Price Prediction) has been one of the most extraordinary turnaround stories of the past year, with shares up 466.75% over the trailing 12 months and 206.26% year to date. But…

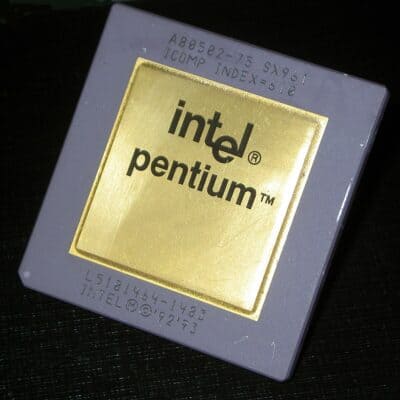
I’ll cut to the chase. Intel (NASDAQ: INTC | INTC Price Prediction) has been one of the most extraordinary turnaround stories of the past year, with shares up 466.75% over the trailing 12 months and 206.26% year to date. But after that run, the math is stretched. Our 24/7 Wall St. price target for Intel is $88.66, which implies meaningful downside from current levels.
| Metric | Value |
|---|---|
| Current Price | $113.01 |
| 24/7 Wall St. Price Target | $88.66 |
| Upside/Downside | -21.54% |
| Recommendation | SELL |
| Confidence Level | 90% |
Why We Could Be Wrong
Before going further, our price target of $88.66 sits below where Intel trades today, and INTC is one of the most divisive names in semiconductors. Real upside could come from Intel 18A winning a marquee external foundry customer, or from agentic AI workloads driving the CPU-to-GPU ratio toward parity as CEO Lip-Bu Tan suggests. Treat our target as one datapoint. The full bull case follows below.

From $20 to $113: How Intel Re-Rated
Intel closed at $113.01 on May 6, up 19.27% in a week and 122.55% over a single month.
The catalyst was Q1 FY2026, reported April 23, 2026. Intel posted non-GAAP EPS of $0.29 on revenue of $13.58 billion, beating revenue estimates by 9.22% and growing 7.18% YoY. Data Center and AI revenue jumped 22% to $5.05 billion and Intel Foundry rose 16%. A $4.07 billion Mobileye goodwill impairment produced a GAAP loss, but the operational story improved.

Why Bulls See a Breakout Ahead
The bull case rests on three pillars. First, Lip-Bu Tan’s claim that “The ratio of CPU to GPUs used to be 1-to-8, and now it is 1-to-4, and I think it could move towards parity or even better.”
Second, the multiyear Google partnership on custom ASIC IPUs and Xeon 6 selection as the host CPU for NVIDIA’s DGX Rubin NVL8.
Third, advanced packaging demand running at “billions of dollars per year”. If 18A wins external commitments and the ASIC business compounds off its current north of a billion dollar run rate, INTC could push toward our bull-case $98.52 ceiling, with peaks near $116.38.

The Risks Worth Watching
Skeptics anchor on valuation. Forward P/E sits at 119, and the “Intel trading at a 119x forward P/E and nobody is talking about this” post lit up r/stocks. Free cash flow remains negative at -$3.87 billion,
Intel Foundry posted a $2.4 billion operating loss, and management has flagged a possible pause of Intel 14A absent customer demand. Bulls would counter that the GAAP loss is dominated by the one-time $4.07 billion Mobileye impairment, that non-GAAP gross margin expanded to 41%, and that the balance sheet now carries $17.25 billion in cash. Still, a bear-case path drops INTC to $66.88.

The Risk Isn’t Worth the Reward Yet
My 24/7 Wall St. price target stays at $88.66 with 90% confidence and a sell rating. The execution at Intel is real, but a stock that has more than quintupled in a year now requires near-flawless delivery to justify a 119 forward P/E.
I’d revisit constructively if 18A lands a major external foundry customer or Q2 prints toward the high end of the $13.8 billion to $14.8 billion guide. I’d stay sidelined if PC TAM weakens as guided or Foundry losses widen.
Intel Price Prediction 2026-2030
Looking further out, here is where our model projects Intel could trade, blending the 5-year scenario range with normalization toward forward earnings power.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $88.66 |
| 2027 | $84.00 |
| 2028 | $80.00 |
| 2029 | $78.00 |
| 2030 | $75.99 |
These projections assume Intel continues executing on Tan’s reset strategy. Significant upside or downside could result from 18A foundry traction, server CPU share dynamics versus AMD, or shifts in CHIPS Act and tariff policy.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.