Why Verizon Is One of Our Top Defensive Picks In 2026

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
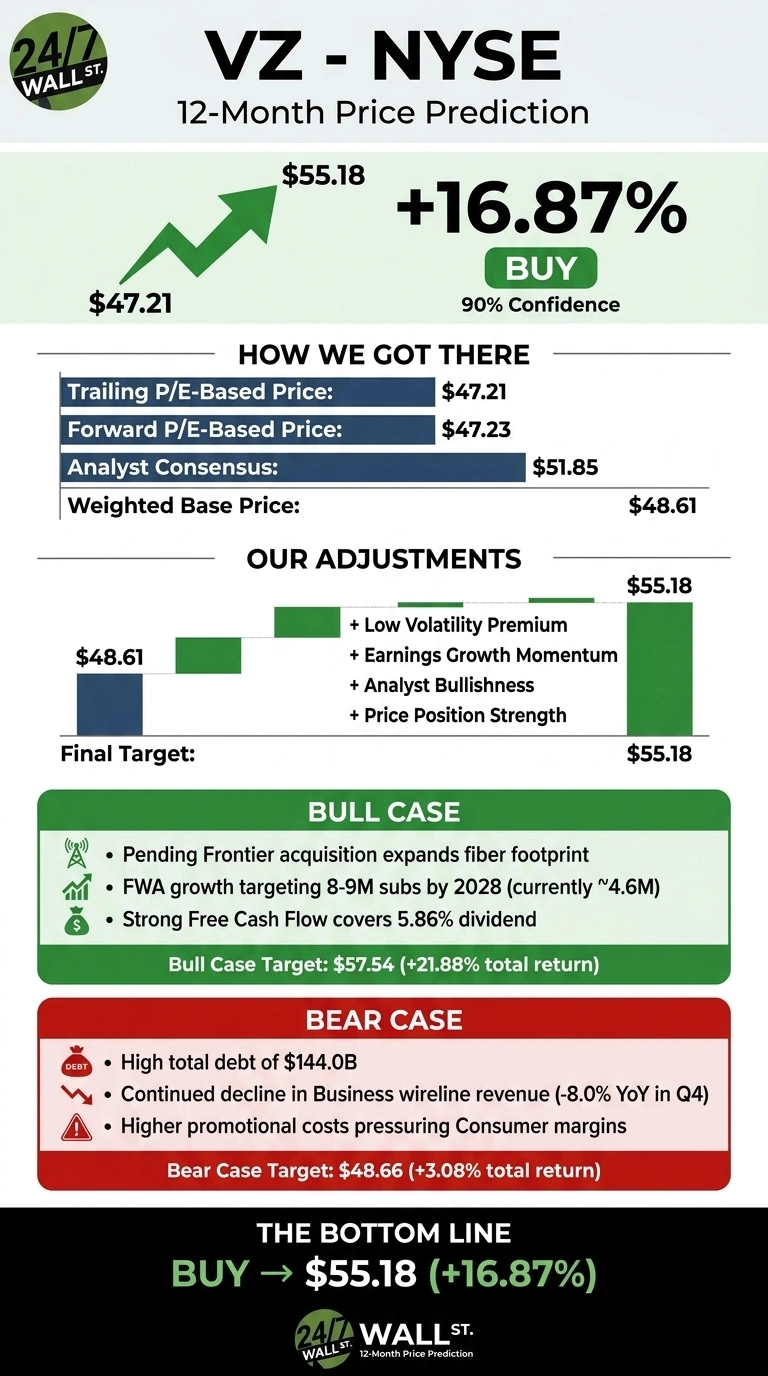
Our Verizon (NYSE:VZ | VZ Price Prediction) call is straightforward: the stock is undervalued, the dividend is well covered, and the model points to meaningful upside over the next 12 months. With shares trading at $47.21 as of May 13, 2026, our 24/7 Wall St. price target for Verizon is $55.18, implying 16.87% upside. Our recommendation is buy with a 90% confidence level, which we consider high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $47.21 |
| 24/7 Wall St. Price Target | $55.18 |
| Upside | 16.87% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Quiet Rerating Has Already Begun
Verizon has been one of the better-performing defensive names in 2026. Shares are up 19.73% year to date and 18.19% over the past year, with the stock recovering sharply from a $39.36 low in January 2026 to within striking distance of the $50.91 52-week high.
The most recent earnings report (Q4 2024) showed revenue of $35.68 billion, beating expectations, alongside EPS of $1.10 in line with estimates. The standout was operations: 568,000 postpaid phone net adds, the best in over a decade, and FWA revenue of $611 million, up 51.6% YoY.

The Case for $57+
Bulls focus on three catalysts. First, the pending Frontier Communications acquisition meaningfully expands Verizon’s fiber footprint and gives it a credible converged offering against cable.
Second, FWA is on a tear, with management targeting 8 to 9 million subscribers by 2028 versus roughly 4.6 million today.

Third, free cash flow of $19.82 billion in 2024 comfortably covers the 5.86% dividend yield. Our bull case scenario points to $57.54, a 21.88% total return. Insider confidence supports the read: senior executives including CEO Hans Vestberg and CFO Anthony Skiadas have been steady buyers through March and April 2026.

The Risks Worth Watching
The bear case centers on the $144 billion debt load and continued declines in legacy business wireline, which fell 8% YoY in Q4. Higher promotional spend is also pressuring consumer margins. Our bear case scenario points to $48.66, still a positive 3.08% total return when factoring the dividend. It should be noted that the high debt reflects multi-year C-Band buildout that is now monetizing through FWA, and capex already fell from $18.77 billion in 2023 to $17.09 billion in 2024.

Verizon Price Prediction 2026-2030
The 24/7 Wall St. price target stands at $55.18 with a buy rating and 90% confidence. The tipping factor is valuation: at a forward P/E near 10, you are getting a defensive cash flow machine for less than the market multiple. The setup favors investors seeking yield plus modest capital appreciation. Key risks to monitor include a sharp spike in rates or a collapse of the Frontier deal.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $55.18 |
| 2027 | $62.08 |
| 2028 | $67.47 |
| 2029 | $72.47 |
| 2030 | $77.49 |
These projections assume Verizon executes on FWA, closes Frontier, and holds dividend coverage. Significant upside or downside could come from interest rate moves or a competitive break in wireless pricing.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.