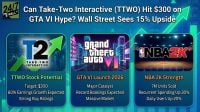
Take-Two’s latest results showed that the company is already operating at a much higher baseline than during previous launch cycles. Fiscal 2026 net bookings reached $6.72 billion, while recurrent consumer spending grew 7% year over year and made up 82% of Q4 bookings.
Recurring spending from GTA Online, NBA 2K, mobile, and live-service titles is now carrying far more of the business between major releases. Instead of relying almost entirely on one blockbuster launch, Take-Two enters the GTA VI cycle with a large and highly monetized recurring revenue engine already in place.
Management’s guidance reinforced how large they expect the next step-up to be. Take-Two forecast up to $8.2 billion in FY27 net bookings and said GTA VI should drive “new record levels of operating performance” after launching on November 19, 2026.
The company also emphasized strong expected cash flow generation, which could give Take-Two significantly more financial flexibility after launch across acquisitions, development spending, and shareholder returns.
Most of the attention around Take-Two is rightfully focused on GTA VI, but management just revealed something else important.
The company expects to release 6 launches during fiscal 2027 alongside GTA VI and 22 titles across fiscal 2028 and 2029.
This shows the company is building a broader pipeline across sports, mobile, live-service, and core AAA franchises simultaneously, and that operating cash flow is expected to soar.
Investors are increasingly viewing Take-Two less as a “one game story” and more as a scaled entertainment platform with one of the deepest pipelines in gaming.
GTA V became one of the biggest entertainment products ever created. The game generated $1 billion in just three days, making it the fastest-selling entertainment launch in history at the time.
What’s crazier is how long the success lasted. More than a decade later since its initial launch in 2013, GTA V has shipped over 225 million copies and generated nearly $10 billion in revenue through game sales and GTA Online.
It’s no wonder investors are so excited for the GTA VI launch. GTA V turned into a permanent cash machine for Take-Two across multiple console generations, and the gaming market today is much larger than it was in 2013. Investors are now trying to figure out just how big the next version can become, especially in terms of LTV after the game’s initial sale.
We all know investors are waiting on the edge of their seats for GTA VI’s launch on November 19, 2026.
But while we wait, Take-Two’s latest results showed strong recurring spending, with recurring consumer spending growing 7% year over year in Q4 and representing 82% of total bookings, driven by GTA Online, NBA 2K, and mobile titles.
Take-Two now expects more than $1 billion in FY27 operating cash flow alongside the November 19 GTA VI release. Importantly, FY27 guidance came in below some Wall Street expectations despite the confirmed launch date.
That suggests management is taking a conservative approach to timing and revenue recognition rather than signaling weaker demand. CEO Strauss Zelnick still said FY27 should deliver “new record levels of operating performance.”
Zelnick: “new record levels of operating performance”.
Take-Two Interactive (NASDAQ:TTWO) delivered the setup investors wanted: scale, cash generation, and a firm GTA VI date. Insider selling and a 59 neutral Reddit read keep this short of an A+.
Take-Two’s latest earnings report showed strong underlying momentum ahead of what management believes will be one of the biggest entertainment launches ever.
Fiscal 2026 net bookings rose 19% year over year to a record $6.72 billion, while recurrent consumer spending remained strong across GTA Online, NBA 2K, and mobile.
The bigger story came from guidance. Management officially confirmed Grand Theft Auto VI will launch on November 19, 2026 and said fiscal 2027 should deliver “new record levels of operating performance.” Take-Two now expects up to $8.2 billion in FY27 net bookings and more than $1 billion in operating cash flow as GTA VI begins reshaping the company’s financial profile.
Importantly, the business is entering the launch cycle from a position of strength. Recurrent spending accounted for 82% of Q4 bookings, giving Take-Two a much larger recurring revenue base than during previous GTA launches.
Take-Two just reported earnings, with shares initially up about 5% following the report. Here are the key numbers:
Revenue: $1.68B vs. expectations around $1.66B
Adjusted EPS: -$0.32 vs. -$21.08 YoY
Net Bookings: $1.58B vs. guidance around $1.39B
Guidance:
FY27 Net Bookings: $8.0B–$8.2B
FY27 Revenue: $7.9B–$8.1B
FY27 EBITDA: $1.01B–$1.07B
GTA VI launch confirmed for November 19, 2026
Quick read:
Take-Two delivered strong bookings growth ahead of GTA VI, with recurrent consumer spending remaining resilient across GTA Online, NBA 2K, and mobile.
Management’s FY27 outlook signals expectations for record operating performance as GTA VI begins reshaping the company’s earnings and cash flow profile.
With shares at $238.185, here’s what to watch when Take-Two (NASDAQ:TTWO) reports after the close.
Management’s Q4 guide frames Net Bookings at $1.51B to $1.56B, GAAP revenue $1.573B to $1.623B, EPS ($0.70) to ($0.54), and EBITDA $138M to $161M. The Street’s average target sits at $277.06, with 26 buys, 1 hold, and 1 sell.
KPIs to track: recurrent consumer spending, NBA 2K26 traction, and Zynga mobile trends.
Recent action: the Q3 report triggered a -5.38% day-of move on an EPS miss, though shares recovered +6.91% over 30 days. Reddit sentiment reads 59, neutral.
Triggers: upside if bookings clear $1.56B or FY27 commentary frames GTA VI scale. Downside if bookings slip below $1.51B, losses widen past ($0.70), or any GTA VI timing wobble surfaces.
Tonight’s headline numbers matter less than what Strauss Zelnick says about fiscal 2027. Wall Street is modeling fiscal 2027 bookings of $9.4 billion, and the whisper bar sits above $8 billion in Net Bookings tied to GTA VI.
Management has historically under-promised and overdelivered: the FY2026 Net Bookings outlook was raised three consecutive quarters, ending at $6.65B–$6.70B. That conservative cadence sets a high bar for tone, not just numbers.
Bullish scenario: Reaffirming the November 19, 2026, GTA VI date, a Q4 raise above $1.56B, and a path to GAAP profitability.
Bearish scenario: Any slippage language, withheld FY27 guide, or recurrent spending mix slipping below 76%. Investors also want clarity on EBITDA trajectory beyond the current $657M–$681M range.
With Take-Two Interactive (NASDAQ:TTWO) shares at $240.25 and down 7.58% YTD, here are 5 questions analysts will likely ask about on tonight’s earnings call:
Top 5 Analyst Questions
Is the November 19, 2026 GTA VI date firm, with pricing and edition strategy locked?
Can management quantify FY2027 “record” Net Bookings and the path to enhanced profitability?
Is GTA Online recurrent consumer spending, 76% of Net Bookings, sustainable into launch?
How is the Zynga mobile portfolio trending post-impairment?
What is the marketing spend ramp embedded in Q4 EBITDA guide of $138M-$161M?
Topics to Address
FY2026 Net Bookings reaffirmation at $6.65B-$6.70B
WWE 2K26 reception
Judas and next BioShock timing
Red Flags
Any GTA VI slippage hint
Decelerating recurrent spending
Fresh impairments after the prior $3.55B goodwill write-down
Take-Two’s upcoming Q4 earnings report tonight gives investors one of the final clean looks at the business before Grand Theft Auto VI reshapes the company’s financial profile.
Investors will focus heavily on mobile trends, NBA 2K monetization, and overall balance-sheet strength ahead of the biggest game launch in years.
If management reinforces confidence in fiscal 2027 and maintains expectations for GTA VI, sentiment toward the stock could improve quickly. A weaker guide would likely pressure the premium investors are already assigning to the launch cycle.
Wells Fargo kept its bullish rating on Take-Two even as it slashed near-term estimates, and the reasoning behind that contradiction reveals just how much is riding on a single game release.
Take-Two missed on revenue and bookings, yet investors still piled in. One cryptic line from the CEO about GTA VI changed the mood, but rate-hike fears and a launch date loom as the real…
Take-Two missed badly on bookings just before its biggest launch ever, yet nearly every analyst still says buy. The real question is whether GTA VI's first weeks reward that confidence or expose it, and…
Take-Two Interactive (NASDAQ: TTWO | TTWO Price Prediction) has delivered a solid 2025, with shares up approximately 36% from their 52-week low of $177.35 and trading near recent highs. The rally has been fueled…
Roblox cratered while its closest gaming peers held up far better, but before you rush to rotate, check whether any corner of this sector actually rewarded investors when the broad market was busy setting…
Credo Technology carries 8 straight EPS beats into tonight's report, but a stock priced at 40 times forward earnings and a 3.2 beta leaves almost no room for anything short of a blowout. Watch…
Broadcom carries a $1.75 trillion market cap and AI revenue expectations that have already punished the stock twice for merely beating estimates. Tonight, the real question is whether Hock Tan's Q4 guidance can finally…
Arm Holdings reports earnings tonight after a brutal 30% pullback, and four specific metrics will determine whether the AI data center bull case still holds or the stock has further to fall.
Cisco heads into tonight's Q4 report near all-time highs after a monster AI-driven run, but with consensus pinned at the very top of management's guidance range and margin pressure lurking beneath record revenue, one…