The AI ‘Memory Wall’ Is About to Get a Lot Taller: These 3 Stocks Will Win Big
Nvidia's GPUs keep getting faster, but a deeper problem is quietly throttling AI's progress and reshaping where the next wave of infrastructure spending lands. Three stocks are positioned to profit from the shift.

Artificial intelligence has been defined by a relentless race for more computing power. Nvidia (NASDAQ:NVDA | NVDA Price Prediction) GPUs became the stars of that story because they delivered the horsepower needed to train ever-larger AI models. But every technology boom eventually runs into a new constraint.
According to a recent Morgan Stanley report, that next hurdle is not computing power. It is memory. As AI models grow larger and inference workloads become more demanding, data centers need far more memory bandwidth and capacity to keep expensive accelerators fed with data. That shift could reshape where hundreds of billions of dollars in AI infrastructure spending flows over the rest of the decade.
The Memory Wall Is Becoming AI’s Biggest Challenge
Morgan Stanley argues memory is becoming the new bottleneck for AI systems, a phenomenon long known in computing as the “memory wall.” GPUs continue getting faster, but they spend more and more time waiting for data to arrive from memory rather than actually performing calculations. The gap between processor speed and memory throughput is the core tension driving the next wave of infrastructure investment.
The numbers help explain why this matters at scale. Morgan Stanley estimates memory will account for roughly 40% of cloud and data center capital spending by 2030, up from only about 12% today. That increase reflects growing demand across several categories:
| Memory Segment | Primary AI Role | Leading Companies |
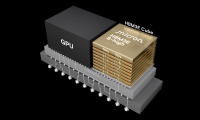
| High-Bandwidth Memory (HBM) | Feeds AI accelerators with massive data throughput | SK Hynix (NASDAQ:SKHY), Micron Technology (NASDAQ:MU), Samsung |
| Server DRAM (DDR5+) | Expands memory capacity for inference and larger AI models | SK Hynix, Micron, Samsung |
| CXL Memory Expansion | Pools and expands memory across AI servers | Marvell Technology (NASDAQ:MRVL), SK Hynix, Micron |
| NAND Flash Storage | Stores AI datasets and checkpoints | SK Hynix, Micron, Samsung |
Consider what this means for how AI infrastructure money flows. Every dollar hyperscalers spend on AI servers increasingly requires another dollar supporting the memory ecosystem. That broadens the investment opportunity well beyond GPU manufacturers.
Morgan Stanley identifies several categories where pressure will build most, and three publicly traded companies appear positioned to benefit across multiple segments.
SK Hynix (SKHY)
SK Hynix remains the purest memory play in the public markets. The company holds roughly 50% of HBM revenue globally, according to Counterpoint Research’s Q2 2026 data, maintaining its lead even as Samsung has ramped HBM4 shipments aggressively and now claims about 33% of the market. That competitive pressure is real, but SK Hynix’s early lead in HBM3E qualification with Nvidia and its reported allocation advantage on Nvidia’s next-generation Rubin platform mean its position at the top is not easily displaced. Beyond HBM, it also maintains major positions in DRAM and NAND, allowing it to benefit regardless of which part of the AI memory hierarchy grows fastest.
Micron Technology (MU)
Micron is closing the gap steadily. The company has secured long-term HBM supply agreements with hyperscale customers while expanding production of AI-optimized DRAM, and Counterpoint Research placed Micron’s HBM revenue share at about 18% in Q2 2026. Unlike previous memory cycles driven by smartphones or PCs, AI demand is creating longer product cycles and richer pricing, with HBM3E stacks trading well above standard DRAM. That dynamic could support stronger margins than investors have historically expected from memory manufacturers, and Micron’s later entry into HBM means it still has room to gain allocation.
Marvell Technology (MRVL)
Marvell Technology offers a structurally different way to profit from the memory buildout. Rather than manufacturing memory chips, Marvell develops CXL controllers, switches, and memory expansion technology that lets AI servers share and pool memory more efficiently. According to Morgan Stanley, the CXL memory controller chip market is expected to more than double in size to $2.1 billion. Marvell’s Structera product line hits all three CXL categories expected to surge. Data center revenue now accounts for 74% of Marvell’s total sales for fiscal 2026, a figure that climbed to 79% in its most recent quarter as hyperscaler AI spending continued to accelerate. Full-year fiscal 2026 revenue reached a record $8.2 billion, up 42%, and the company’s market cap has grown to over $200 billion, a dramatic expansion that reflects how central Marvell has become to AI infrastructure.
Key Takeaway
AI’s next growth phase may depend less on adding more GPUs than on ensuring those processors never sit idle waiting for data. Morgan Stanley’s projection that memory spending could climb from 12% to 40% of cloud infrastructure investment by 2030 represents one of the largest potential realignments of AI capital in the coming years.
Memory has always been a cyclical business, and supply expansions can pressure pricing. AI is nonetheless creating structural demand for higher-value products like HBM and CXL-enabled memory systems that simply did not exist during previous cycles. The shift from commodity memory to performance-critical AI memory is what makes this moment different from prior booms and busts.
For investors looking beyond Nvidia, SK Hynix, Micron, and Marvell each capture a different slice of the memory wall opportunity. As that wall grows taller, these companies may prove to be some of the most important builders helping the industry climb over it.
Editor’s note: This update corrects SK Hynix’s HBM revenue market share from 58% to roughly 50% per Counterpoint Research’s Q2 2026 data, reflects Samsung’s rise to 33% in that market, updates Marvell’s market cap to over $200 billion and its data center revenue share to 74% for fiscal 2026 (rising to 79% in its most recent quarter), and adds Marvell’s record fiscal 2026 revenue of $8.2 billion.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.