Mark Cuban: ‘A Lot of Data Centers Are Going To Be Turned Into Pickleball Courts’
Mark Cuban sold Broadcast.com at the peak of the dot-com boom, so when he warns that billions in AI infrastructure spending could end up repurposed for pickleball, investors who remember 1999 might want to pay attention.

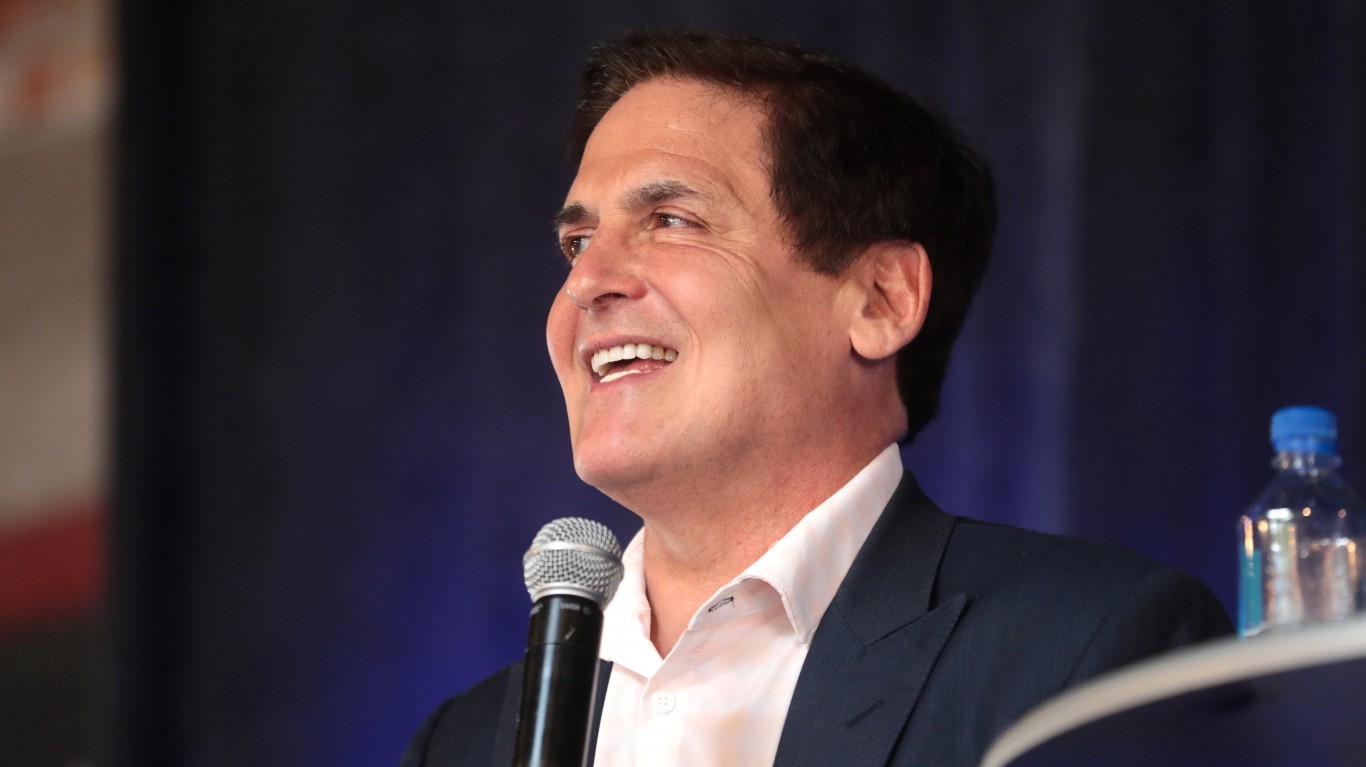
Billionaire investor Mark Cuban has a new metaphor for the AI infrastructure boom, and it doubles as a plug for one of his side projects. On the latest episode of the All-In podcast, Cuban warned that “if there’s a price-performance curve on AI that minimizes the power requirements, there’s going to be a lot of data centers that are going to be turned into pickleball courts.” The line carries extra weight given that Cuban co-owns the Dallas Flash pickleball team. For investors tracking both the “AI bubble” narrative and the AI infrastructure overbuild thesis, the argument deserves a serious look.
Cuban brings genuine dot-com-era operator credibility to this debate. The Yahoo acquisition of Broadcast.com was announced on April 1, 1999, valuing the company at $5.7 billion in stock, right at the peak of internet mania. That exit, timed almost perfectly at the top, gives his overbuild warning real authority, even if the pickleball punchline is doing most of the work on social media.
The Efficiency Argument
Cuban’s core view is that hyperscalers like Meta and Alphabet are right to expect AI usage will keep climbing. His concern is what comes next. He argues that “technological breakthroughs” will make AI dramatically cheaper and more power-efficient over time, and if that happens, a large share of the computing capacity being poured into the ground today will prove far larger than demand ever required.
His go-to historical parallel is the late-1990s fiber-optic buildout. Telecoms overbuilt long-haul networks, connection speeds then improved dramatically, and in Cuban’s telling “there wasn’t a bandwidth problem anymore.” Jason Calacanis noted on the same episode that the result was “dark fiber” sold for “pennies on the dollar.” Cuban sees exactly the same price-performance curve playing out in AI compute. On Big Tech’s habit of spending all available cash flow on capital expenditures and then borrowing on top of that, he called it “planning for perfection, and that’s going to be hard,” adding that “nobody can predict that well.”
The scale of what is being planned makes the warning harder to dismiss. The capital expenditure of the 14 largest publicly traded data center operators globally is tracking close to $750 billion for 2026 alone, according to BloombergNEF. PIMCO estimates combined hyperscaler capex will consume roughly 94% of operating cash flow in 2026 and 2027. Goldman Sachs projects total hyperscaler capex from 2025 through 2027 at $1.15 trillion, more than double the $477 billion spent from 2022 through 2024. Since Cuban appeared on the podcast, Alphabet has raised its 2026 capex forecast to roughly $200 billion and Amazon has increased its own spending plans to approximately $220 billion, two data points that only deepen the tension he was describing. The comments were reported by Business Insider’s Theron Mohamed on July 22, 2026.
A Different Kind of Bubble, in Cuban’s View
Cuban is careful to separate overbuild risk from outright mania. He argues the AI boom is not the traditional dot-com bubble, because far fewer companies are going public at “crazy valuations” with “no revenue, no traffic, no nothing,” and none of the retail-frenzy signals that defined 2000 (cab drivers pitching internet stocks, for instance) are visible today.
Where the pain would show up, in his framing, is narrower and more institutional. Cuban argued the damage would be concentrated, warning it “could just destroy a lot of VCs and a lot of funds and a lot of PE” that have gone all-in on AI infrastructure bets, while sparing “most people across the US.” The distinction matters: this is a warning aimed squarely at sophisticated capital allocators, not at retail investors holding index funds.
Power constraints are already adding a wrinkle to that picture. In mid-2026, TD Cowen reported that Microsoft had cancelled or paused data center lease agreements totaling several hundred megawatts, concentrated in international markets, and Wells Fargo separately reported that Amazon had paused some overseas data center leasing conversations. Those moves do not prove Cuban’s thesis on efficiency, but they do suggest that at least some planned capacity is already stalling, for reasons of grid access rather than demand.
He Is Not Alone
Other prominent skeptics have arrived at similar conclusions by different routes. Michael Burry has warned that Big Tech is overinvesting in chips and data centers that could quickly become obsolete. GMO co-founder Jeremy Grantham called AI “obviously a bubble” on the Merryn Talks Money podcast in January 2026, arguing the probability it “will not bust are slim to none” because it “meets every condition of the railroads and the Internet.” He expanded on that view in a January 2026 GMO paper co-authored with financial historian Edward Chancellor, titled “Valuing AI: Extreme Bubble, New Golden Era, or Both?” where his answer was mostly the first. All three see AI as genuinely transformative. Their shared argument is that the capex math assumes a demand curve history has rarely delivered.
What the Market Is Saying Right Now
The current market is running hard in the other direction. Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) disclosed over $60 billion in new orders and a record backlog in a preliminary fiscal Q4 2026 business update filed with the SEC on July 21, 2026. The company guided gross margin to 15% to 17%, well above its prior guidance of 8.2% to 8.4%, and the stock jumped 24% on the news. When Supermicro reported full Q4 results on August 11, gross margin came in at 17.5%, topping even that preliminary range, and the company guided full fiscal year 2027 revenue to between $65 billion and $72 billion, far above the analyst consensus of $54.4 billion. Bank of America is telling clients that wafer fab equipment spending will surge from $144 billion in 2026 to $250 billion by 2028. OpenAI plans to dramatically increase compute spending through 2030, and Microsoft recently signed a multi-billion-dollar agreement to rent computing capacity from Mistral’s European data centers.
That is exactly the “planning for perfection” Cuban is warning about. Whether it ends in more revenue or more pickleball courts is the question every AI-infrastructure investor should be stress-testing right now.
Editor’s note: This pass added post-publication context on Alphabet raising its 2026 capex forecast to roughly $200 billion and Amazon increasing its spending plans to approximately $220 billion, TD Cowen’s mid-2026 report of Microsoft cancelling or pausing several hundred megawatts of international data center leases, the Wells Fargo report of Amazon pausing some overseas leasing conversations, and the detail that Supermicro’s actual Q4 gross margin of 17.5% exceeded even the preliminary 15% to 17% range the company had guided in July. The Broadcast.com transaction was also clarified as an all-stock deal announced April 1, 1999.
Contact [email protected] for any questions or corrections.
I've spent more than 15 years inside enterprise software, working alongside the finance, sales operations, and HR leaders who run the revenue engines at some of the largest tech companies in the country.
My day job is helping enterprise executives make smarter decisions about retention, compensation, and growth. These are the same operational levers that show up in every earnings report investors actually read. That perspective shapes my writing for 24/7 Wall St.
The headline numbers are easy. The interesting stuff is underneath: how companies make money, what executives are worried about, and what any of it means for the person checking their 401(k) on a Sunday afternoon. I write about personal finance and business as someone who has spent her career inside the rooms where these decisions get made.