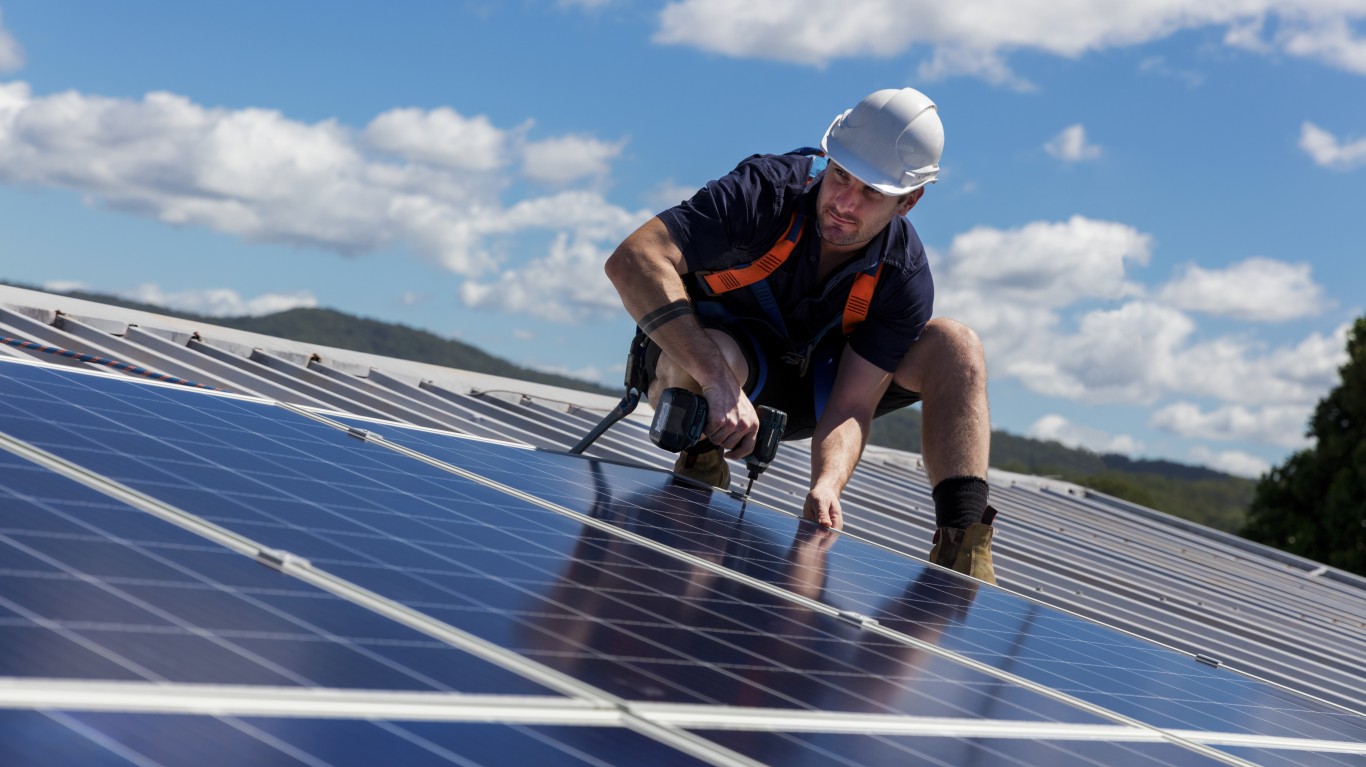
Enphase Energy reports Q2 earnings after today’s close with guidance calling for $280 million to $310 million in revenue, including approximately $85 million of safe-harbor sales.
The anticipated tariff drag narrows to roughly three percentage points from 4.3 points in Q1, providing a modest tailwind. More important will be signs that Propel prepaid-lease originations are stabilizing U.S. demand, European “green shoots” are strengthening, and the new IQ SST product can establish Enphase in AI data-center power.
Enphase is attempting to evolve beyond subsidy-dependent residential solar into a broader energy-electronics platform spanning batteries, EV charging, and data centers and currently trades at a share price of $36.35. A clean beat with stronger Propel disclosure could support Citigroup’s $43 price target, while a weak Q3 outlook would strengthen GLJ Research’s bear case and $24.47 target.