This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Live coverage has ended. The full story is below.
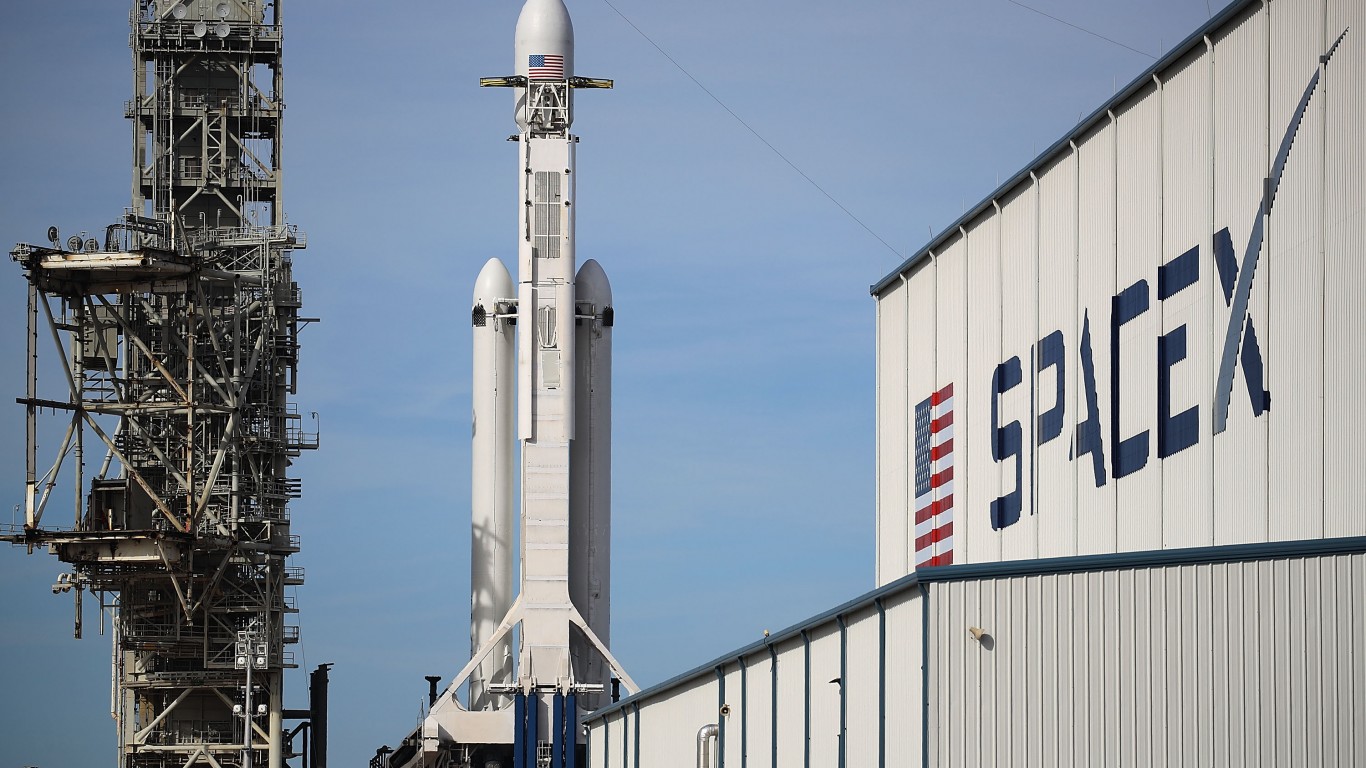
SpaceX (NASDAQ: SPCX | SPCX Price Prediction) reports Q2 2026 results tonight after the market closes. Shares trade at around $120, far off the post-IPO peak near $225. This first quarterly report as a public company frames the trillion-dollar space and AI-infrastructure narrative.
The Backdrop: Momentum Meets Post-IPO Reset
Shares have dropped 26.1% in a month, from $162 on July 2 to $120 by August 4. Reddit sentiment sits at 36 (bearish), driven by lock-up concerns and AI capital-allocation scrutiny. Wall Street stays constructive with 7 buys, 3 holds, and 1 sell, and a $236.71 target implying nearly 100% upside.
Two hyperscaler deals reset the story. Anthropic agreed May 6 to rent about 300 megawatts of Colossus compute at $1.25 billion per month. Google followed June 5 with 110,000 GPUs at $920 million per month through mid-2029. The combined run rate from these deals is roughly $26 billion annually.
Consensus Estimates
| Metric |
FY 2026 |
FY 2027 |
FY 2028 |
| Revenue |
Loss year |
~$62B (~+100% YoY) |
N/A |
| EPS (Normalized) |
Net loss |
~$0.70 |
Over $3.00 |
Consensus estimates that SpaceX will lose money this year, with its first profitable quarter starting in Q3 2026. SpaceX’s S-1 showed $18 billion in revenue, up 33%, but Wall Street models $62 billion for hyperscaler contracts next year.
What I’m Watching: Hyperscaler Rents Meet Space Economics
I’ll be watching four items closely.
First, revenue mix. Both hyperscaler deals include 90-day termination clauses, so management framing of recognized revenue versus contracted run rate matters more than the headline dollar figure.
Second, the margin path. With profitability slated to start in Q3, Q2 gross margin commentary and capex guidance shape whether the FY 2027 EPS bar of roughly $0.70 holds.
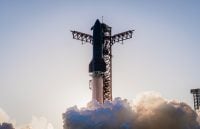
Third, competitive positioning. Japan’s reusable rocket landing rattled retail conviction, with one r/wallstreetbets thread hitting 1,309 upvotes and 512 comments. Any commentary on launch cadence, Starship progress, and moat durability moves the narrative.
Fourth, capital allocation. Analysts will watch how management balances AI infrastructure spend against core space reinvestment. The Reddit thread “SpaceX’s first results put Musk’s AI spending under Wall Street microscope” captured the tension currently defining the stock.
Earnings History
Tonight’s Q2 2026 release is SpaceX’s first reported quarter since the IPO, so there is no 1-day, 7-day, or 14-day post-earnings track record to reference.
Contact [email protected] for any questions or corrections.