Analyst: If SpaceX Delivers Even a Quarter of Elon Musk’s Promised Compute, Nvidia Could Hit $1 Trillion in Revenue
SpaceX's first-ever earnings call gave Nvidia bulls a number so large that one top analyst ran the math and came back with a scenario that rewrites the entire revenue ceiling for the AI chip giant.

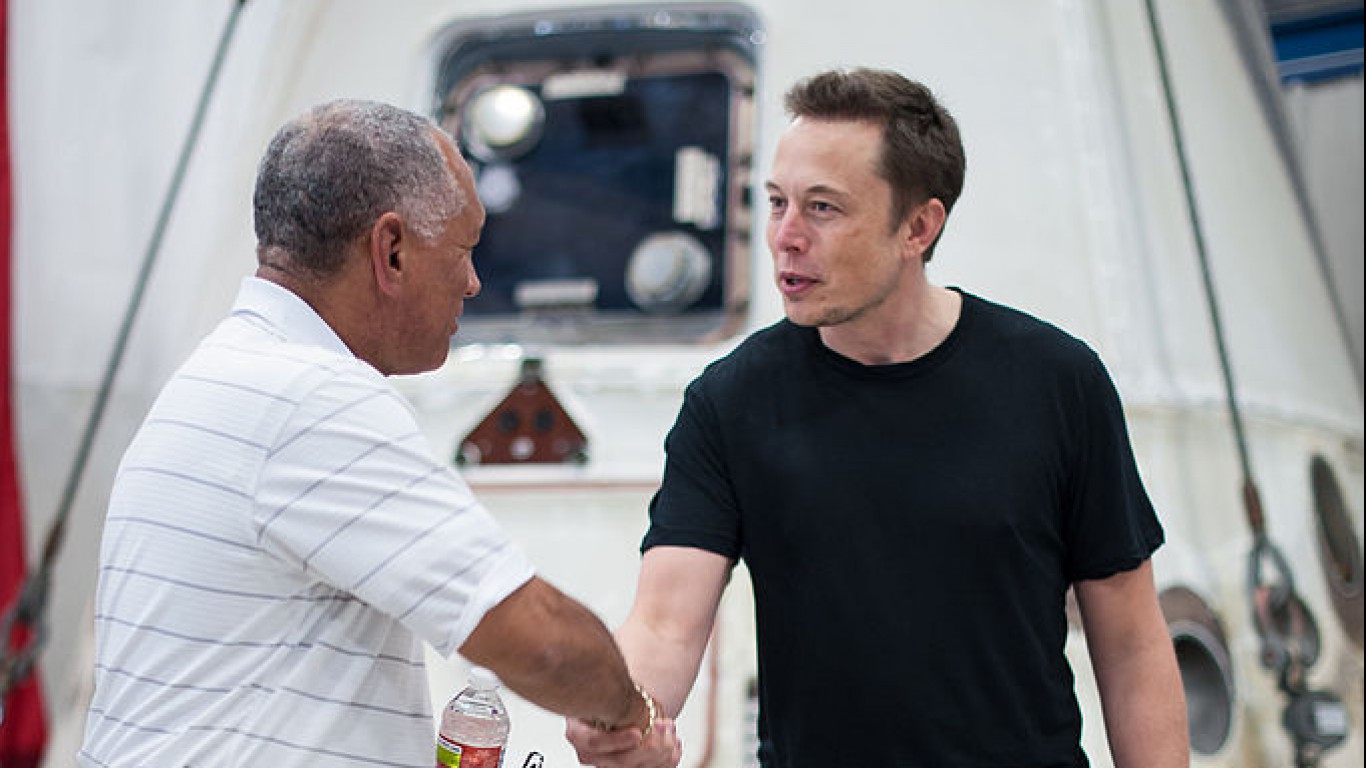
Elon Musk used SpaceX‘s (NASDAQ:SPCX | SPCX Price Prediction) first-ever public earnings call on August 4, 2026 to commit that the company will build its AI computing platform exclusively on NVIDIA‘s (NASDAQ:NVDA) Vera Rubin architecture, and floated a tentative target of 20 gigawatts of power and cooling capacity online by the end of 2027. Melius Research analyst Ben Reitzes ran the math on what even a slice of that means for Nvidia, and the answer is enormous.
What Musk Actually Said
Musk told analysts, “Our understanding with Nvidia is that we will receive a very significant percentage of their GPUs next year.” He framed the buildout in characteristic terms, comparing SpaceX’s entry into large-scale data centers to “the New York Yankees going in and playing a Little League team,” and calling data-center construction a “trivial problem” next to rocket science. SpaceX ended Q2 with 1.4 gigawatts of nameplate compute and expects to exceed 2 gigawatts by year-end 2026. When pressed, Musk gave a 20 GW tentative target by end of 2027, adding that even with delays the company would likely land “close to 15 gigawatts.”
SpaceX’s Numbers Back the Ambition
The credibility of that pledge rests on SpaceX’s Q2 earnings report, which came in well above expectations. Revenue surged 92% to $7.8 billion, beating Wall Street estimates by nearly $1 billion. AI-specific revenue reached $2.6 billion, up 213% sequentially, and management disclosed $14.1 billion in contracted cloud services agreements, including deals with Anthropic and Google. The catch is capex. Companywide spending hit $18.4 billion in Q2 (up from $10 billion in Q1), with AI infrastructure alone near $16 billion, and executives said capex will hold near those levels for the next two quarters. Shares reflected that pressure into the release, with SPCX down 22.64% over the past month before bouncing 9.43% on the day of the report.
The Melius Math
Reitzes laid out two scenarios. In the conservative case, “if SpaceX executes even 2-3 GWs of its stated deployment roadmap in CY27, it could represent an incremental $100B or so of revenue for Nvidia… which equates to ~$2 in upside to our EPS of $13.36.” That 2-3 GW slice is roughly a tenth to a fifth of Musk’s own tentative target, which is why the headline framing of “even a quarter” is a conservative read. The more speculative scenario is bigger: “At $1T in revenue, Nvidia would earn ~$24 at today’s margins.” Reitzes closed with, “We love the endorsement. Reiterate Buy.” Context matters here. Nvidia’s Q1 FY2027 revenue was $81.615 billion, up 85.23% year over year, and management guided Q2 to $91.0 billion plus or minus 2%. Data Center revenue alone reached $75.246 billion, up 92% year over year, running at roughly 92% of the company’s total.
How This Connects to Huang’s Own $1 Trillion Claim
Jensen Huang has separately told investors at GTC that he expects “at least” $1 trillion in cumulative revenue from Blackwell and Vera Rubin chip sales through 2027. That is a different claim from Reitzes’s SpaceX-driven math, but the two dovetail. Melius’s read is that if SpaceX’s plan proves credible, it’s the kind of demand signal that could push Jensen Huang to formally guide toward $1 trillion in revenue “well before 2030.” Huang himself has described AI infrastructure as “the largest infrastructure expansion in human history.”
The Date to Watch
Reitzes says Melius is looking for more detail at Nvidia’s August 26, 2026 earnings report, which is confirmed for after market close. Melius’s current stance on Nvidia stays a Buy with a $400 price target, reaffirmed in May 2026, well above the current stock price of $211.94. This remains one analyst’s conditional scenario built on Musk’s stated roadmap rather than official company guidance from Nvidia. But the arithmetic clarifies why a single customer’s compute pledge is now a first-order variable in Nvidia’s revenue trajectory. Read the full Q1 FY2027 8-K for Nvidia’s own numbers heading into the report.
Contact [email protected] for any questions or corrections.
AJ has spent the past 10 years writing about financial markets at The Motley Fool. His coverage centers on technology stocks and the broader macroeconomic trends, from interest rates to geopolitics, that shape where markets are headed next. AJ is drawn to the stories where big-picture economics and individual companies collide.