Yes, Safe 6% Dividend Yields Do Exist. Here Are 5 You Can Buy Right Now
Most high-yield dividend stocks force a tradeoff between income and safety, but five names across very different sectors are quietly proving that assumption wrong right now.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
With the 10-year Treasury yielding 4.70%, income investors don’t need to reach for junk to beat the risk-free rate. The five names below all offer yields at or near 6%, all have payouts covered by earnings or cash flow, and all have kept the dividend flowing through the past several years. Safety leads; yield follows.
OneMain Holdings
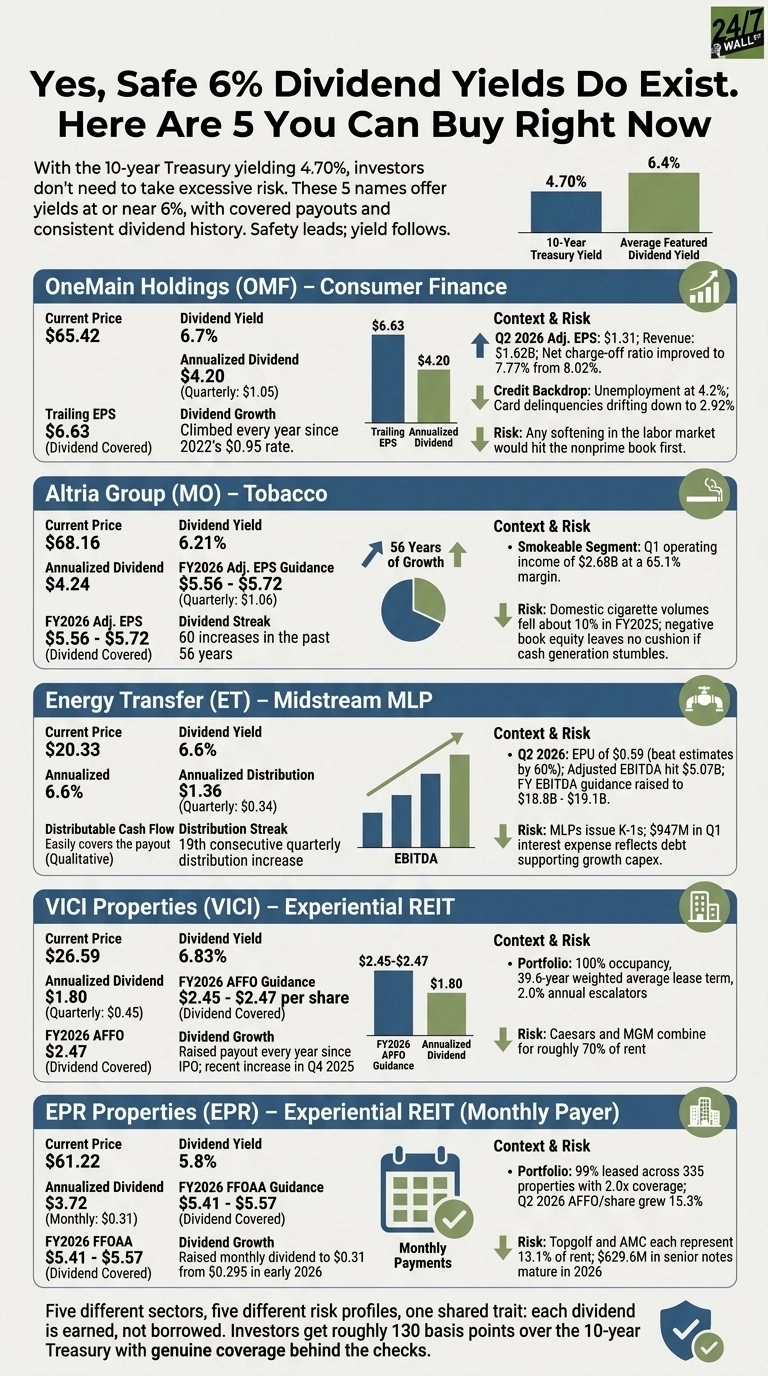
OneMain Holdings (NYSE:OMF | OMF Price Prediction) is a nonprime consumer lender yielding 6.7% at $65.42. The $1.05 quarterly payout ($4.20 annualized) sits well beneath trailing EPS of $6.63, and the dividend has climbed every year since 2022’s $0.95 rate.
Q2 2026 delivered adjusted EPS of $1.31 on $1.62B in revenue, with the net charge-off ratio improving to 7.77% from 8.02%. With unemployment at 4.2% and card delinquencies drifting down to 2.92%, the credit backdrop is cooperative.
Risk: any softening in the labor market would hit the nonprime book first.
Altria Group
Altria Group (NYSE:MO) yields 6.21% at $68.16, backed by one of the longest raise streaks on the market: 60 increases in the past 56 years. The current $1.06 quarterly payout ($4.24 annualized) is covered by reaffirmed FY2026 adjusted EPS guidance of $5.56 to $5.72.
Marlboro’s smokeable segment still throws off enormous cash: $2.68B of Q1 operating income at a 65.1% margin.
Risk: domestic cigarette volumes fell about 10% in FY2025, and negative book equity leaves no cushion if cash generation stumbles.
Energy Transfer
Energy Transfer (NYSE:ET) is a midstream MLP yielding 6.6% at $20.33. The partnership just declared its 19th consecutive quarterly distribution increase, taking it to $0.34 per unit ($1.36 annualized). Q2 2026 was a blowout: EPU of $0.59 beat estimates by 60%, adjusted EBITDA hit $5.07B, and management raised full-year EBITDA guidance to $18.8B to $19.1B. Distributable cash flow easily covers the payout.
Risk: MLPs issue K-1s, and $947M in Q1 interest expense reflects the debt supporting growth capex.
VICI Properties
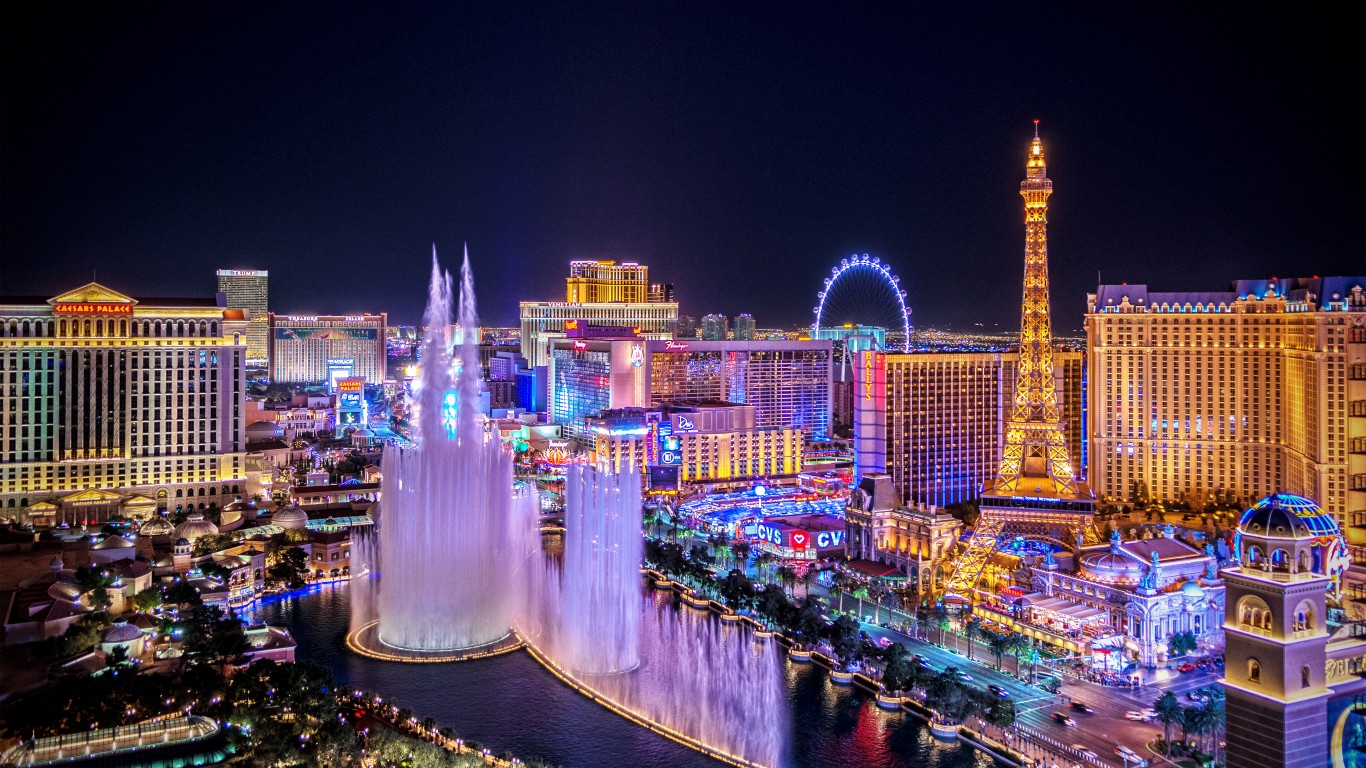
VICI Properties (NYSE:VICI) yields 6.83% at $26.59, the highest in the group. The $0.45 quarterly dividend ($1.80 annualized) is comfortably supported by FY2026 AFFO guidance of $2.45 to $2.47 per share.
The gaming net-lease REIT runs at 100% occupancy with a 39.6-year weighted average lease term and 2% annual escalators. VICI has raised the payout every year since IPO, most recently from $0.4325 to $0.45 in Q4 2025.
Risk: Caesars and MGM combine for roughly 70% of rent.
EPR Properties
EPR Properties (NYSE:EPR) is the monthly payer, yielding 5.8% at $61.22. The experiential REIT raised the monthly dividend to $0.31 from $0.295 in early 2026, taking the annualized rate to $3.72. That’s well inside raised FY2026 FFOAA guidance of $5.41 to $5.57. The portfolio is 99% leased across 335 properties with 2.0x coverage, and Q2 2026 AFFO/share grew 15.3%.
Risk: Topgolf and AMC each represent 13.1% of rent, and $629.6M in senior notes mature in 2026.
The bottom line
Five different sectors, five different risk profiles, one shared trait: each dividend is earned, not borrowed. Investors get roughly 130 basis points over the 10-year Treasury with genuine coverage behind the checks. For income portfolios starved of yield without the risk of a cut, this is the shelf worth shopping.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.