Eli Lilly Stock Has Become a Trillion-Dollar Giant. Is It Too Late to Buy?
Eli Lilly just crossed the trillion-dollar threshold on the back of a GLP-1 empire growing at nearly 50% annually, but a recent pullback and rising risks are forcing investors to decide whether this pharmaceutical giant still has meaningful upside left.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Eli Lilly has joined the trillion-dollar club, and the question every long-only investor is asking is whether the run has more room. My take: yes, but the easy money is behind us.
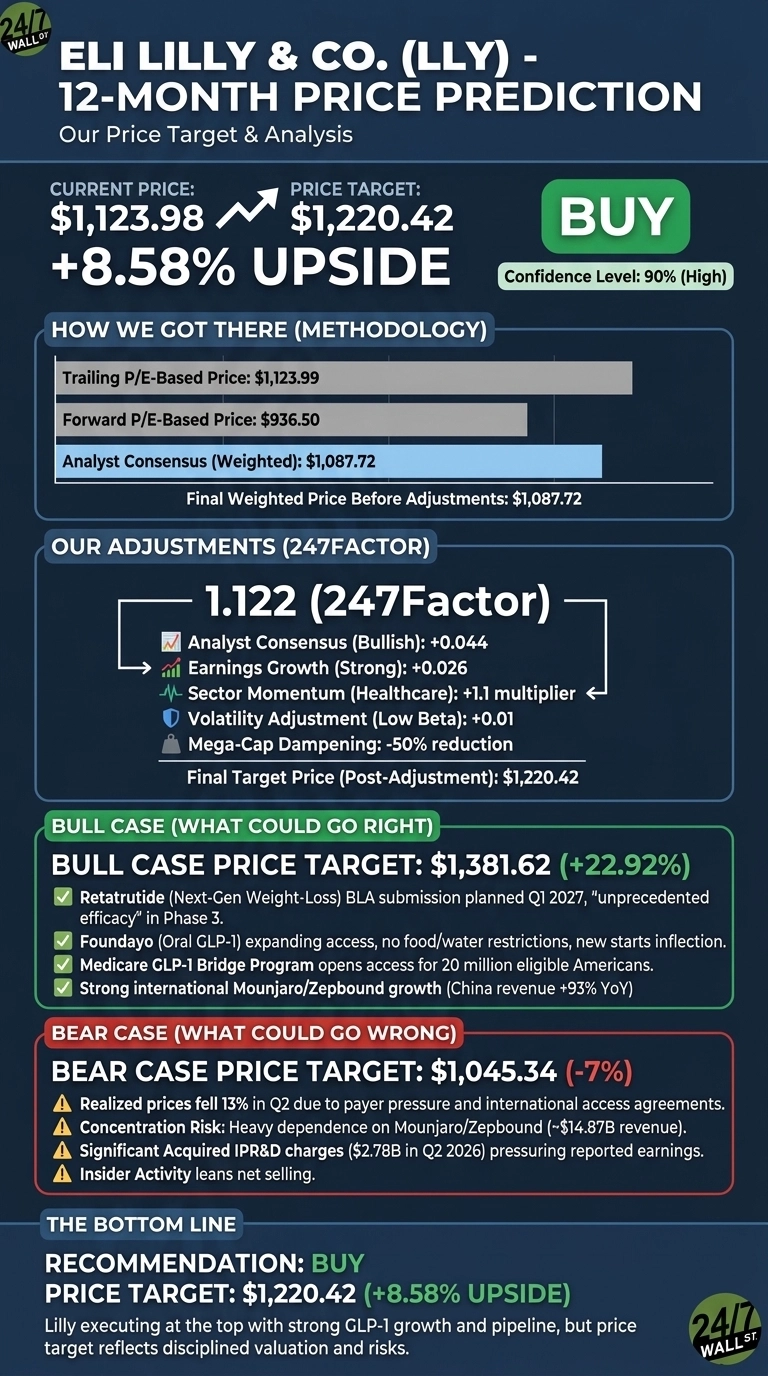
Eli Lilly (NYSE:LLY | LLY Price Prediction) trades at $1,123.98 with a market cap of $1.002 trillion. Our 24/7 Wall St. price target for Lilly is $1,220.42 over the next 12 months, implying 8.58% upside. The recommendation is buy with high confidence at 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,123.98 |
| 24/7 Wall St. Price Target | $1,220.42 |
| Upside | 8.58% |
| Recommendation | BUY |
| Confidence Level | 90% |

How Lilly Got to a Trillion, and Where Shares Sit Now
Shares are up 50.72% over the past year but down 8.61% over the past month as investors digest a scorching run. LLY sits below its 52-week high of $1,292.65 and well above the low of $707.59.
The engine remains Mounjaro and Zepbound: Q2 2026 revenue reached $22.974 billion, up 47.67% year over year, with EPS of $8.38 beating consensus by 27.27%. Mounjaro alone posted $9.94 billion (+91% YoY), and management raised full-year revenue guidance to $85 billion to $87 billion.

Bull Case for $1,381 and Higher
The bull path takes LLY to $1,381.62, a 22.92% gain. The catalysts are real. Retatrutide, Lilly’s triple-agonist, delivered what management called “unprecedented efficacy” across three Phase 3 trials, with a BLA submission planned for Q1 2027.
Foundayo, the first oral GLP-1 with no food or water restrictions, expanded to 36,000 prescribers, and the Medicare GLP-1 Bridge Program opened access for 20 million eligible Americans at $50 per month. International incretin market share of 55% and China revenue growth of 93% in constant currency show the runway is global.

What Could Go Wrong
The bear scenario takes shares to $1,045.34, a 7% decline. Realized prices fell 13% in Q2, and concentration risk is real, with the incretin franchise generating roughly $14.87 billion of the quarter’s revenue.
Acquired IPR&D charges of $2.78 billion pressured reported earnings, and insider activity leans net selling. To be fair, bulls would note the IPR&D charges reflect aggressive pipeline building (Orna, Kelonia, Ajax, Centessa) that expands the long-term shot count, and pricing declines have been more than offset by 60% volume growth.

How Lilly Compares to Novo Nordisk and Merck
Novo Nordisk (NYSE:NVO) is the only true GLP-1 peer, and the valuation gap is stark. NVO trades at a forward P/E of 14 with quarterly revenue growth of just 2.1%, versus Lilly’s 47.7%. That gap validates Lilly’s premium multiple.
Merck (NYSE:MRK) offers a diversified big-pharma contrast. Merck’s forward P/E of 16 looks cheap on paper, but quarterly earnings shrank 19.3% year over year on Keytruda patent-cliff concerns.
| Company | Forward P/E | Quarterly Revenue Growth |
|---|---|---|
| Eli Lilly | 24 | 47.7% |
| Novo Nordisk | 14 | 2.1% |
| Merck | 16 | 5.1% |
The peer set makes our 24/7 Wall St. price target look reasonable: Lilly deserves a premium, but not an unlimited one.
Eli Lilly Price Prediction 2026-2030
The 24/7 Wall St. price target of $1,220.42 and buy rating at 90% confidence reflect a company still executing at the top of its industry.
The tipping factor is guidance: four straight EPS beats and a raised outlook are hard to fade. I’d be a buyer here if retatrutide’s BLA stays on track for Q1 2027. I’d stay on the sidelines if realized-price declines accelerate past 13% in coming quarters.
Looking further ahead, here is where our model projects LLY could trade, assuming continued execution.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $1,154 |
| 2027 | $1,224 |
| 2028 | $1,308 |
| 2029 | $1,399 |
| 2030 | $1,474 |
These projections assume Lilly continues executing on its GLP-1 leadership and pipeline. Significant upside could come from a clean retatrutide launch, while downside risk centers on payer pricing pressure and eventual GLP-1 competition.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.