Joby Aviation Is Near Its 52-Week Low With 91% Upside. The Catch Is Real
Joby Aviation sits a few cents above its 52-week low while the business quietly beats revenue estimates and a White House-backed pilot program reshapes the demand picture. The catch hiding inside that 91% upside could determine whether early buyers are…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our 24/7 Wall St. price target for Joby Aviation (NYSE:JOBY | JOBY Price Prediction) is $11.38 over the next 12 months. The current price is $5.96.

| Metric | Value |
|---|---|
| Current Price | $5.96 |
| Price Target from 24/7 Wall St. | $11.38 |
| Upside/Downside | 91.02% |
| Recommendation | BUY |
| Confidence Level | 50% |
Joby earns a buy rating from our model with moderate confidence. The key risk is cash, as Joby spends hundreds of millions every half year while waiting FAA type certification. The upside depends on reaching milestones before needing another capital raise.
Joby Shares Have Lost More Than Half Their Value in 2026
Joby fell 5.87% over the past week and 11.36% over the past month. It is down 55.08% year to date. The stock sits just above its 52-week low of $5.93 and far below its high of $19.98.
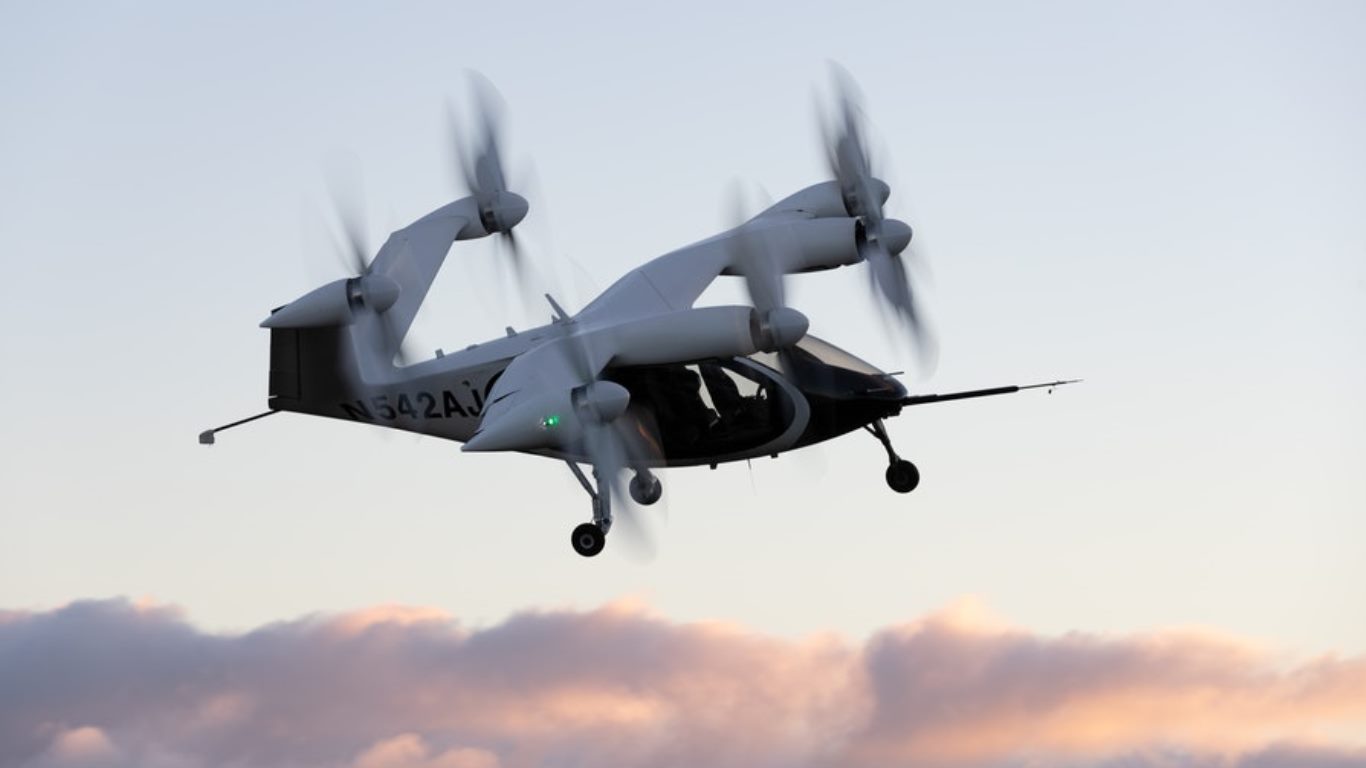
The business is outpacing the stock, with Q2 revenue of $38.64M beat the $30.38M estimate. Blade drove the beat, with seats flown up 50%+. GAAP EPS of -$0.25 missed expectations of -$0.2345. Full-year revenue guidance was raised to $115M-$125M, and the company aims to carry first passengers in 2026.

Why Bulls See $14.56 Within Reach
The bull scenario reaches $14.56 within a year. The main driver is eIPP, the White House-backed eVTOL pilot program. The CFO said it allows Joby “monetize every single aircraft that comes off our production for the foreseeable future.” Certification is progressing:
- Stage 3 plans are 83% complete on Joby’s side.
- The first FAA-conforming aircraft is flying.
- 12 more aircraft are in production.
Toyota (NYSE:TM) plans a $250 million direct investment, expected to close later this year or early next. A planned launch in Dubai brings an international catalyst. Joby carries one Strong Buy and two Buy ratings.

Cash Burn and Dilution Could Cap Gains
The bear case of $8.52 still sits above today’s price. Joby used $365 million in H1 and guided to $385 to $415 million for H2. Share count rose from 894.6 million at end-2025 to 969.9 million by June. Stage 4 testing is 20% complete on Joby’s side and 10% on the FAA’s.
Joby ended Q2 with $2.3 billion in cash and short-term investments. Non-cash revaluations distort GAAP losses, including a $106M gain in Q1. Much spending goes to the Ohio plant and production increase.
Joby Commands a Premium to Archer but Trails Textron
Archer Aviation (NYSE:ACHR) is Joby’s main eVTOL rival under eIPP. Archer posted $5 million in Q2 revenue and $1.56 billion in liquidity. Joby’s larger revenue and cash buffer support its premium valuation.
Textron (NYSE:TXT) shows what a profitable aircraft manufacturer is worth. Textron guides to adjusted EPS of $6.40 to $6.60 for 2026. Joby’s valuation already prices in years of future scale.
| Company | Market Cap | Q2 2026 Revenue |
|---|---|---|
| Joby | $5.94B | $38.64M |
| Archer | $3.73B | $5M |
| Textron | $13.27B | $3.827B |
Milestones Make the 91% Upside Credible
My 24/7 Wall St. price target is $11.38, with a buy rating at 50% confidence. Joby has enough cash to reach its next milestones. Watch for eIPP flights in Texas advancing to carrying passengers and Toyota’s investment closing on time.
Risks to monitor include a Stage 4 stall or another dilutive raise before certification. At this price, the model’s bear case of $8.52 still sits above the current share price.
These are the year-end values from our base-case model.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $6.63 |
| 2027 | $12.80 |
| 2028 | $18.21 |
| 2029 | $24.38 |
| 2030 | $32.47 |
These projections assume Joby continues executing its current strategy. Delays in certification or more dilution could drove results well below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.