Fifty-Five Analysts Cover Meta and None Say Sell
Wall Street's analyst community has reached a verdict on Meta that almost never happens with a mega-cap stock, and the numbers behind that consensus point to a price target that may surprise even longtime bulls.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Wall Street’s coverage of Meta (NASDAQ: META | META Price Prediction) has rarely looked this one-sided. Across the analyst community, 55 Buy ratings sit next to 7 Hold calls and zero Sell ratings. That unanimity is doing real work in our valuation model, and it lands the 24/7 Wall St. price target well above where shares trade today.
Meta closed Friday near $660.71, and our 24/7 Wall St. price target for the stock is $805.90, implying 24.36% upside over the next 12 months. My recommendation is a buy with a 90% confidence rating.
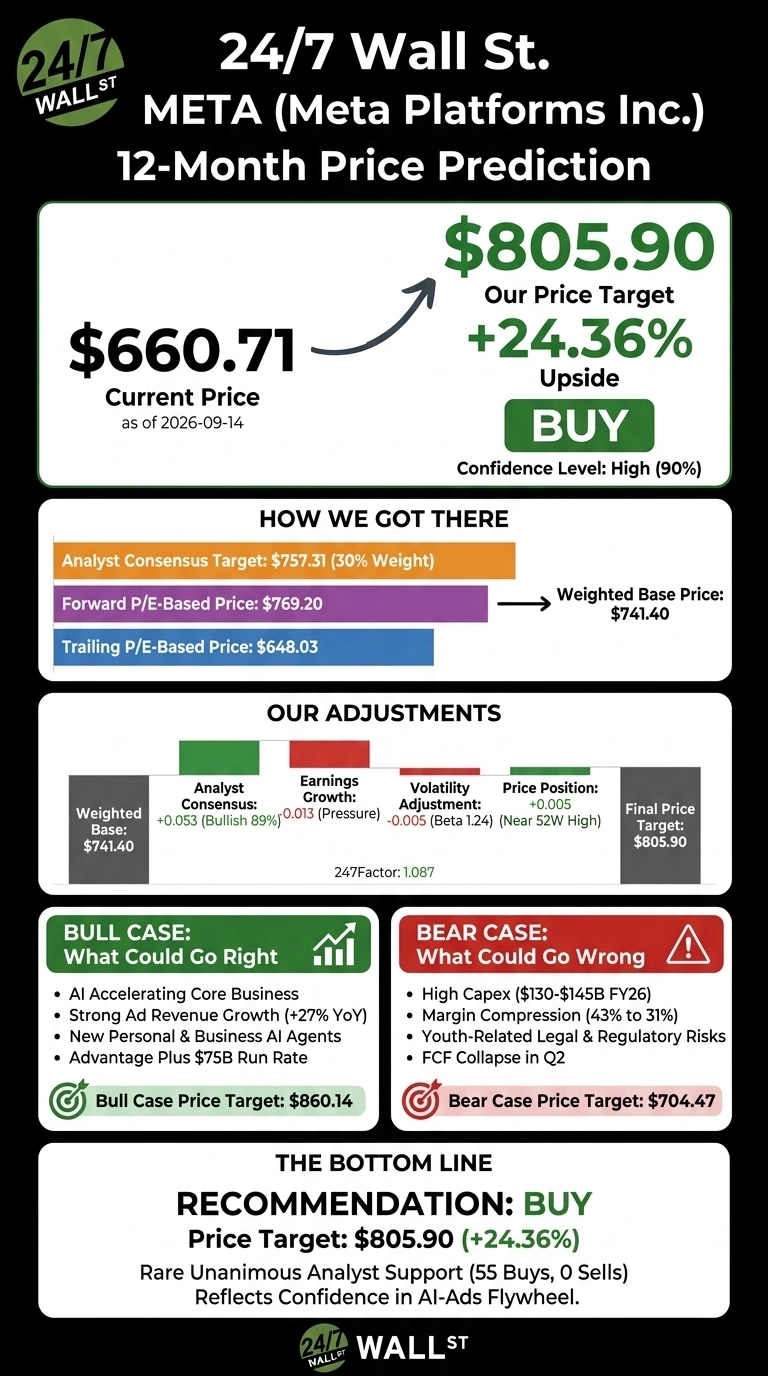
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $660.71 |
| 24/7 Wall St. Price Target | $805.90 |
| Upside | 24.36% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Rebound Off the August Lows
Meta has quietly staged a comeback. Shares are up 7.12% over the past week and 14.14% over the past month, though the stock is still down 11.73% year-over-year and hugging breakeven at +0.27% YTD. The 52-week range runs from $519.78 to $788.22.
The Q2 2026 report on July 29 was the pivot point. Revenue reached $60.80 billion, up 27.96%, but diluted EPS of 6.18 came in 14.42% below consensus, ending a six-quarter beat streak.
The miss reflected $2.40 billion in legal charges and $1.18 billion in severance tied to a roughly 8,000-person headcount reduction. More recently, MarketWatch reported that Meta’s rollout of its Muse personal AI agent reignited investor enthusiasm around monetization.

Bull Case Points to $860 and Higher
Bulls have real ammunition. On the Q2 call, CEO Mark Zuckerberg said “our ads business is reporting faster year over year revenue growth than any other company’s reported ad business.” Ad impressions grew 14% and price per ad grew 12%.
Advantage Plus is at a $75 billion annual revenue run rate, and business agents on WhatsApp already serve 1 million businesses weekly. Our model’s bull scenario puts META at $860.14 in 12 months.

What Could Go Wrong
The bear case starts with capex. FY2026 capital spending is guided to $130 to $145 billion, and Q2 free cash flow collapsed to $784 million, down 91.31%. Operating margin compressed from 43% to 31%.
Youth-related U.S. litigation with trials scheduled for 2026 could also produce material losses. Bulls would counter that excluding legal and severance charges, Q2 operating income would have grown 9% year over year. Our model’s bear case still lands at $704.47, above today’s price.
How Meta Compares to Alphabet and Pinterest
Alphabet (NASDAQ: GOOGL) is the natural digital-ad comparison. Alphabet trades at a P/E of 15, materially cheaper than Meta’s trailing P/E of 24, and Google Cloud grew 82% in Q2 2026. Meta’s advertising still grew faster (27%) than Alphabet’s overall business (24.23%), which supports the premium multiple.
Pinterest (NYSE: PINS) is the smaller social-ad comp. Pinterest posted Q2 revenue of $1.18 billion, up 18.2%, with 640 million monthly active users. Meta’s 3.60 billion daily active people and full-quarter revenue five times PINS’s annual base show why Meta commands a valuation gap. Against this peer set, our $805.90 target looks reasonable.
| Company | Forward P/E | Q2 Revenue Growth |
|---|---|---|
| Meta | 19 | 27.96% |
| Alphabet | 15 | 24.23% |
| n/a | 18.17% |
Meta Price Prediction 2026-2030
My 24/7 Wall St. price target is $805.90 with a buy recommendation and 90% confidence. The tipping factor is the analyst consensus: 55 Buys against zero Sells is rare in mega-cap tech, and it reflects genuine confidence in the AI-plus-ads flywheel.
I’d be a buyer here if capex discipline holds and Q3 revenue lands in the guided $61 to $64 billion range. I’d stay on the sidelines if operating margin drops below 30% again next quarter.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $805.90 |
| 2027 | $897 |
| 2028 | $998 |
| 2029 | $1,110 |
| 2030 | $1,235 |
These projections assume Meta continues executing on its AI monetization roadmap and holds ad pricing power. Significant upside or downside could come from enterprise agent adoption or an adverse youth-litigation verdict.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.