Oracle Has a Massive Opportunity Hiding in Plain Sight
Oracle just posted record AI bookings and cloud growth that should have sent shares soaring, yet the stock sits near a 52-week low. Something is broken in how the market is pricing this company, and the gap between its earnings…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Oracle (NYSE:ORCL | ORCL Price Prediction) just delivered a fiscal Q1 that should have sent shares to new highs. Instead, the stock is trading like the AI trade is unraveling.
Cloud infrastructure revenue grew 121% year over year, remaining performance obligations sit at $664 billion, and management booked more than $30 billion of new AI contracts in a single quarter.
Yet shares are down 25.66% year to date. The question I want to answer: can Oracle really reach $350 per share in 2027?

Why Oracle Shares Are Stuck Despite Record Bookings
The issue is the cash burn, not the underlying business. Oracle guided full-year fiscal 2027 capital expenditures of $90 billion to $95 billion and reported negative $5 billion of free cash flow in Q1 alone. That has spooked investors who bought this name when it was cash-generative software rather than a capex-heavy AI landlord.
The stock action reflects it. Shares are off 9.62% over the past week and 6.38% over the past month, with a brutal 52.86% drawdown over the past year.
A MarketWatch headline captured it directly: “Oracle shook off fears about AI spending, but its stock still loses ground.” With a beta of 1.732, this name amplifies every wobble in AI sentiment. That is the straightforward read.
Wall Street Sees 68% Upside. My Model Says Bigger
The Street is loud on this one. 8 strong buys, 28 buys, 7 holds, and 1 sell with an average price target of $241.41. Our internal base case sits at $221, implying 47.06% upside, with a bull case at $333.39 and a bear case at $185.62. Confidence: 0.9, or high.

Here is my pushback. With 82% of analysts bullish and quarterly earnings growth of 54.5% year over year, the consensus target may still be too anchored to the pre-AI Oracle. Half of the $664 billion RPO is expected to convert to revenue over the next 36 months. Analysts are catching up to the story.
Path to $350 Per Share
Now the math. Reaching $350 from today’s price of $143.50 would require a gain of 143.9%.
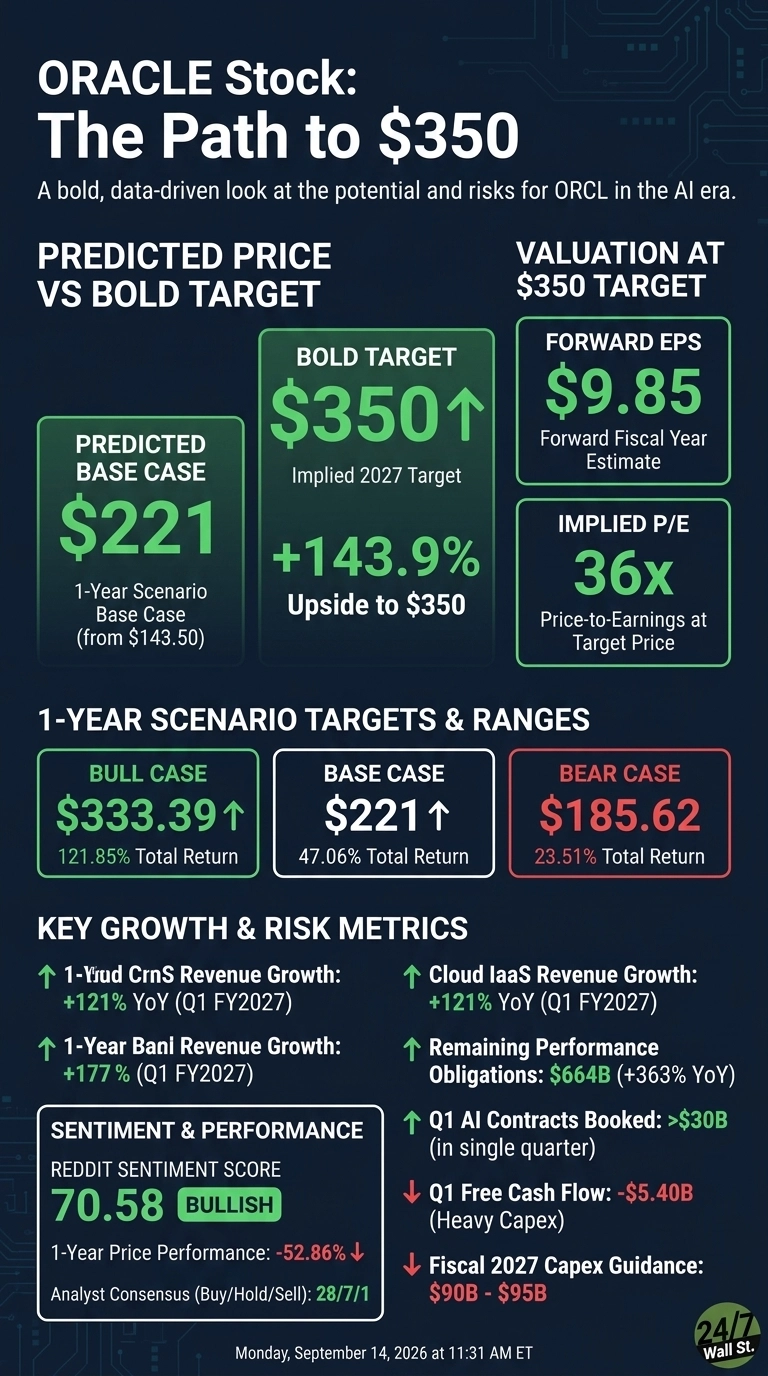
With forward EPS of $9.85, a price of $350 implies a forward P/E of 36x. Our base case of $221 already implies 19x, meaning $350 requires 17x of additional multiple expansion.
That is aggressive, but here is the case for it. GPU utilization is running at 97.9%, and renewals are pricing 20% above prior contracts. Multi-cloud database revenue grew 353% year over year.
On the call, management said, “The world’s a big place. There’s a lot of demand for this capacity.” If Oracle prints EPS closer to the FY2028 consensus of $10.97, the required multiple compresses fast.
The primary risk: a single missed data-center delivery, whether Wisconsin, New Mexico, or Shackleford, could stall the RPO conversion story. Oracle is now as much an AI infrastructure landlord as a software vendor, and the picks-and-shovels names behind that buildout are worth knowing (we profiled seven of them, from power to cooling, in a free report you can grab here).
Where Oracle Trades Today vs Its Earnings Power
At $143.50 against forward EPS of $9.85, Oracle trades near 15x forward earnings. That is a discount to the S&P 500 and cheaper than most hyperscaler peers, despite 30% total revenue growth.
Shares sit closer to the 52-week low of $114.50 than the high of $325.79. Long-term holders have been rewarded, with a 314.55% 10-year return. The valuation gap between growth and price is the entire bull thesis.

Is $350 Realistic? My Verdict
Reaching $350 requires a 143.9% gain and a re-rating to 36x forward earnings. That is a stretch. For it to happen, Oracle needs to convert RPO on schedule, keep OCI utilization above 95%, and show a credible glide path back to positive free cash flow. Sustained EPS beats through fiscal 2028 would do most of the heavy lifting.
What kills it: any capex overrun that forces an equity raise larger than the $20 billion ATM already completed. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Oracle could reach $350 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.