Prediction: Oracle Could Have 50% Upside From Here
Oracle just posted 121% cloud growth and a $664 billion backlog, yet the stock sits near a yearly low. Something in the market's math does not add up, and the answer determines whether this is a generational buy or a…

Oracle (NYSE:ORCL | ORCL Price Prediction | ORCL Price Prediction) has become the most controversial AI infrastructure name on the board. Cloud infrastructure grew 121% year over year last quarter, remaining performance obligations hit $664 billion, and management just booked more than $30 billion in additional AI contracts in a single quarter.
Yet the stock is down 22.89% year to date. That is the tension. My question is simple. Can Oracle recover to $225, roughly 50% above where shares trade today?

Why Oracle Shares Are Stuck Despite Record Bookings
The market accepts the growth story. Its concern is the check. Oracle guided to full-year capital expenditures of 90 to 95 billion for fiscal 2027, produced negative $5.4 billion of free cash flow last quarter, and management has not committed to when free cash flow turns positive. Interest expense already jumped 55% to $1.4 billion.
Shares are off 0.96% on the week and down 49.25% over the past year, from $293.27 to $148.84. A recent Business Insider report on severance for laid-off Oracle workers has added to the noise. With a beta of 1.732, this is a name that swings hard in both directions.
Wall Street Sees 60% Upside. Our Model Says 47%
The consensus is loudly bullish. The average analyst target sits at $237.97, with 8 strong buys, 28 buys, 7 holds, and 1 sell. That works out to 82% bullish among covering analysts.

Our own model lands slightly more conservatively. Base case is $216.99, an upside of 47%, with a bull case of $332.66 and a bear case of $182.81. Confidence is high at 0.9.
I think analysts are actually right to lean aggressive here. Trailing-12-month operating income growth just accelerated from 16% in Q4 to 21% in Q1, and RPO conversion is only starting.
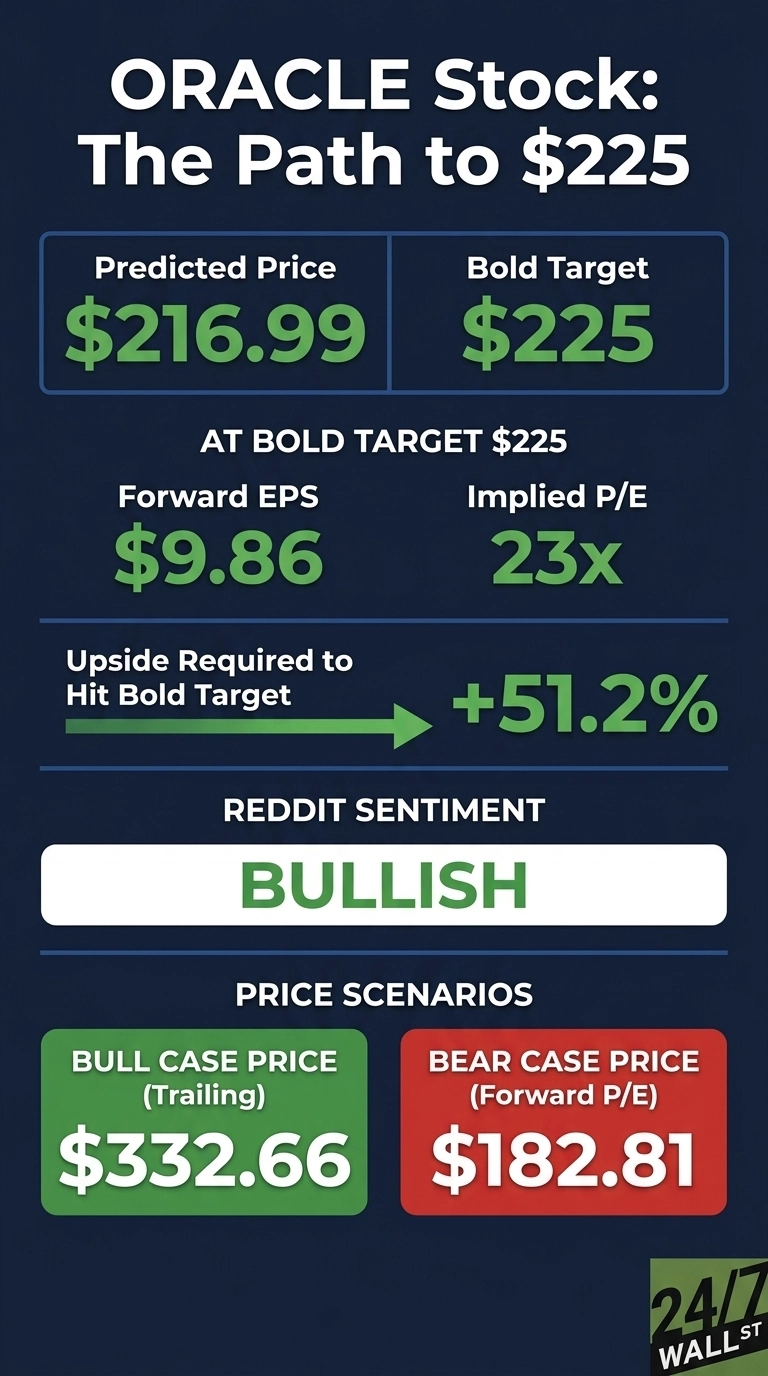
Path to $225 Per Share
Reaching $225 from today’s price of $148.84 would require a gain of 51.2%.
With forward EPS of $9.86, a price of $225 implies a forward P/E of 23x. Our base case of $216.99 already implies 18x, meaning the bold target requires roughly 5x of additional multiple expansion.

That is achievable, but only with proof. The 247Factor adjustment sits at 1.139, powered by technology sector momentum (1.15 multiplier), 82% bullish analyst consensus, and 54.5% year-over-year earnings growth.
Management raised FY2027 non-GAAP EPS guidance to $8.10 and revenue to at least $90 billion. Consensus for FY2028 already sits at $10.99.
On that number, $225 is only 20x. Management stated “GPU utilization remains extremely high at 97.9% in Q1” and renewed GPUs at a 20% premium. The primary risk is that peak-CapEx years pressure the balance sheet before RPO converts.
Where Oracle Trades Today vs Its Earnings Power
At $148.84, Oracle trades at a forward P/E of 15x against fiscal 2027 EPS of $9.86. For a business growing revenue 30% year over year with cloud accelerating, that is cheap.
Shares sit well off the 52-week high of $325.79 and above the 52-week low of $114.50. Over ten years, Oracle has returned 342.19%. The multiple compression is real, but so is the earnings ramp underneath it.
Is $225 Realistic? Here’s My Verdict
Reaching $225 requires a 51.2% gain from here. I think that is realistic on a 12-to-18-month view.
Three things need to go right. RPO has to keep converting on schedule, with management already targeting half within 36 months. GPU utilization needs to stay near 97.9%. And FY2028 EPS consensus of $10.99 has to hold or move higher.
Oracle is one of several picks-and-shovels names riding the data center buildout, and we profiled seven more suppliers, from power to cooling, in a free AI infrastructure report. A datacenter delivery slip or a credit-market shock would derail it. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Oracle could reach $225 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.