Jim Cramer Picks Nokia as AI Supercycle Winner While Dumping on BWX Technologies’ 30x Multiple
Jim Cramer gave two nuclear and AI infrastructure plays completely opposite verdicts on the same night, and the reason comes down to a single number that separates a buy from a pass in a rising rate environment.

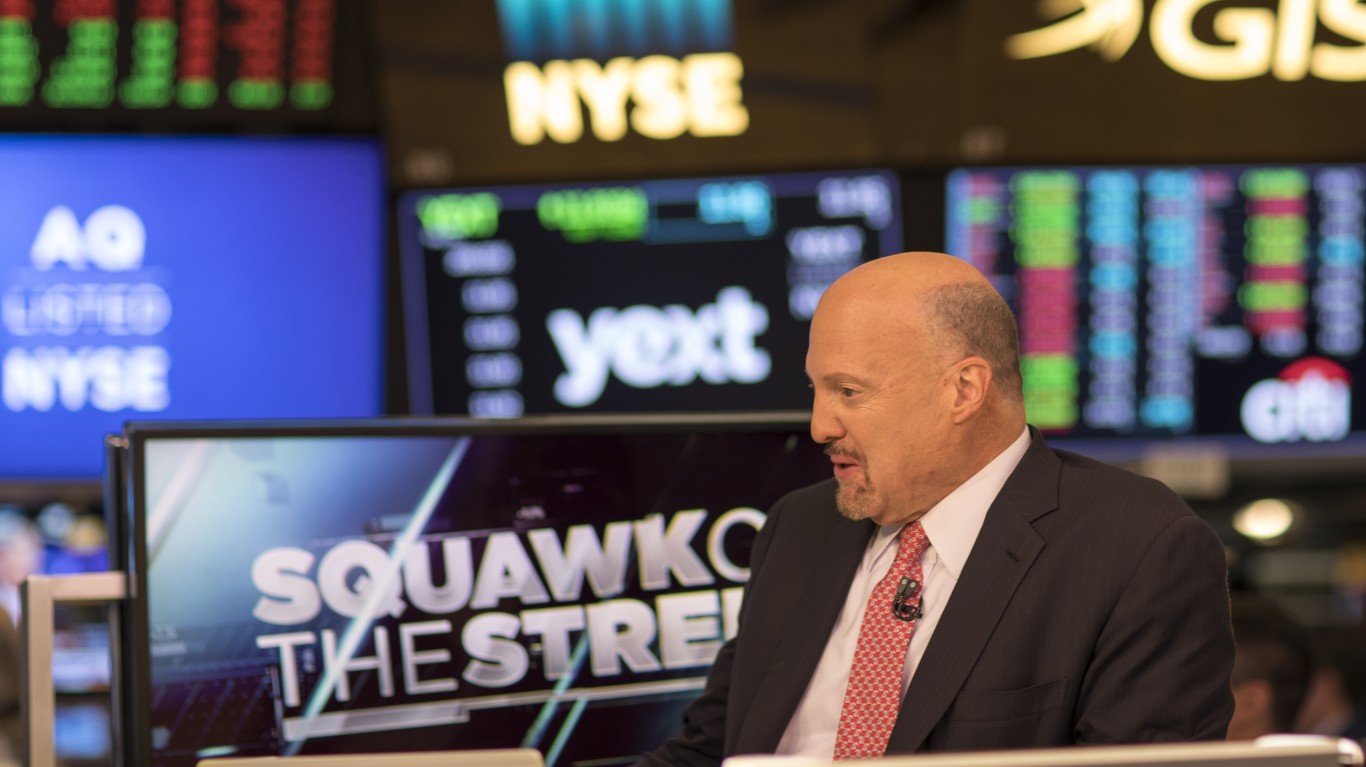
Two quality businesses came up on the September 16 Mad Money lightning round, and only one cleared Jim Cramer’s bar. He told a caller Nokia (NYSE:NOK | NOK Price Prediction) was a buy right here right now, then passed on BWX Technologies (NYSE:BWXT) because the multiple was too rich.
Both names sit on real end markets, one in AI networking and the other in naval propulsion and small modular reactors, so the split reflects what he is willing to pay when the discount rate is moving against long-duration stories.
Nokia has rerated on data center wins and optical demand, up 59.02% year to date through the September 16 close. BWXT has given back a chunk of its nuclear renaissance premium, down 15.37% over the same stretch. That gap frames the segment, and it frames a rule that runs through most of Cramer’s snap verdicts in a tightening cycle.
Why Nokia Cleared the Bar
Nokia is up 124.18% over the past year as the AI supercycle shows up in the order book. Q2 revenue of $5.49 billion beat consensus by 13.79%, and AI & Cloud customer revenue more than doubled year-on-year to roughly $509 million.
Order intake in that same segment reached $3.20 billion for the quarter, with roughly half expected to convert to revenue within twelve months. CEO Justin Hotard said on the call that “the stronger order momentum that began in the second half of 2025 is now translating into revenue growth.”
The strategic moves back that up: the NXP Chandler fab acquisition for indium phosphide production, the San Jose fab ramping to volume by Q4 2026, and preferred networking status with Nscale.
At a forward P/E of 22x against an analyst target of $14.96, the cash is arriving at a multiple that still discounts to peers in optical and IP.

Why BWXT’s Multiple Is the Sticking Point
Cramer’s objection was blunt. “The problem with BWXT, the price to earnings multiple at 30 is too high, according to CNBC. I think it’s a great company. Really terrific. But it’s too expensive. Even though it has nuclear. We have to hold off.”
The business is genuinely strong. Q2 revenue rose 18% to $901.63 million, backlog reached $8.4 billion (up 40% year over year), and trailing twelve-month book-to-bill sits at 1.7 times.
A multiple that was defensible when discount rates were falling becomes hard to defend when they are rising. BWXT still trades at a forward P/E of 29x, and a trailing P/E of 38x, and much of the SMR order flow remains years away from meaningful revenue (we mapped five ways to play the nuclear restart, utilities and fuel suppliers included, in a free report here).


Nuclear exposure is a thesis. The stock’s multiple is a price, and Cramer’s read is that today’s price already discounts the win.
Cramer’s Rule Underneath Every Call
Cramer framed the segment as follows: in a rate-tightening cycle, buyers cannot own companies with persistent losses. That is why his caution on trucking after a soft J.B. Hunt earnings report and his advice to consider a merger and move on sit alongside the BWXT pass.
The through line is a shorter time horizon on anything requiring patience, and a preference for cash flow visible in the current fiscal year.
Lightning round answers are snap judgments delivered without a model. Treat any of them as a starting screen for your own work.
Bull and Bear Case for NOK Stock
The bull case is that Nokia is early in a multi-year AI networking cycle where supply is the binding constraint, with Hotard noting on the call that “if there was more supply, I think we’d probably generate more revenue.” Full-year comparable operating profit is guided to EUR 2.1 billion to EUR 2.6 billion, with management pointing above the midpoint.
The bear case is customer concentration in a handful of AI and cloud names, plus $445 million in accelerated restructuring charges that pushed reported Q2 operating result to a $57.06 million loss, with free cash flow conversion tracking the low end of the 55% to 75% range.
The variable is whether the AI RAN pilots at year-end and the San Jose fab ramp turn the current order book into 2027 revenue, or whether hyperscaler order timing slips and the rerate stalls.

Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.