Nokia Investors Won’t Like This: Jim Cramer Says NOK Stock Is a Buy
Jim Cramer just called Nokia a strong buy, which would be great news except for one uncomfortable fact that long-suffering NOK shareholders know all too well about his track record.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
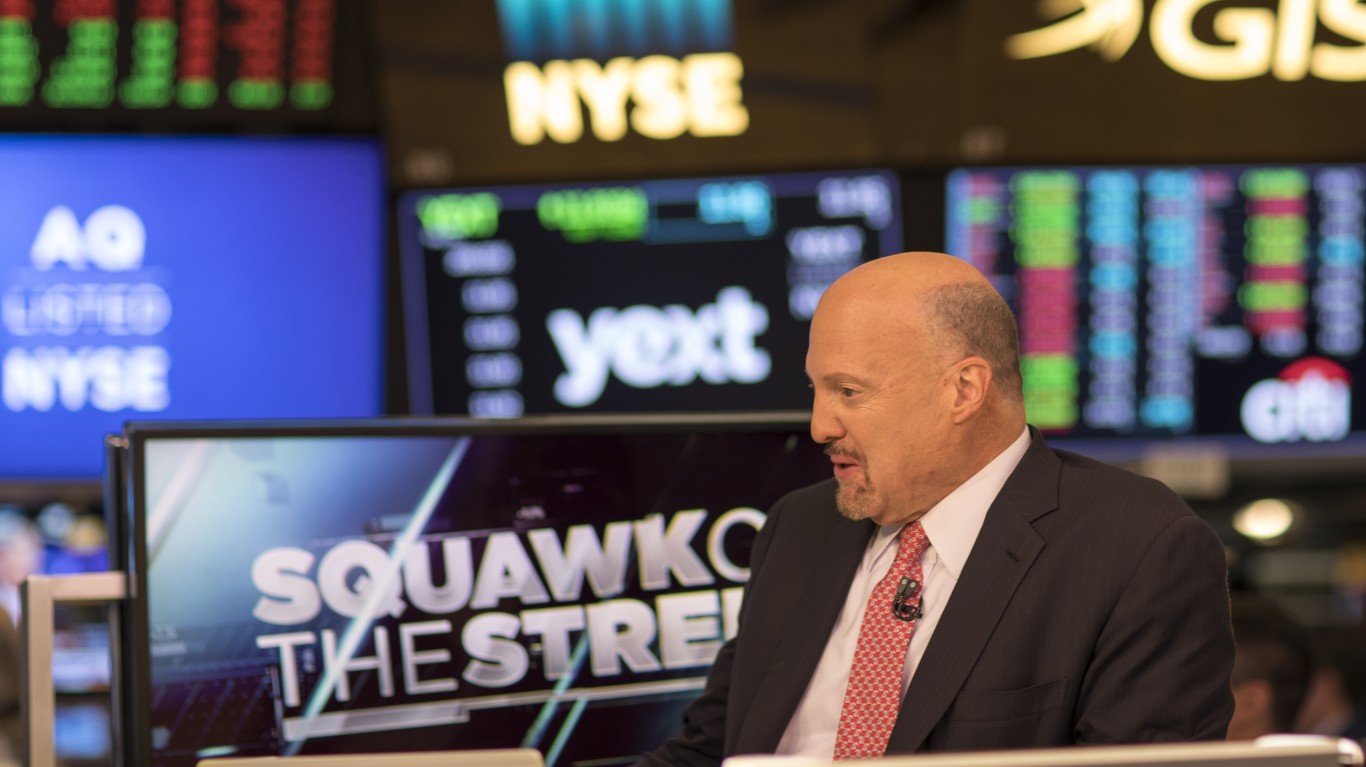
Long-suffering Nokia shareholders finally got the CNBC blessing this week. On the September 16 Lightning Round of Mad Money, Jim Cramer told a caller asking about Nokia (NYSE:NOK | NOK Price Prediction) that “I like Nokia very much… I think it’s a terrific situation and I would be a buyer right here, right now.” The endorsement came a day before Nokia disclosed an expanded partnership with Microsoft (NASDAQ:MSFT) to launch an AI-powered telecom network automation platform integrating Nokia Data Suite with Microsoft Fabric, sending shares up 3.8% intraday Thursday.

Here is why some Nokia holders may cringe at the timing. A cottage industry of “Inverse Cramer” strategies has grown up around the premise that fading his calls beats following them. Quiver Quantitative runs an Inverse Cramer portfolio, and the popular CramerTracker account on X recently circulated three-year performance numbers claiming the inverse strategy returned 171.6% versus 146.6% for a Nancy Pelosi tracker. One viral post joked that “Inverse Cramer being autopilot’s best performing fund will never not be hilarious.”
Rally Already Baked In?
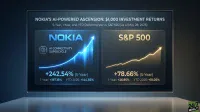
Nokia has moved well beyond its sleepy value-trap reputation. The ADR is up 132.81% over the past 12 months and 65.14% year to date, trading around $10.53 after touching a 52-week high of $17.36. Market capitalization now sits near $58.95 billion. That rally reflects a genuine business inflection under CEO Justin Hotard, who has retooled the Finnish equipment maker around what he calls the AI supercycle.
The Q2 2026 report on July 23 gave the bulls their ammunition. Revenue of $5.49 billion beat estimates by 13.79% and EPS of $0.0799 beat the $0.0682 consensus. Most striking, AI and Cloud customer revenue more than doubled year over year to $508.96 million, with order intake of EUR 2.8 billion in the segment. Optical Networks grew 19% and IP Networks grew 15% on a constant currency basis. Details are in the 6-K filing.
Hotard told analysts on the call, “If there was more supply, I think we’d probably generate more revenue,” underscoring that supply capacity is the binding constraint. Nokia is addressing that by acquiring NXP’s Chandler, Arizona semiconductor fabrication campus for Indium Phosphide production, ramping a new San Jose optical fab in Q4, and boosting Pennsylvania test capacity tenfold.
Valuation and the Numbers Cramer Skipped
Nokia carries a trailing P/E of 70 and a forward P/E of 22, with a PEG of 0.818 and an analyst consensus target of $14.96. Wall Street sentiment is mixed: four strong buys, four buys, two holds, and one strong sell.

The complicating footnotes matter. Reported Q2 operating income was a loss of $57 million after $445.05 million in accelerated restructuring charges. Free cash flow ran negative $835 million, and net income dropped 94.44% year over year. Management expects EUR 800 million in total restructuring charges in 2026 as it integrates its China operations and simplifies its European footprint.
What to Watch Next
The Microsoft news reported by Barron’s and the WSJ Thursday morning extends a strategic pattern that includes the prior Nscale networking partnership and a patent agreement with Amazon. AI-RAN pilots are on track to begin at year-end, with commercial availability in 2027. For Q3, Nokia guided sequential net sales growth of 3% to 7%. Cramer’s viewers should watch order conversion. Management expects about half of AI and Cloud orders to convert to revenue within twelve months. Whether the Inverse Cramer crowd or the CNBC faithful ends up looking smart on NOK will hinge on that conversion metric.

Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.