Amazon’s AI Bet is Already Starting to Pay Off
AWS just posted its fastest growth in 18 quarters while Amazon is burning through capex at a rate that swung free cash flow negative. Here is why that tension keeps me adding shares instead of walking away.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
I keep buying Amazon (NASDAQ:AMZN | AMZN Price Prediction) because every quarter the AI capex story looks less like a bet and more like a receipt. I have added on strength and pullbacks, and I plan to keep adding.
AWS revenue hit $42.23B, growing 37% year over year, the segment’s fastest growth in 18 quarters. The trajectory is compelling: 20% to 24% to 28% to 37% across Q3 2025 through Q2 2026. Growth is accelerating even as the base expands, with an AWS operating margin of 39.4%.
Custom Silicon Is Compounding
Amazon’s chips and AI businesses each eclipsed run rates of more than $25 billion in Q2, both growing at triple-digit percentages year over year. 98% of Amazon’s top 1,000 EC2 customers use Graviton, with revenue commitments increasing nearly three times quarter-over-quarter. Anthropic and OpenAI have made multi-year, multi-gigawatt commitments to Trainium. AWS’s backlog now sits at $496 billion, growing triple digits year over year.
Q2 operating income landed at $27.46B, up 43.2% YoY. Advertising is a $70B+ TTM business growing 26%. Amazon holds $78.21B in cash, debt/equity of 0.37, and interest coverage at 35x, enabling its $200B 2026 capex plan without external funding.
Why I Skip the Index Route
Since Amazon reported Q2 on July 30, 2026, AMZN moved from $230.08 to $251.19. Over the same window, SPDR S&P 500 ETF Trust (NYSEARCA:SPY) went from $747.03 to $762.70, and Invesco QQQ Trust (NASDAQ:QQQ) went from $687.99 to $716.92. I add AMZN on top of the index for direct exposure to AWS’s 39.4% segment margin and fastest growth in 18 quarters.
Capital Intensity Is the Real Risk
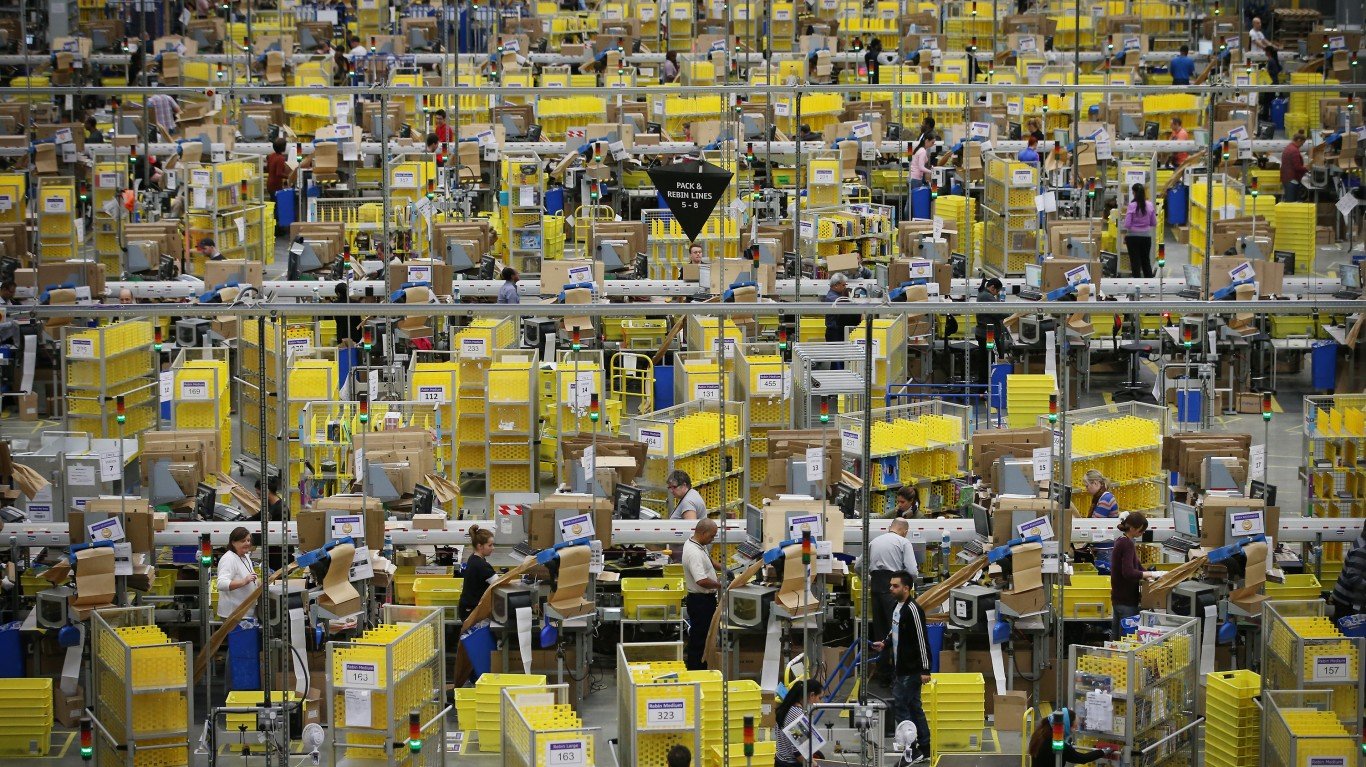
I will not pretend the risk away. Capex reached $54.21B in a single quarter, up 68.4% YoY, and free cash flow swung to negative $7.6 billion TTM. If AI demand rolls over before those data centers monetize, the payback window stretches out and the stock takes it in the teeth. What keeps me buying anyway is management’s own framing of the economics. Data-center capital is spent two years before servers go in. Servers take a little less than three years to break even and then run for at least five to six years. Most AI capacity is contracted for at least five-year terms. A large portion of 2027 capacity is already reserved, and Amazon expects to have double the power capacity by the end of 27 that we had in 25. That buildout has to be powered, cooled, and networked by someone, and we profiled seven of the suppliers riding the same wave in a free AI infrastructure report. The demand is contracted. The math works when the equipment runs.
Why the Buy Button Stays Active
Andy Jassy said AWS “could become a few hundred billion dollar revenue business” and now believes it “will be at least double that and very possibly be a trillion dollar annual revenue business for us in time.” At a $2.71 trillion market cap and P/E of 35, that valuation is reasonable for a company with $496 billion of contracted backlog, a $169 billion AWS run rate, and two separate $25B+ AI and chips businesses.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.