Joby Is Still Early. That’s Exactly Why the Stock Is So Interesting
Joby Aviation has lost more than half its value over the past year, yet our model puts fair value nearly double the current price. The question is whether the certification and commercial flight timeline holds long enough to close that…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
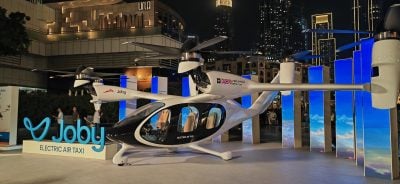
Joby Aviation is one of the most polarizing names in aerospace, and after a rough year for the stock, our proprietary model still sees meaningful upside from here.
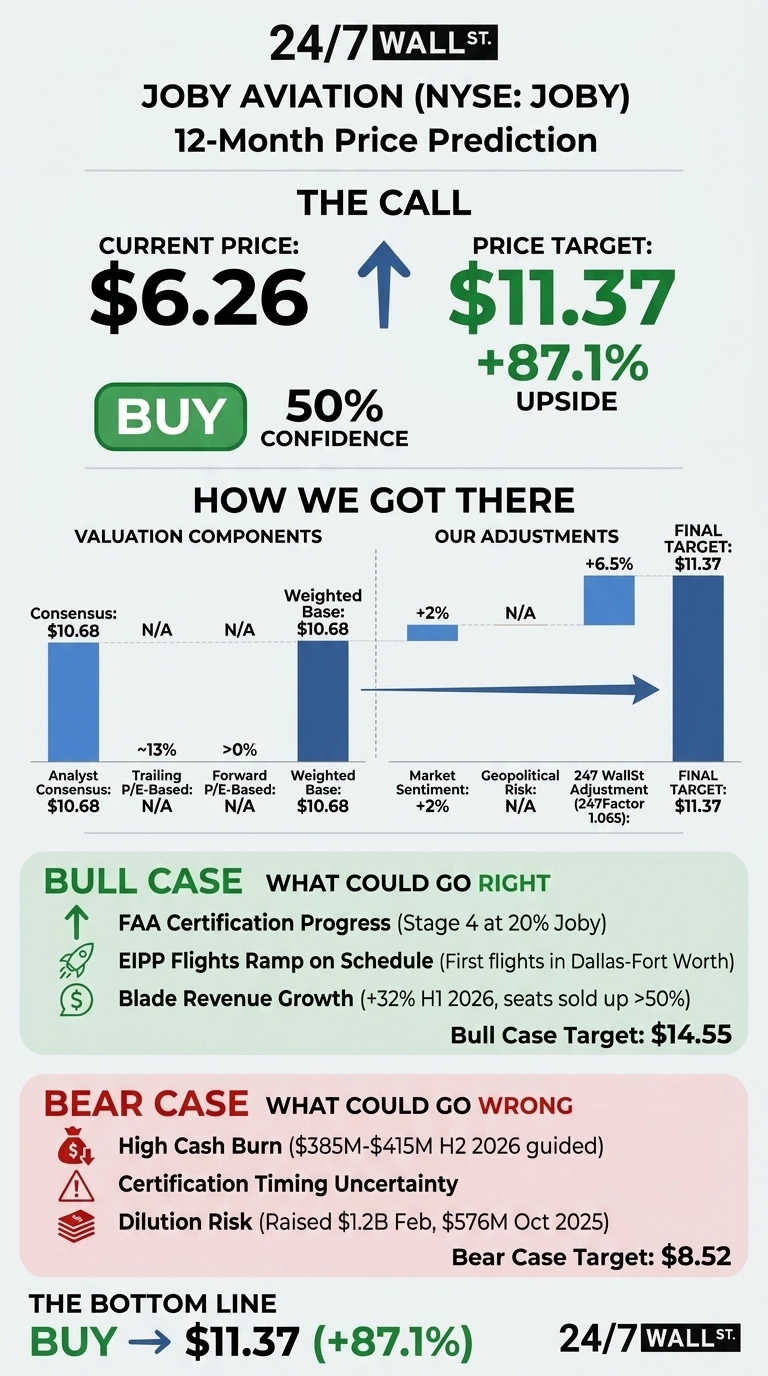
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) trades at $6.26 as of this morning, and our 24/7 Wall St. price target puts fair value materially higher over the next 12 months. The company is still burning cash and still pre-certification on its core eVTOL, but the setup into commercial flight is the most tangible it has ever been.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $6.26 |
| 24/7 Wall St. Price Target | $11.37 |
| Upside | 87.1% |
| Recommendation | BUY |
| Confidence Level | 50% |
Our 24/7 Wall St. price target for Joby is $11.37, implying 87.1% upside. Confidence is medium at 50%, which fits a pre-revenue eVTOL story where the outcome distribution is genuinely wide.
We rate the stock a buy, but this is a risk-on position sized accordingly (we wrote a whole free playbook on speculating with just 5% of a portfolio, here).

Down Sharply, but the Setup Is Improving
JOBY is down 52.57% year-to-date and 56.49% over the past year, trading well below the $19.98 52-week high.
Q2 was actually strong operationally. Revenue came in at $38.64M vs $30.38M consensus, and management raised FY26 revenue guidance to $115M to $125M.
On the earnings call, CEO JoeBen Bevirt said Joby is “now at the point where we’re preparing for commercial service” with first EIPP flights in Dallas-Fort Worth targeted for this month. A recent Forbes piece asked whether JOBY is mispriced ahead of commercial flight, and the model agrees the gap has widened.

Bull Case: $14 and Higher
If FAA certification progresses on the current arc and EIPP flights ramp on schedule, JOBY’s optionality gets repriced quickly. Stage 4 certification has moved from 6% to 20% on the Joby side, and Bevirt says “the core constraint we’re facing on many routes is now aircraft availability rather than passenger demand.”
Blade seats sold were up over 50% year-over-year in Q2. Toyota’s $250 million direct investment, the Virgin Atlantic UK partnership, and the Dubai vertiport network all support upside. Our bull-case one-year projection is $14.55.

What Could Go Wrong
The bear case is straightforward. Joby’s operating margin is -1,346.92%, and H2 2026 cash use is guided to $385M to $415M. Certification timing remains uncertain, and prior capital raises ($1.2B in February, $576M in October 2025) show real dilution risk. Insider activity trends net selling.
Bulls would counter that ugly GAAP numbers include a $108M non-cash warrant/earnout revaluation, and that spending is deliberately “disciplined and milestone-driven.” Our bear-case one-year projection is $8.52, still above where the stock trades today.
How Joby Compares to Archer and Textron
Archer Aviation (NYSE:ACHR) is the cleanest direct comp. Archer carries a $4.02 billion market cap versus Joby’s $6.04B, and posted just $5 million in Q2 revenue against Joby’s $38.64M (thanks to Blade). Joby’s revenue base makes our target look reasonable relative to Archer’s premium.
Textron (NYSE:TXT) is the mature aviation benchmark. Textron guides FY26 adjusted EPS of $6.40 to $6.60 on a $8 billion Aviation backlog. That contrast shows how far Joby must travel, but also how much room exists in the electric segment Textron just dissolved as a standalone unit.
Joby Aviation Price Prediction 2026-2030
The 24/7 Wall St. price target is $11.37, the recommendation is buy, and confidence is 50%. The scale-tipper is that even the model’s bear case sits above today’s price.
The bullish thesis rests on FAA Stage 4 continuing to progress and EIPP flights beginning as planned this month. The bearish thesis takes hold if certification slips into 2027 or the next capital raise arrives before revenue meaningfully scales.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $7.28 |
| 2027 | $12.79 |
| 2028 | $19.70 |
| 2029 | $25.37 |
| 2030 | $30.64 |
These projections assume Joby executes on certification, manufacturing ramp, and EIPP monetization. Meaningful upside or downside could come from FAA timing, hydrogen propulsion progress, or another dilutive raise.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.