Price Prediction: Joby Aviation’s High-Risk, High-Reward Path to 30% Upside
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) has been one of the most volatile names in the eVTOL space. After a punishing first half of 2026, the risk/reward calculus has shifted. The stock is down sharply, certification is inching closer,…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) has been one of the most volatile names in the eVTOL space. After a punishing first half of 2026, the risk/reward calculus has shifted. The stock is down sharply, certification is inching closer, and Dubai operations are reportedly on track.
The 24/7 Wall St. Price Target for Joby Aviation
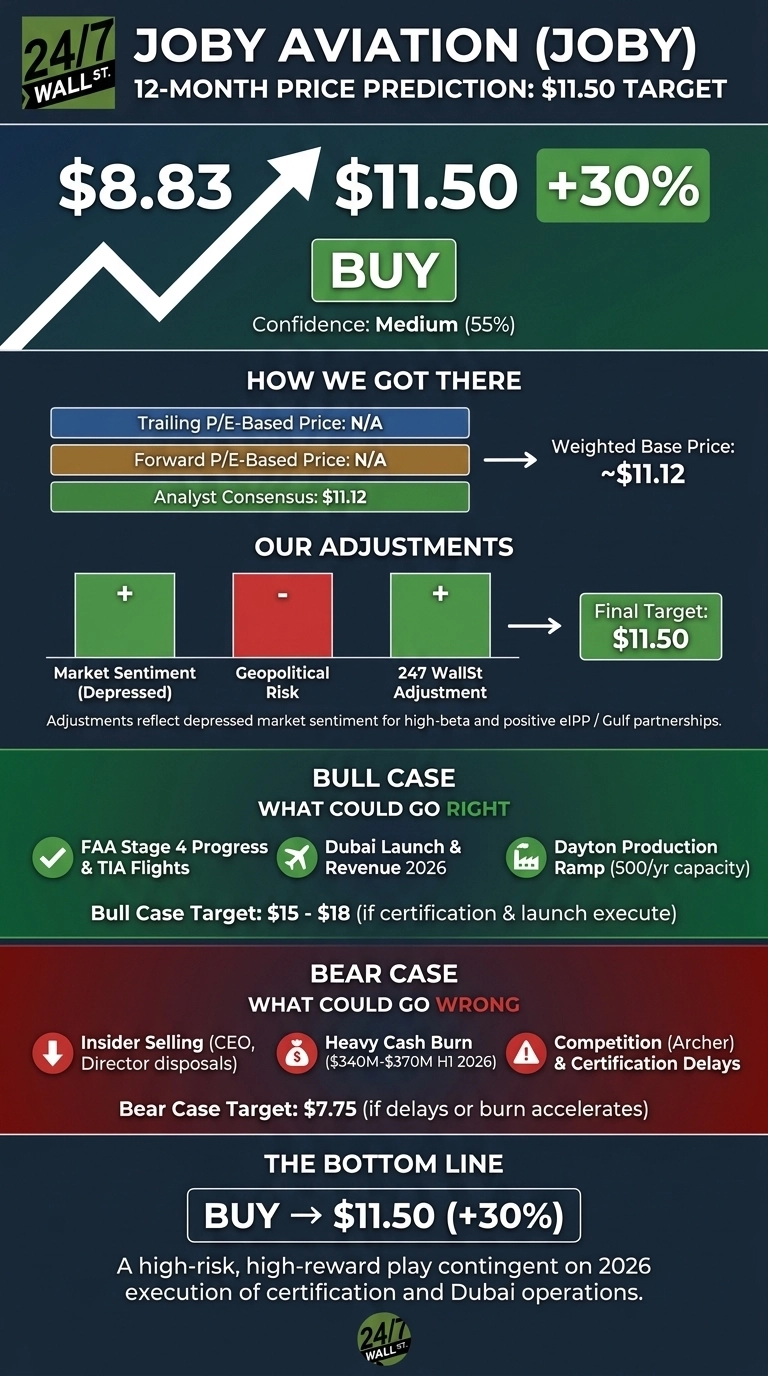
Joby Aviation trades at $8.83, down 33.11% year to date. Our 24/7 Wall St. price target for Joby is $11.50 over the next 12 months, implying roughly 30% upside, modestly above the Wall Street consensus target of $11.12. Recommendation: Hold with constructive bias. Confidence: medium, given the binary nature of FAA certification and cash burn risk.
| Metric | Value |
|---|---|
| Current Price | $8.83 |
| 24/7 Wall St. Price Target | $11.50 |
| Upside | 30% |
| Recommendation | HOLD |
| Confidence Level | 55% |
A Brutal Six Months, but a Real Earnings Beat
Joby has fallen 23.08% over the past month and 11.7% in the past week, pressured partly by Russell rebalance flows. The 52-week range is $7.75 to $20.95, with the 200-day moving average at $12.39.
Q4 2025 results were strong: revenue of $30.84 million exceeded the $16.88 million consensus, and EPS of -$0.14 beat the -$0.20 estimate. A $1.2 billion equity and convertible raise in February pushed cash to $1.41 billion, extending runway materially.
Why Bulls See a Breakout Ahead
The bull case is rich. CEO JoeBen Bevirt called 2026 “a key inflection point”, citing Dubai passenger service this year and the eIPP program. FAA Stage 4 certification advanced 18 points in Q4 alone. Joby logged 9,000+ flight miles in 2025 and has letters of intent worth over $1 billion across Saudi Arabia, Kazakhstan, and Japan.
The 700,000 sq ft Dayton, Ohio facility targets eventual capacity of 500 aircraft per year, supported by Toyota’s $500 million commitment. If FAA Type Certification arrives on time and Dubai launches cleanly, a bull scenario points to $15 to $18, near the 52-week high.
The Risks Worth Watching
The bear case starts with insider activity. CEO Bevirt sold 322,019 shares on June 15 at $10.38, part of a broader pattern of executive disposals. Director Paul Sciarra sold 500,000 shares at roughly $12. Much of this trades through Rule 10b5-1 plans, and Sciarra still holds 56.1 million shares, so framing every sale as conviction loss overstates the case.
H1 2026 cash usage is guided at $340 million to $370 million, gross margin sits at -30.1%, and Archer Aviation is a credible competitor. Bulls counter that the operating loss reflects $161.26 million in Q4 R&D spending ahead of certification. A bear scenario revisits the 52-week low near $7.75.
Hold for Now, but Watch Dubai
My 24/7 Wall St. price target is $11.50 with a hold rating and 55% confidence. I would be a buyer if Joby announces a concrete FAA TIA flight schedule or confirms paying passenger flights in Dubai before year end.
I would stay on the sidelines if cash burn exceeds guidance or certification slips into 2027. The setup is high risk, high reward. The 30% upside requires execution on certification and Dubai.
Assuming certification by 2027, the Dayton ramp toward 4 aircraft per month, and progressive margin expansion as Blade revenue scales:
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $11.50 |
| 2027 | $14.00 |
| 2028 | $17.50 |
| 2029 | $21.00 |
| 2030 | $25.00 |
Significant upside or downside could result from FAA timing, dilution from future raises, or Archer Aviation winning key contracts.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.