The Joby Aviation Bull Case Comes Down to One Question
Joby Aviation has lost more than half its value this year, yet five aircraft are flying, a Toyota factory deal is closing, and FAA certification keeps advancing. Whether JOBY can reach $12 in 2027 depends entirely on a single regulatory…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
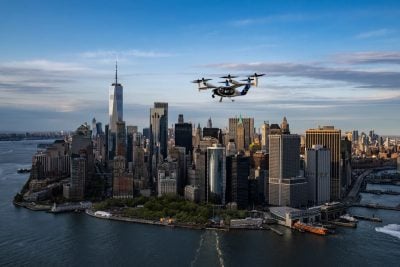
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) has had a punishing 2026. Shares are down 53.56% year-to-date and 56.59% over the past year, after touching the mid-teens in late 2025. Yet the underlying business has quietly matured.
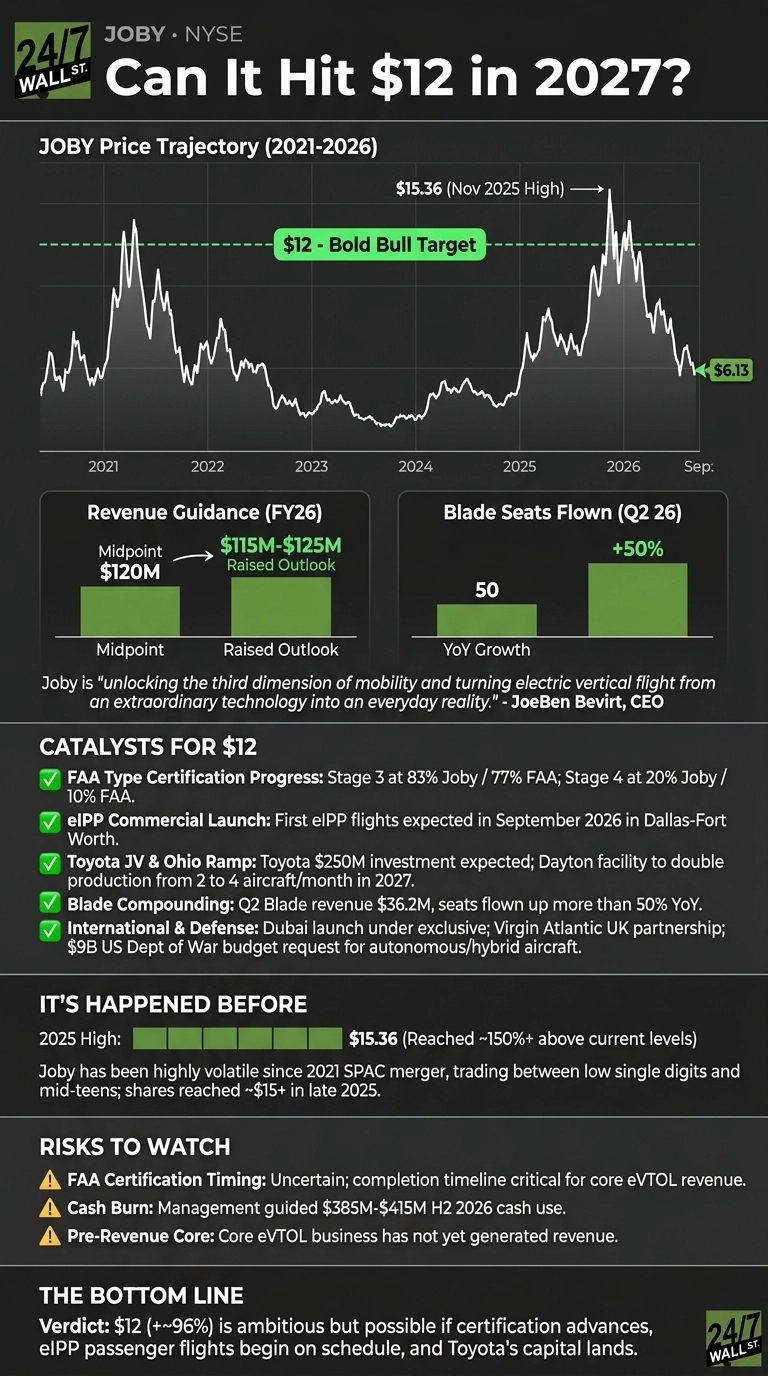
CEO JoeBen Bevirt told investors on the Q2 call that Joby is “unlocking the third dimension of mobility and turning electric vertical flight from an extraordinary technology into an everyday reality.”
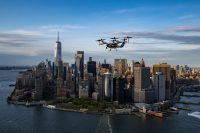
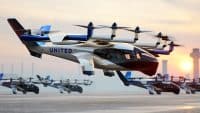
With five air taxis flying, a Toyota manufacturing JV, and FAA certification advancing, the setup for a rebound is here. Let’s look at what it would take for JOBY to hit $12 per share in 2027.
Wall Street Sees Meaningful Upside From Here
The analyst consensus 1-year target sits at $10.68, implying 74.23% upside from the recent close of $6.13. Ratings are split: 3 buys, 5 holds, and 3 sells. The bulls point to Blade’s momentum and certification progress; the skeptics point to cash burn.
Joby also beat revenue estimates in each of the last three quarters, most recently posting $38.6 million against a $30.38 million consensus, and management raised full-year 2026 revenue guidance to between $115 million and $125 million.

Path to $12 Per Share
Since Joby is pre-revenue on its core eVTOL business, price-to-sales is the right lens. On the $120 million guidance midpoint, the current $6.09 billion market cap is roughly 50x forward sales.
At $12, JOBY would trade near 100x. That looks steep, but it becomes defensible the moment the FAA signs off and the aircraft starts generating revenue.

What could push JOBY to $12?
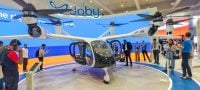
- FAA type certification progress. Stage 3 is at 83% Joby / 77% FAA and Stage 4 at 20% Joby / 10% FAA, with five conforming aircraft flying and 12 more in production.
- eIPP commercial launch. First eIPP flights are set for September in the Dallas-Fort Worth area, with paying passengers targeted in 2026.
- Toyota JV and Ohio ramp. Toyota’s $250 million direct investment is expected to close by early 2027, backing a Dayton facility built to double production from 2 to 4 aircraft per month in 2027.
- Blade is compounding. Q2 Blade revenue reached $36.2 million with seats flown up more than 50% year-over-year.
- International and defense. Dubai launch under a six-year exclusive, a Virgin Atlantic UK partnership, and a $9 billion FY26 U.S. Department of War budget request for autonomous/hybrid aircraft all widen the addressable market.
Joby’s Volatility Says $12 Is in the Range
A move from $6.13 to $12 would roughly double the stock. JOBY has done that repeatedly since its 2021 SPAC merger, with shares reaching $15.36 as recently as November 2025.
The stock still trades 28.72% below its price five years ago, so $12 would simply recover ground already covered during prior eVTOL enthusiasm cycles. A name this volatile belongs in the speculative sleeve of a portfolio, sized with rules (we laid out a full playbook for speculating with just 5% of a portfolio in a free guide: here).

Bottom Line: $12 Hinges on One Question
The bull case for Joby comes down to whether the FAA signs off and commercial operations scale before cash gets tight. Management guided $385 million to $415 million of second-half 2026 cash use against roughly $2.3 billion in liquidity, giving Joby runway to execute.
If certification advances, eIPP passenger flights begin on schedule, and Toyota’s capital lands, $12 in 2027 becomes credible. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how Joby could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.