Joby Stock Has a Futuristic Story. Here’s My Long-Term Price Prediction
Joby Aviation has lost more than half its value in 2026, yet analysts see a path back above $10 and bulls are eyeing $12 by next year. The question is whether a handful of upcoming catalysts can close that gap…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
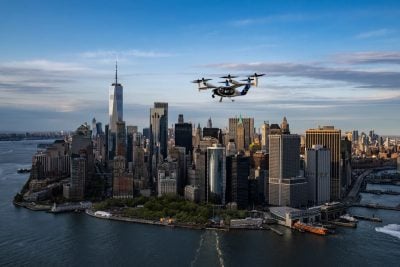
Joby Aviation (NYSE:JOBY | JOBY Price Prediction) has had a brutal 2026. Shares are down 52.73% year-to-date and off 62.68% over the past year, sliding from a 52-week high of $19.98 to roughly $6.24. The pullback reflects impatience with FAA certification timing and heavy cash burn.
CEO JoeBen Bevirt still frames 2026 as the year Joby is “unlocking the third dimension of mobility and turning electric vertical flight from an extraordinary technology into an everyday reality.”
Let’s walk through what it would take for JOBY to reach $12 per share in 2027.

Wall Street Is Split, but the Average Target Sits Well Above Spot
The consensus analyst price target is $10.68, implying meaningful upside from current levels. Coverage is genuinely mixed: 1 Strong Buy, 2 Buys, 5 Holds, 2 Sells and 1 Strong Sell.

What the bears are missing is the revenue trajectory. Trailing revenue reached $116.3 million, up 2,574.93% year over year, and Joby has beaten revenue estimates in 3 of the last 3 quarters, including an 82.66% beat in Q4 2025 and a 27.18% beat in Q2 2026. Management raised full-year 2026 guidance to $115 million.
Path to $12: Here Is the Math
Joby is unprofitable, so traditional P/E is useless. On price-to-sales, the stock trades at 53.54x trailing revenue. At $12, with roughly 993.87 million shares outstanding, market cap would be near $12 billion.
Layer in 2027 revenue scaling toward $250-$300 million as Blade grows and eVTOL commercial flights begin, and the implied multiple compresses meaningfully, even at the higher price. That is the setup bulls need.
What could push JOBY to $12?
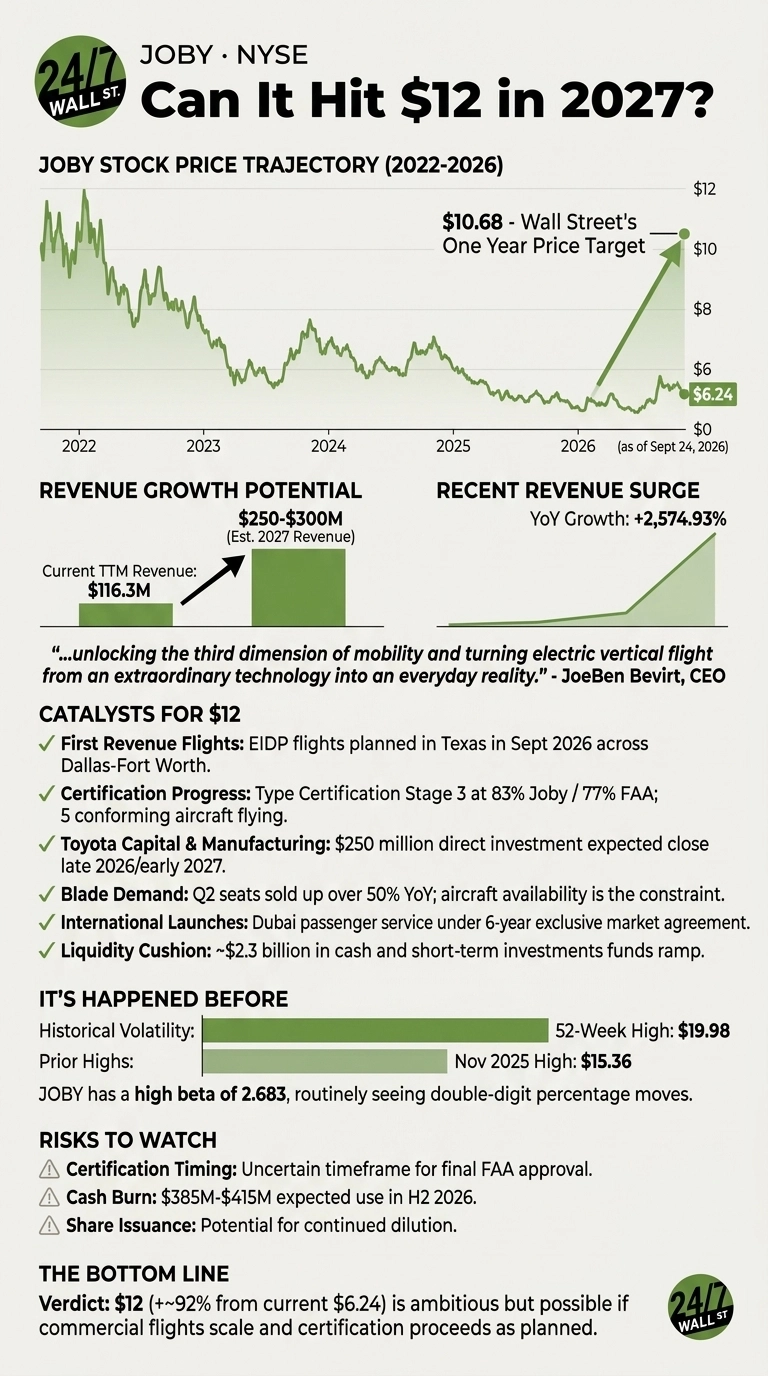
- First revenue flights: Joby plans first EIDP flights in Texas in September 2026 across Dallas-Fort Worth, progressing to paying passengers.
- Certification progress: Type Certification Stage 3 is at 83% Joby / 77% FAA, with five conforming aircraft flying and 12 more in production.
- Toyota capital and manufacturing: A $250 million direct investment is expected to close late 2026 or early 2027, plus a JV for high-volume production.
- Blade demand: Q2 seats sold jumped over 50% year over year, with aircraft availability now the binding constraint.
- International launches: Dubai passenger service under a 6-year exclusive market agreement, plus Virgin Atlantic in the UK.
- Liquidity cushion: Roughly $2.3 billion in cash and short-term investments funds the ramp.

History Shows JOBY Can Move Fast in Either Direction
With a beta of 2.683 and a 52-week range of $5.93 to $19.98, JOBY moves in double-digit percentages routinely. The stock traded near $15.36 as recently as November 2025, so $12 would be a reversion to where the market already valued the story less than a year ago.
A model weighted to the analyst target projects a base case of $11.37 and a bull case of $14.55 by September 2027.
Verdict on $12 by 2027
Hitting $12 would require roughly a double from today. That is ambitious, but Joby already trades well below its own recent range, analysts already peg fair value near $10.68, and 2027 is set up as the year commercial revenue begins scaling behind Toyota’s capital and the EIPP flight program.
The hurdles are real: certification timing, $385M-$415M in H2 2026 cash burn, and continued share issuance. Returns at this level should not be assumed every year, but I have outlined the blueprint for how JOBY could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.