CoreWeave Stock Has a Massive AI Catalyst. We See 94% Upside
CoreWeave has shed nearly half its value from its 52-week high, but a triple-digit backlog and a fresh wave of AI commitments point to a setup that bears may be dangerously underestimating.

CoreWeave (NASDAQ:CRWV) has become the purest public-market bet on AI infrastructure, and after a punishing three-month slide, our model sees the setup skewing sharply to the upside.
Our 24/7 Wall St. price target for CoreWeave is $167.84, implying 94.19% upside from the current $86.44 quote. We rate the shares a buy at moderate confidence, given the volatility that comes with a name burning cash to build out gigawatts of GPU capacity.
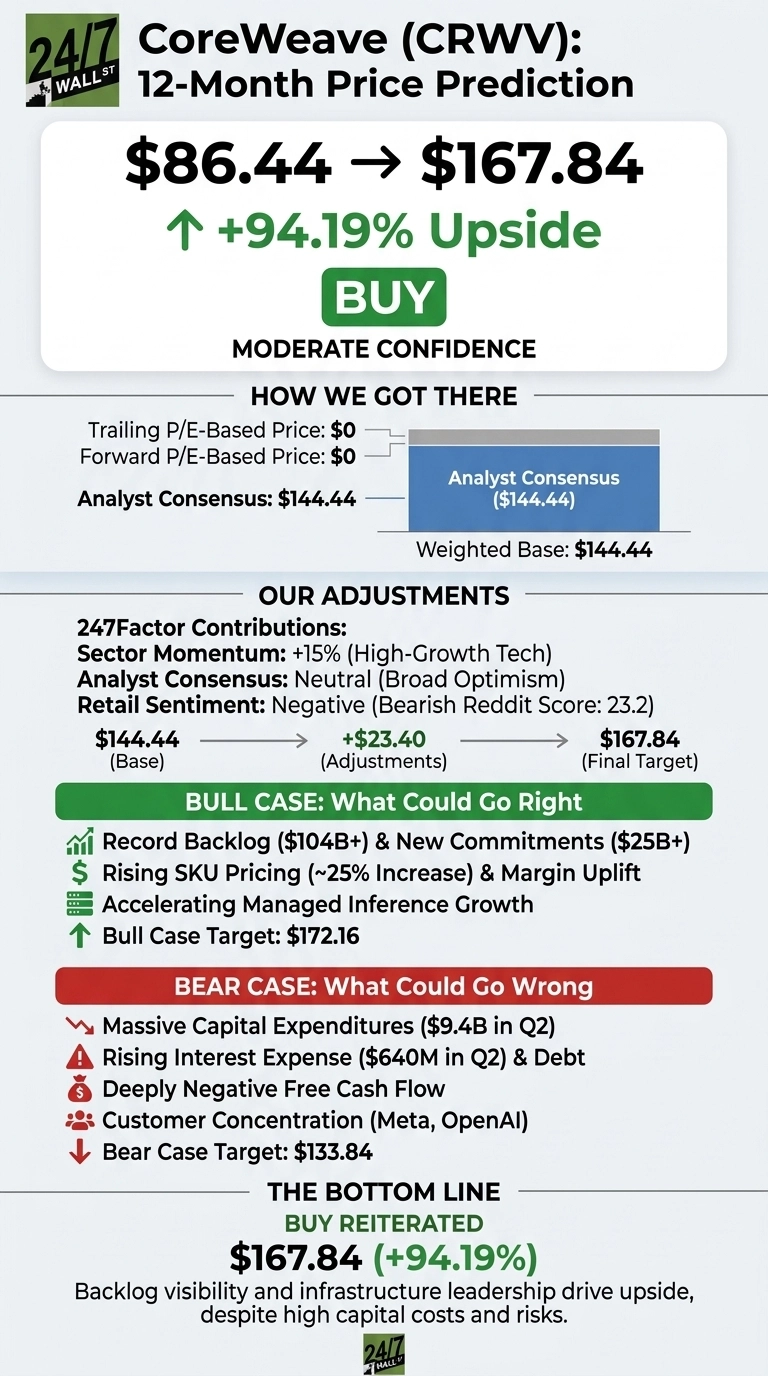
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $86.44 |
| 24/7 Wall St. Price Target | $167.84 |
| Upside | 94.19% |
| Recommendation | BUY |
| Confidence Level | 50% |
A Nasdaq-100 Newcomer With a Bruised Chart
CRWV has traded like a barometer of AI sentiment. Shares are down 2.87% in the past week and 4.88% over the past month, sitting roughly 44% below the $153.20 52-week high but still 20.71% higher year to date.
Q2 2026 results on August 11 beat both lines: revenue of $2.575 billion grew 112.32% year over year, GAAP EPS of -$1.14 beat the -$1.447 consensus, and backlog hit $104 billion.
Management disclosed more than $25 billion of net new commitments in early Q3, plus Nasdaq-100 inclusion. Rising interest expense and dilution fears have weighed on the stock.

Bull Case for $172 and Beyond
The bull case starts with backlog conversion. Management guided full-year 2026 revenue of $12.4 billion to $13.2 billion and year-end annualized run rate of $18.5 billion to $19.5 billion. Managed inference ARR jumped from $1 million to more than $100 million in months.
The July SKU price hike of roughly 25% should show up in Q4 margins, expected to reach the low teens.
CoreWeave validated NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) Vera Rubin NVL72, driving 5 to 10 percentage points of contribution-margin uplift on new contracts. Our bull-case one-year target sits at $172.16.
What Could Go Wrong
The bear case is a balance-sheet argument. Q2 capex of $9.4 billion and interest expense of $640 million (up from $267 million a year earlier) produced a $626 million net loss.
CoreWeave cut its weighted average cost of debt by nearly 300 basis points, worth about $1.1 billion in annualized savings, and asset-level debt is designed to be repaid during initial deployment.
Other risks include a securities fraud class action tied to Q4 2025 filing and customer concentration around Meta (NASDAQ:META) and OpenAI. Our downside scenario lands at $133.84, well above today’s price.
How CoreWeave Compares to Nebius and Oracle
Nebius Group (NASDAQ:NBIS) is the closest neocloud peer. Nebius posted Q2 2026 revenue of $582.3 million, up 454% year over year, with remaining performance obligations of $37.5 billion and a market cap of $55.79 billion.
CoreWeave’s $44.87 billion market cap is smaller despite a backlog nearly three times larger, suggesting our target is conservative.
Oracle (NYSE:ORCL) shows the scale contrast. Oracle’s Q1 FY2027 IaaS revenue grew 121% to $7.39 billion, and RPO ballooned to $664 billion.
Oracle trades on a roughly 20x forward earnings multiple with real profits, while CoreWeave trades on backlog and EBITDA. CoreWeave’s pure-play exposure and 59% adjusted EBITDA margin should command a premium relative to today’s price.
CoreWeave Price Prediction 2026-2030
Our 24/7 Wall St. price target of $167.84 argues for a buy at moderate confidence.
The key factor is backlog visibility: $104 billion contracted, plus $25 billion booked in early Q3, against a $44.87 billion market cap. CoreWeave is one of the clearest picks-and-shovels ways to play the AI data-center buildout (we profiled seven more of these infrastructure suppliers, from power to cooling, in a free report you can grab here).
The setup looks compelling if Q4 margins hit the low teens as guided, and would warrant caution if interest expense climbs faster than revenue or if a major customer trims commitments.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | ~$95 |
| 2027 | $167.84 |
| 2028 | ~$266 |
| 2029 | $364.34 |
| 2030 | ~$446 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.