Prediction: The Biggest Opportunity in AI Hardware May Still Be NVIDIA
Wall Street's consensus target already implies strong gains for NVIDIA, but one bull case pushes far beyond what analysts are willing to say publicly. The path there hinges on three catalysts that have to land in the same window.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
AI hardware remains the loudest trade on Wall Street, and the picks-and-shovels crowd keeps getting paid.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is up 22.94% year to date, Micron Technology (NASDAQ:MU) has surged 278.77%, and SanDisk (NASDAQ:SNDK) has ripped 692.86% as HBM and NAND became the AI industry’s scarcest resource.
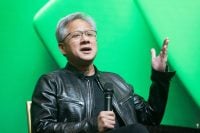
CEO Jensen Huang calls this the largest infrastructure expansion in human history, and the numbers back him up. Here is how NVIDIA, the anchor of the trade, could reach $350 per share in 2027.
Wall Street Already Sees Meaningful Upside From Here
The sell-side consensus 12-month target on NVIDIA sits at $327.70, backed by 48 Buy and 9 Strong Buy ratings against just three cautious calls.

Analysts model FY27 EPS of $9.31 rising to $15.68 in FY28, and the FY28 average has jumped from $12.67 just 90 days ago. That includes 42 upward EPS revisions in the last month with zero cuts. Momentum in the estimates is doing the analysts’ work for them.

Path to $350: The Valuation Math
At today’s $228.74, NVIDIA trades at a forward P/E of 25, barely above the S&P 500. A move to $350 would represent 53% upside and price the stock at roughly 38x FY27 earnings.
Look one year further and $350 is only 22x FY28 estimates, essentially a market multiple for a company Huang said will grow revenue by approximately 70% in fiscal 2028.

What could push shares to $350?
- Beat streak intact. NVIDIA has topped estimates for five consecutive quarters, most recently posting Q2 revenue of $96.22B, up 105.8% YoY.
- Vera Rubin ramp. Management called it the fastest product ramp in NVIDIA’s history, worth $40 billion per gigawatt versus $25B for Blackwell.
- Hyperscaler capex. Top five hyperscalers are on track for nearly $800 billion in 2026 and $1.3 trillion in 2027.
- Memory partners confirm the demand. Micron just guided FY Q4 revenue to $50B with EPS near $31, while SanDisk reported datacenter revenue up 437% for fiscal 2026. Both cite orders committed beyond calendar 2027.
NVIDIA’s History Says $350 Is Within Reach
A 53% year is aggressive for a $5.5 trillion company, yet NVIDIA has done far more, far more often. Shares are up 947.09% over five years and 14,254.64% over ten.
Even in 2024, when NVIDIA was already a mega-cap, the stock rose 171%. With supply still the binding constraint, the 30-day estimate revisions running 39 up to 1 down for FY27 suggest actual results will keep pushing the target higher.
Bottom Line: $350 Is a Stretch Goal With a Real Blueprint
Hitting $350 requires roughly 53% upside, above the Street’s $327.70 consensus but far from unprecedented for NVIDIA.
If Vera Rubin ships on schedule, hyperscaler capex holds, and China supply questions stay excluded from the model as a hidden option, the FY28 multiple compresses to a market average at $350.
Add in Micron and SanDisk validating the demand, and the AI hardware trade still has room to run (we profiled seven more suppliers powering the data-center buildout, from power to cooling, in a free report you can grab here). Returns like this shouldn’t be expected every year, but we’ve outlined the blueprint for how NVIDIA could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.