Why Cathie Wood Is Trimming the World’s Biggest Tech Stock to Bet on a Space Company
ARK Invest just rotated out of the world's most valuable company to load up on a loss-making space startup trading at 58 times sales. The reasoning reveals something important about how ARK thinks the next decade of infrastructure gets built.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
ARK Invest’s daily trade files show Cathie Wood’s funds adding to Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) while trimming Alphabet (NASDAQ:GOOGL). The disclosures themselves list tickers, funds, and share amounts. They do not include a reason. Anything offered as motivation from here is inference, and readers should treat it that way.
What is verifiable from ARK’s own portfolio data: as of the July 31, 2026 ARKK snapshot, Alphabet was still held across both share classes, with $118.5 million in GOOG (2.13% of net assets) and $27.0 million in GOOGL (0.49% of net assets). Rocket Lab was not in the ARKK snapshot at that date, consistent with recent RKLB adds landing in ARK’s space and next-generation internet vehicles rather than the flagship.
What Is Actually Happening at Rocket Lab
The buy comes into a business that is being rebuilt in front of investors. Rocket Lab reported Q2 2026 revenue of $234.07 million, up 62% year over year, with backlog reaching a record $2.36 billion. Q3 revenue guidance is $250 million to $265 million.

Two developments matter more than the quarter. First, Rocket Lab announced a deal to acquire Iridium Communications, funded in part through equity issuance that has already brought in $1.53 billion in ATM proceeds during the first half of 2026. Iridium would bolt a recurring satellite communications revenue stream onto a company whose top line has been dominated by launches and lumpy program awards. Recurring revenue commands a different multiple than project revenue because it is predictable, higher margin at scale, and can be forecast years out.
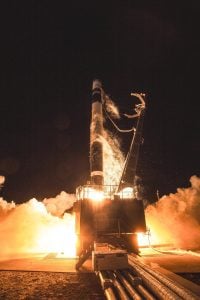
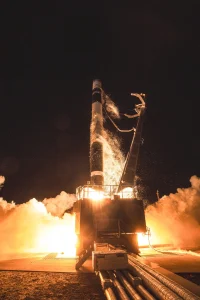
Second, the medium-lift Neutron rocket is targeted for launch pad delivery in Q4 2026, following an earlier stage-one tank test failure that pushed the timeline. If Neutron flies, Rocket Lab moves from small-satellite launch specialist to a genuine competitor for larger national security and commercial payloads.
The valuation reflects the promise well ahead of the profits. Shares trade at $70.23, with a price-to-sales ratio of 58 and Q2 net income of negative $49.3 million. Details on the Iridium financing and dilution risk sit in Rocket Lab’s August 10, 2026 8-K.

Why ARK Is Trimming Alphabet
The Alphabet reduction is the smaller side of the rotation. Institutions trim mega-caps for position sizing, index-drift management, and mandate reasons. Alphabet just posted Q2 2026 revenue of $119.80 billion (+24.23% year over year) with Google Cloud growth of 82% to $24.77 billion. Shares are $338.19, up 34.27% over the past year. That is not the profile of a business ARK would be exiting on fundamentals.

A defensible inference: ARK’s mandate rewards concentration in disruptive, small- and mid-cap names. Alphabet at a ~$4.29 trillion market cap with FY2026 capex guidance of $175 billion to $185 billion and Q2 free cash flow of negative $5.86 billion is a different asset than what ARK typically overweights.
What Following an ARK Trade Actually Means for Retail
ARK is a high-conviction, high-volatility manager. Its disclosed trades are point-in-time snapshots, and the funds turn over positions frequently. Rocket Lab is a speculative holding: unprofitable, richly valued, exposed to Neutron schedule slippage, and issuing equity to fund acquisitions. It carries materially higher risk than a mega-cap position, and readers should size it accordingly.
What to watch next: Neutron’s arrival at the launch pad, closing progress on Iridium, and Rocket Lab’s Q3 report against the $250M-$265M guide. On Alphabet, keep an eye on whether cloud growth holds above 60% and whether capex intensity begins to compress free cash flow further into 2027.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.