America Needs More Electricity. Here’s What It Could Mean for DTE Energy
Michigan's utility giant just locked in hyperscale data center deals with Oracle and Alphabet while its stock slid nearly 10% in a month, creating a rare gap between what the market sees and what the load growth math suggests.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
DTE Energy (NYSE: DTE | DTE Price Prediction) sits at the intersection of two powerful forces: the AI-driven surge in US electricity demand and Michigan’s constructive utility regulatory framework.
With 2.4 gigawatts of executed hyperscale data-center agreements already inked with Oracle (NYSE: ORCL) and Alphabet (NASDAQ: GOOGL), plus five to six gigawatts of additional pipeline, the growth story is tangible.
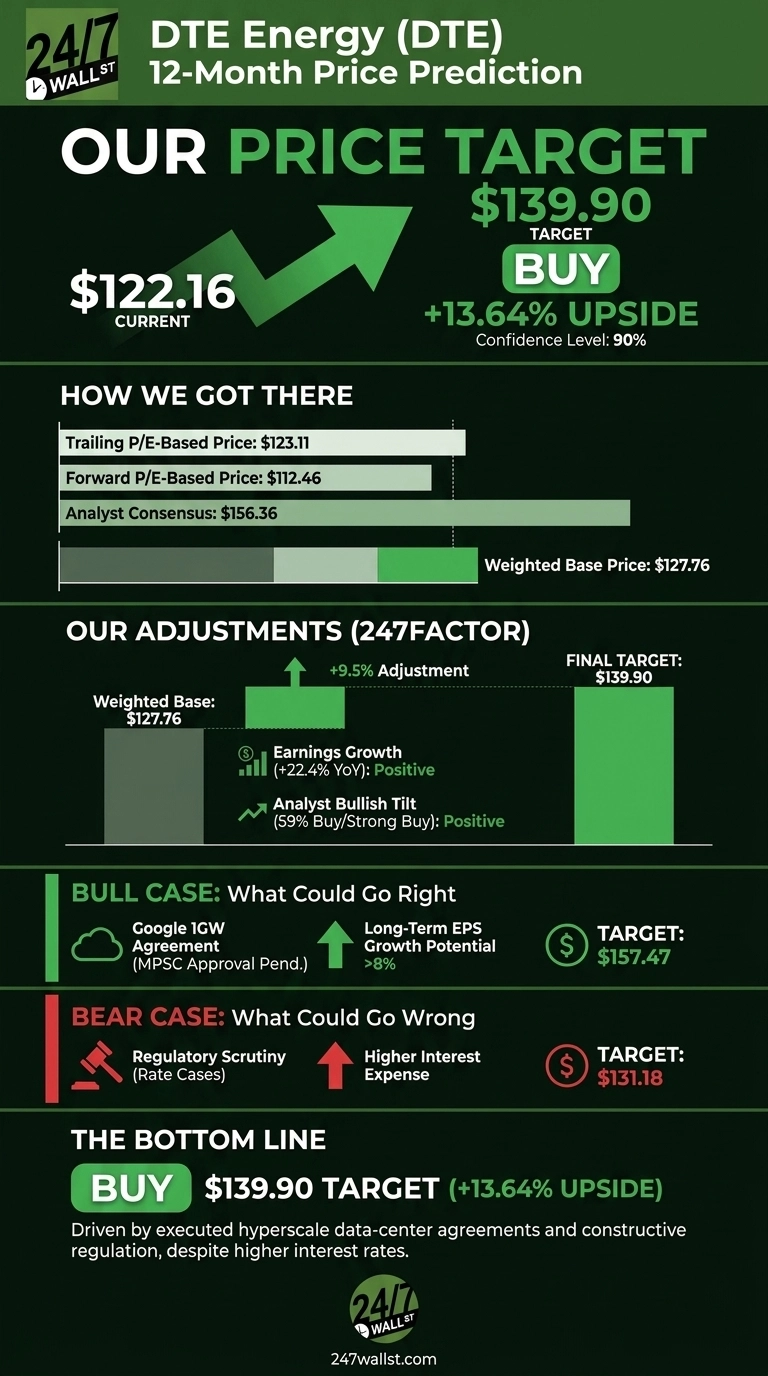
Our 24/7 Wall St. price target for DTE Energy is $139.90, pointing to 13.64% upside from the current $122.16. Confidence in the call is high, at 90%.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $122.16 |
| 24/7 Wall St. Price Target | $139.90 |
| Upside | 13.64% |
| Signal | Positive |
| Confidence Level | 90% |
Why Michigan’s Data Center Boom Is Repricing DTE
DTE shares fell 9.12% over the past month, pressured by the 10-year Treasury yield at 4.96%.
Fundamentals diverge sharply. Q4 2025 operating EPS of $1.65 beat consensus by 8.29%, and full-year 2025 operating EPS reached $7.36 versus $6.83 in 2024.
Q1 2026 operating EPS of $1.95 missed the $2.03 estimate, though management reaffirmed 2026 guidance of $7.59 to $7.73. The Google 1 GW Van Buren Township agreement could drive roughly $5 billion of incremental capital investment through 2032.

Why Bulls See a Breakout to $157
CEO Joi Harris said “three gigawatts gets DTE ‘eight plus'” on long-term operating EPS growth. Google alone brings “solidly to eight.” Add the two gigawatts in advanced discussions targeted for signing by year-end, and the growth range could reset higher.
Bull-case scenario points to $157.47, matching the Street’s $156.36 mean target with 10 buy or strong buy ratings outweighing 7 holds.

Risks Worth Watching
Regulatory scrutiny of rate cases is real. DTE Gas swung to a $4M net loss in Q2 2026 with uncollectible expense doubling to $14M. Higher interest expense pressured Corporate & Other by $54M in Q1.
The Gas weakness reflects a pending MPSC rate case seeking a $163M base rate increase and an ROE step-up to 10.25%, with a final order expected this month. Planned equity issuances of $500M to $600M annually through 2030 dilute per-share metrics. Bear-case scenario lands at $131.18, still above today’s price.
How DTE Compares to CMS Energy and Southern Company
CMS Energy (NYSE: CMS) is DTE’s closest regulatory analog in Michigan. CMS reaffirmed 2026 adjusted EPS guidance of $3.83 to $3.90 with a roughly 9 GW economic development pipeline on a $24 billion capital plan. DTE’s larger $36.5B plan and executed hyperscale contracts provide more visible growth, making our target reasonable.
Southern Company (NYSE: SO) is the national bellwether for data-center-driven utility growth. Q2 2026 adjusted EPS of $1.13 beat the $1 consensus by 13%, with commercial kWh sales up 7.3%. Southern trades at a premium reflecting its Georgia footprint. DTE’s cheaper forward multiple of 14x on similar growth suggests room to expand if execution holds.
| Company | Market Cap | Data Center Pipeline |
|---|---|---|
| DTE Energy | ~$25.45B | 2.4 GW signed + 5-6 GW pipeline |
| CMS Energy | ~$19.5B | ~9 GW pipeline |
| Southern Company | ~$95.8B | Southeast hyperscale leader |
Why DTE Looks Compelling Here
The 24/7 Wall St. price target of $139.90 carries 90% confidence at current levels. The executed hyperscale book plus a credible path to 8%-plus EPS growth drive the call.
Catalysts to watch include Google MPSC approval and the September gas order landing constructively.
Key risks include Treasury yields breaking 5.25% or a third gigawatt agreement slipping into 2027.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $126.91 |
| 2027 | $139.87 |
| 2028 | $155.13 |
| 2029 | $165.97 |
| 2030 | $178.20 |
These projections assume DTE executes its capital plan and converts advanced-stage data-center discussions into contracts. Upside could come from a third gigawatt agreement; downside from persistently high long-term yields or regulatory pushback.
The utilities powering this buildout are a story in themselves, and we pulled together seven of the AI infrastructure names benefiting from it in a free report you can grab here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.