Price Prediction: ON Semiconductor Stock Looks Ready for Its Next Move
ON Semiconductor has pulled back sharply while its AI data center business accelerates toward a potential doubling, so the real question is whether the selloff created an opportunity or a warning sign worth heeding.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
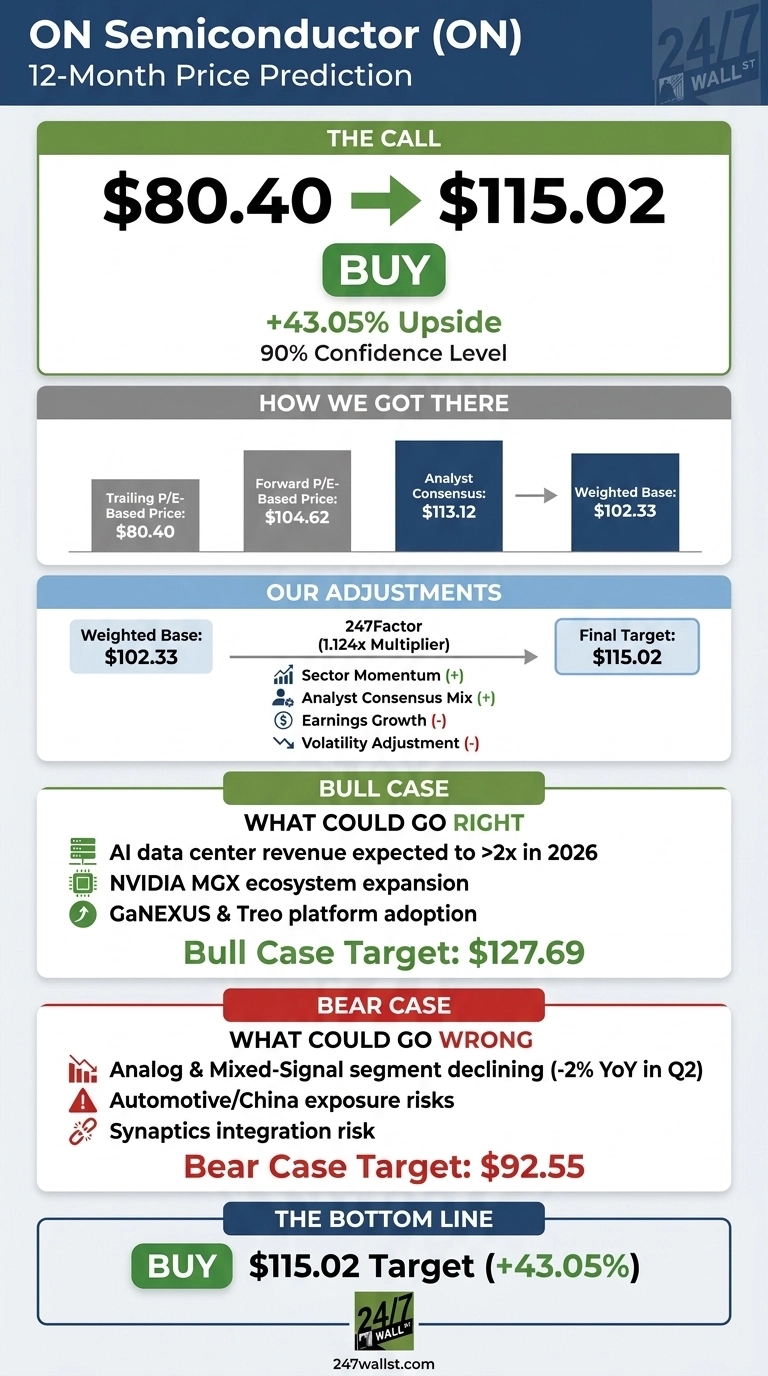
Our call on ON Semiconductor (NASDAQ:ON | ON Price Prediction) is straightforward. The 24/7 Wall St. price target for onsemi is $115.02, pointing to 43.05% upside from the current $80.40 quote. Our recommendation is buy, with a 90% confidence level.
A quadrupling in free cash flow, an AI data center business set to more than double this year, and a fresh $6 billion buyback authorization make the risk/reward attractive after the recent pullback.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $80.40 |
| 24/7 Wall St. Price Target | $115.02 |
| Upside | 43.05% |
| Recommendation | BUY |
| Confidence Level | 90% |
From Cyclical Trough to AI Reacceleration
Shares have cooled recently, sliding 9.7% in the past week and 11.86% over the past month, yet ON is still up 48.48% year to date and 41.5% over the past year. The stock sits 16% below its 52-week high of $134.92, well off the $44.56 low set during the analog cycle bottom.
Q2 2026, filed August 3, 2026, delivered clean results. Non-GAAP EPS of $0.74 beat the $0.72 consensus, revenue of $1.60 billion grew 9.2% year over year, and Power Solutions Group revenue rose 19% to $829 million.
Free cash flow of $425.4 million was roughly quadruple the year-ago figure. CEO Hassane El-Khoury told investors “AI data center remains our fastest-growing business, and we now expect revenue to more than double in 2026.”
Why Bulls See a Breakout Ahead
Management guided Q3 revenue to $1.65 billion to $1.75 billion and non-GAAP EPS to $0.81 to $0.93, both above trailing quarters. The AI data center thesis has real receipts: expanding NVIDIA MGX ecosystem wins, a strategic EliteSiC and silicon MOSFET platform deal with Great Wall, and the new GaNEXUS gallium nitride portfolio spanning 40V to 650V.
Automotive momentum layers on top, with 900V EV architecture wins at Geely and NIO plus the Rivian R2 zonal architecture. In the bull case, ON reaches $127.69 within twelve months, roughly 58.81% upside. Analyst consensus of $113.12 sits in that neighborhood, backed by 11 Buy ratings against zero Sells.
The Risks Worth Watching
The bear case is not trivial. Barclays initiated at Equal-Weight with a $75 price target, flagging automotive and China exposure. The Analog and Mixed-Signal segment shrank 2% year over year in Q2, restructuring and impairment charges hit $41.2 million in the quarter, and the pending Synaptics acquisition adds integration risk. A beta of 2.01 means macro shocks land hard.
Our bear case lands at $92.55, still above today’s price. Bulls counter that restructuring reflects deliberate portfolio pruning tied to Treo and GaNEXUS investment, and Q2 non-GAAP gross margin already recovered to 39.3% with operating income up 33.71%.
How ONsemi Compares to Texas Instruments and Microchip
Texas Instruments (NASDAQ:TXN) is the analog benchmark. TXN posted Q2 2026 revenue of $5.46 billion, up 22.8% year over year, with the Analog segment growing 26% to $4.365 billion. At a $245.7 billion market cap, TXN trades at a premium multiple to ON, but faster top-line growth and higher margins set the bar our target implicitly benchmarks against.
Microchip Technology (NASDAQ:MCHP) is the tighter recovery comp. Microchip’s most recent quarter delivered revenue of $1.31 billion, up 35.1% year over year off a deeper trough, with fiscal Q1 2027 guided to $1.442 billion to $1.469 billion. Its $40.8 billion market cap on lower absolute revenue suggests the market pays up for cycle-recovery leverage. Our $115.02 target looks reasonable: ON has larger absolute revenue and stronger AI data center exposure than Microchip.
ON Semiconductor Price Prediction 2026 to 2030
The 24/7 Wall St. price target of $115.02 and buy rating at 90% confidence rest on one core call: AI data center revenue doubling in 2026 more than offsets residual weakness in Analog and Mixed-Signal, and the buyback pace absorbs convertible dilution.
The bull thesis strengthens if Q3 comes in at or above the guided midpoint and gross margin holds above 40%. The setup weakens if AI data center growth decelerates below the doubling target or Synaptics integration proves messier than management projects.
Looking further out, here is where our model projects onsemi could trade, assuming continued execution on the intelligent power and AI data center roadmap.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $115.02 |
| 2027 | $138.00 |
| 2028 | $165.00 |
| 2029 | $192.00 |
| 2030 | $217.24 |
These projections assume onsemi continues executing on its AI data center, EV, and industrial power roadmap. Significant upside or downside could result from a step-change in AI power tree adoption or a sharper-than-expected automotive downturn.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.