Onsemi’s AI Data Center Sales Reportedly Grew 175%. Is That the Chip Stock’s New Story?
Onsemi just posted its fourth straight earnings beat while trading nearly 48% below its 52-week high, and a surprise surge in one fast-growing segment has analysts split on whether the stock is a bargain or a value trap.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
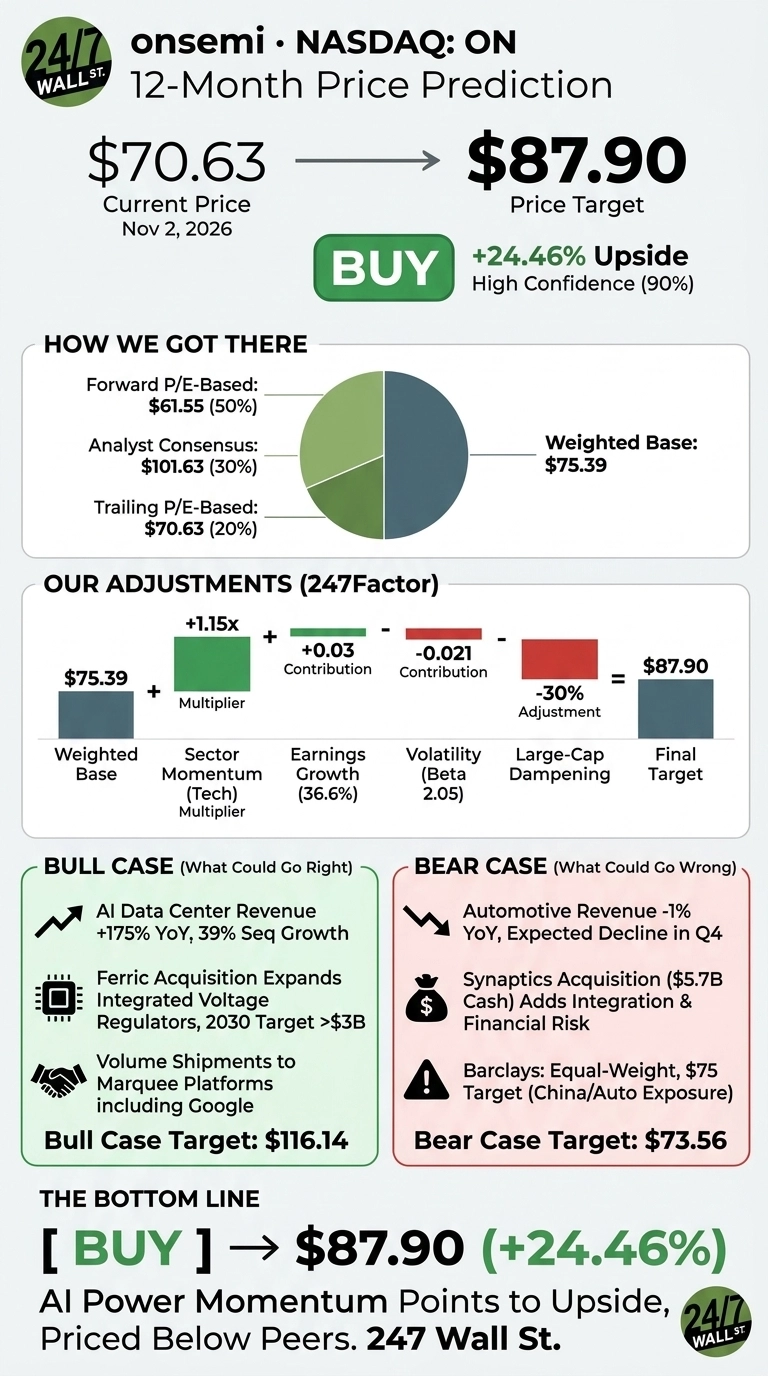
The 24/7 Wall St. price target for onsemi (NASDAQ:ON | ON Price Prediction) is $87.90. This suggests 24.46% upside from the $70.63 close on November 2, 2026. The stock earns a buy rating with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $70.63 |
| Price Target from 24/7 Wall St. | $87.90 |
| Upside/Downside | 24.46% |
| Recommendation | BUY |
| Confidence Level | 90% |
The catalyst came after the market closed on November 2. AI data center revenue reached $180 million, up 175% year over year. Management now expects about $620 million from AI data centers in 2026. Shares traded at $73 premarket, up 4.12%.

Fourth Straight Beat Lands With Shares Far Below Their High
Coming into the report, onsemi had fallen 14.01% over the past month and 1.43% over the past week. Even so, it remains up 34.81% year to date. It trades 47.65% below its 52-week high of $134.92 and 58.51% above its 52-week low of $44.56.
Third-quarter revenue came in at $1.7223 billion, ahead of the $1.7046 billion estimate, and grew 11.1% year over year. Non-GAAP EPS of $0.90 beat the $0.8778 estimate. GAAP gross margin expanded to 41.4% from 37.9% a year earlier. Free cash flow rose 153% to $488.6 million. Fourth-quarter guidance calls for non-GAAP EPS of $0.95 to $1.07.
Why Bulls See $116 Within Reach
In our bull case, the stock reaches $116.14. Management expects AI data center revenue to double over 2026 in 2027, and that growth would start from a larger base. The $600 million Ferric deal moves onsemi into integrated voltage regulators that sit next to the GPU.
After the deal, management raised its 2030 AI data center target to greater than $3 billion. onsemi has also started volume shipments into “multiple marquee platforms, including Google.” Jefferies analyst Blayne Curtis called the 2027 doubling “pretty impressive.”

Automotive Weakness and a $5.7 Billion Deal Could Drag ON Lower
The bear case puts the stock at $73.56. AI data centers still made up only about 10.45% of quarterly revenue. Automotive revenue of $777 million fell 1%, and management expects a high single-digit decline in the fourth quarter. The $5.7 billion cash price for Synaptics adds integration risk.
Barclays rates the stock equal-weight with a $75 target, citing exposure to China and automotive. On the other side of the equation, management says the automotive dip shows supply being shifted to AI and industrial customers, and it expects automotive growth to return to its long-term target in 2027.

onsemi Trades Below Microchip and Texas Instruments
Microchip Technology (NASDAQ:MCHP) competes with onsemi in power and analog chips and is also chasing data center connectivity. It trades at 21x forward earnings.
Texas Instruments (NASDAQ:TXN) is the standard benchmark for analog valuation and trades at 26x, with quarterly revenue growth of 27.7%. Our target values onsemi at about 20x forward EPS, which is still below both peers. The target therefore looks conservative.
| Company | Forward P/E | EV/EBITDA |
|---|---|---|
| onsemi | 16 | 18.2 |
| Microchip | 21 | 32.28 |
| Texas Instruments | 26 | 25.6 |
AI Power Momentum Points to Upside
The 24/7 Wall St. price target of $87.90 carries a buy rating with 90% confidence. The key factor is that a fast-growing AI power business is priced at a discount to its peers (we rounded up seven more companies feeding the AI data-center expansion, from power to cooling, in a free report).
I’d see more upside if AI revenue stays on track to double in 2027 and automotive sales recover. I’d see less if the Synaptics deal reduces margins or AI orders slow. For now, the evidence supports the upside case.
onsemi Price Prediction 2026-2030
Over a longer horizon, the 24/7 Wall St. price target model projects the following base-case prices, assuming onsemi’s current growth path holds.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month) | $87.90 |
| 2027 | $89.92 |
| 2028 | $98.68 |
| 2029 | $119.04 |
| 2030 | $128.95 |
These projections assume onsemi keeps executing its AI power strategy. The figures could prove much higher or lower depending on how the Ferric and Synaptics integrations go and on when automotive demand recovers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.