ON Could Be One of the Semiconductor Sector’s Biggest Comeback Stories
ON Semiconductor crashed hard in 2025, but the numbers coming out of its latest quarter tell a very different story, and the question now is whether the market has fully caught on yet.


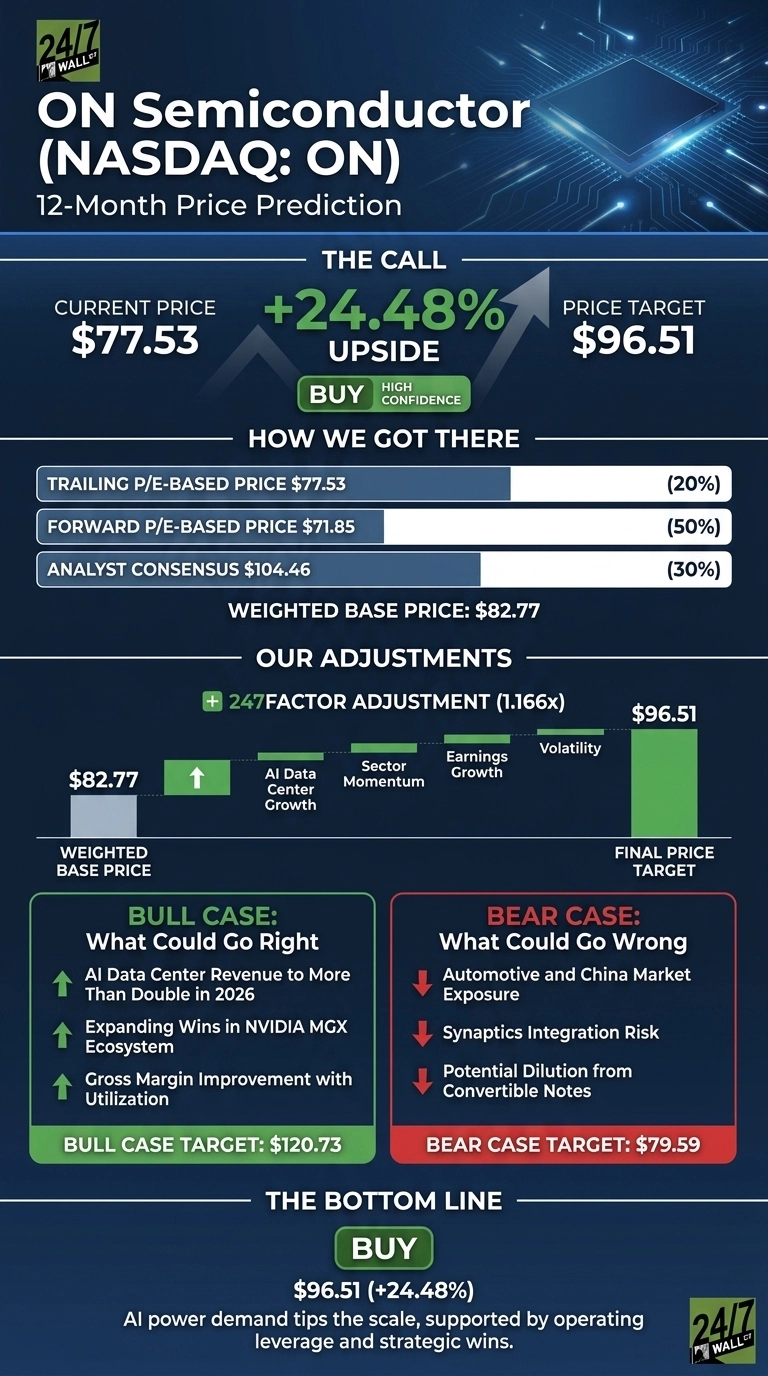
The 24/7 Wall St. price target for ON Semiconductor (NASDAQ:ON | ON Price Prediction) is $96.51 over the next 12 months. From a recent price of $77.53, that works out to 24.48% upside. The stock gets a buy rating from our model, and its confidence is high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $77.53 |
| Price Target from 24/7 Wall St. | $96.51 |
| Upside/Downside | 24.48% |
| Recommendation | BUY |
| Confidence Level | 90% |

ON has climbed out of the trough. Revenue fell 22.39% year over year in Q1 2025, then grew 9.18% in Q2 2026. Management now expects AI data center revenue to more than double in 2026, and Q3 guidance calls for non-GAAP EPS of $0.81-$0.93.
A 42% Rally Interrupted by a Sharp Pullback
The stock is up 42.27% year to date and 54.17% over the past year. Over the past week it fell 9.25%, though it is still up 8.54% over the past month. Shares sit well below the 52-week high of $134.92 and well above the low of $44.56.
In Q2, revenue came in at $1.6035B, beating estimates by 0.89%. Non-GAAP EPS was $0.74 against a $0.7153 estimate. Free cash flow reached $425.4M. ON also put through a price adjustment that took effect on October 10, which points to firm demand.

Why Bulls See $120 and Beyond
Management raised its 2030 AI data center addressable market from $12 billion to almost $50 billion. All of that expansion still has to be powered, cooled, and connected by somebody, and we rounded up seven of those suppliers in a free AI infrastructure report. Lead times extended from approximately 27 weeks to approximately 32 weeks.
Utilization rose to 83%, and each additional point adds 25 to 30 basis points of gross margin. A $6B buyback adds further support. Among analysts, 2 rate the stock a strong buy and 12 rate it a buy. Our bull case reaches $120.73.

Risks That Could Stall the Comeback
Barclays started coverage at equal-weight with a $75 target and noted ON’s automotive and China exposure. Analog and Mixed-Signal revenue fell 2%. The Synaptics (NASDAQ:SYNA) deal, expected to close in mid-2027, brings integration risk, and the convertible notes could dilute shareholders.
The trailing P/E of 249 looks alarming, but it reflects low 2025 earnings, including $666.9M of restructuring charges. Those charges dropped to $41.2M in Q2. The bear case sits at $79.59.

ON Trades Between NXP and Texas Instruments
NXP Semiconductors (NASDAQ:NXPI) is ON’s most direct automotive and industrial rival. It trades at 13x forward earnings while growing revenue 19.48%, so ON looks pricier on recovery-stage earnings.
Texas Instruments (NASDAQ:TXN) is the analog and power benchmark. It commands 28x forward earnings on 22.82% growth. Our target implies about 24x forward EPS, which sits between the two. That looks reasonable as long as ON’s margins keep recovering.
| Company | Forward P/E | Q2 2026 Revenue Growth |
|---|---|---|
| ON Semiconductor | 19x | 9.2% |
| NXP | 13x | 19.48% |
| Texas Instruments | 28x | 22.82% |
ON Semiconductor Price Prediction 2026-2030
I see the 24/7 Wall St. price target of $96.51 as well supported, and our model’s buy rating carries 90% confidence. Operating leverage is the key factor.
The thesis gets stronger if Q3 gross margin lands within the 40%-42% guidance. It weakens if automotive demand fades or the Synaptics integration struggles. I think the recovery has further to run.
Going forward, here is where our model projects ON could trade, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $83.57 |
| 2027 | $96.51 |
| 2028 | $113.64 |
| 2029 | $123.49 |
| 2030 | $135.97 |
These projections assume ON keeps executing its current strategy. The adoption of 800-volt data center architectures could push results higher, while a decline in automotive demand could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.