Prediction: Google’s Next Chapter Could Be Worth Trillions More
Google Cloud is growing faster than AWS and Azure combined, yet the stock trades at a fraction of their valuations. Something in that gap either represents the biggest discount in mega-cap tech or a warning sign worth understanding before the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Google (NASDAQ: GOOG | GOOG Price Prediction) has quietly become the most interesting AI story in mega-cap tech. Google Cloud accelerated to 82% growth last quarter, Gemini reached 950 million monthly active users, and the stock trades at a discount to peers on forward earnings.
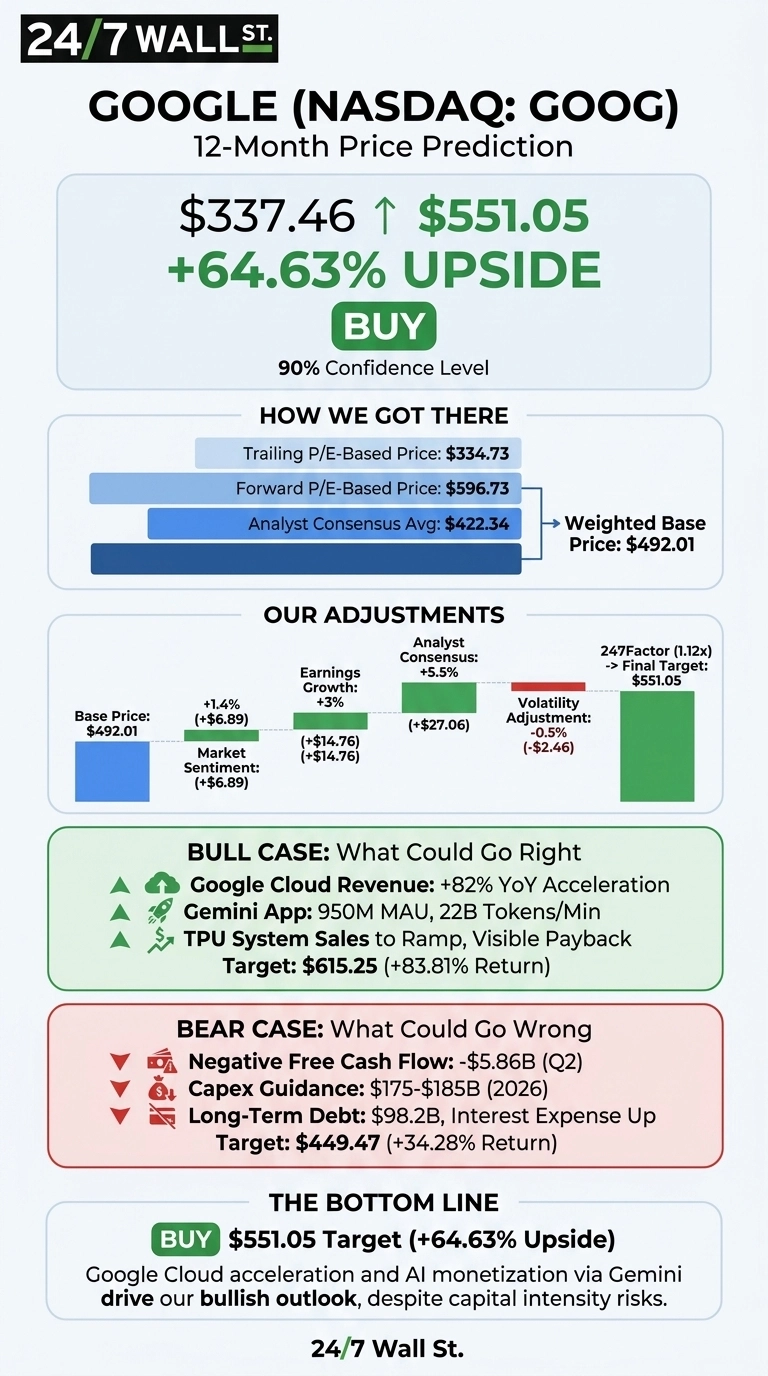
Our 24/7 Wall St. price target for Google is $551.05 over the next 12 months, implying 64.63% upside from $337.46. Rating: Buy with high conviction.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $337.46 |
| 24/7 Wall St. Price Target | $551.05 |
| Upside | 64.63% |
| Recommendation | BUY |
| Confidence Level | 90% |

Why Google Stock Is Coiled for a Breakout
The stock is down 0.56% over the past week but has returned 34.08% over the past year.
Q2 fiscal 2026 revenue of $119.80 billion grew 24.23% year over year, EPS of $9.11 beat consensus by 199.41%, and Google Cloud backlog swelled to $514 billion. Barron’s flagged Google’s geothermal partner Fervo Energy hitting a milestone, underscoring that the AI energy buildout extends well beyond chips.

Why Bulls See a $615 Breakout Ahead
The bull scenario points to $615.25, an 83.81% total return. Google Cloud growth accelerated from 48% to 63% to 82% in three quarters. Sundar Pichai says nearly 90% of the Fortune 100 now use Gemini Enterprise.
API token throughput runs at 22 billion tokens per minute, up from 16 billion a quarter ago. Of 61 analysts, 13 rate the stock Strong Buy and 43 Buy, with zero sells. Waymo, YouTube’s $60 billion-plus annual run rate, and 350 million paid subscriptions add optional upside.

What Could Go Wrong at $449
The bear scenario lands at $449.47, still 34.28% above today. The primary risk is capital intensity. 2026 capex guidance is $175 billion to $185 billion, free cash flow turned negative at -$5.855 billion in Q2, and long-term debt jumped to $98.2 billion.
Bulls counter that Cloud operating margin expanded to 35.6% from 20.7% and TPU system revenue is expected to ramp in 2027, showing visible payback. Regulatory overhang from the EU’s $3.5 billion fine remains but is priced in.
How Google Compares to Microsoft, Meta, and Amazon
Microsoft (NASDAQ: MSFT) trades at a P/E of 28 with Azure growing 43% last quarter. Google Cloud grew nearly double that at 82% yet GOOG trades at a P/E of just 17, making our target look conservative.
Meta Platforms (NASDAQ: META) trades at a P/E of 27 with Q2 ad revenue of $59.4 billion. Google’s search and network advertising outpaces that on scale at a lower multiple.
Amazon (NASDAQ: AMZN) trades at a P/E of 35 with AWS growing 37% in Q2. Google Cloud is now growing faster at a fraction of the multiple.
Google Price Prediction 2026-2030
The 24/7 Wall St. price target is $551.05, rating buy, confidence 90%. The key factor is the widening gap between Google Cloud’s growth rate and Google’s forward multiple.
The bullish case rests on Gemini and TPU monetization compounding into 2027. The bearish case is that the $175 billion to $185 billion capex bill destroys returns before producing them. My call is that the payback shows up.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $377 |
| 2027 | $551 |
| 2028 | $791 |
| 2029 | $968 |
| 2030 | $1,158 |
These projections assume Google executes on Cloud, Gemini, and Search monetization at its current pace. Significant upside or downside could result from AI infrastructure ROI and antitrust rulings.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.