The 6%-Yielding Blue Chip Has a New Catalyst
Verizon's stock has cooled sharply after a strong year, yet two fresh growth catalysts are quietly stacking up behind a 6% yield that already pays you to wait. Whether those drivers can actually move the needle depends on a debt…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
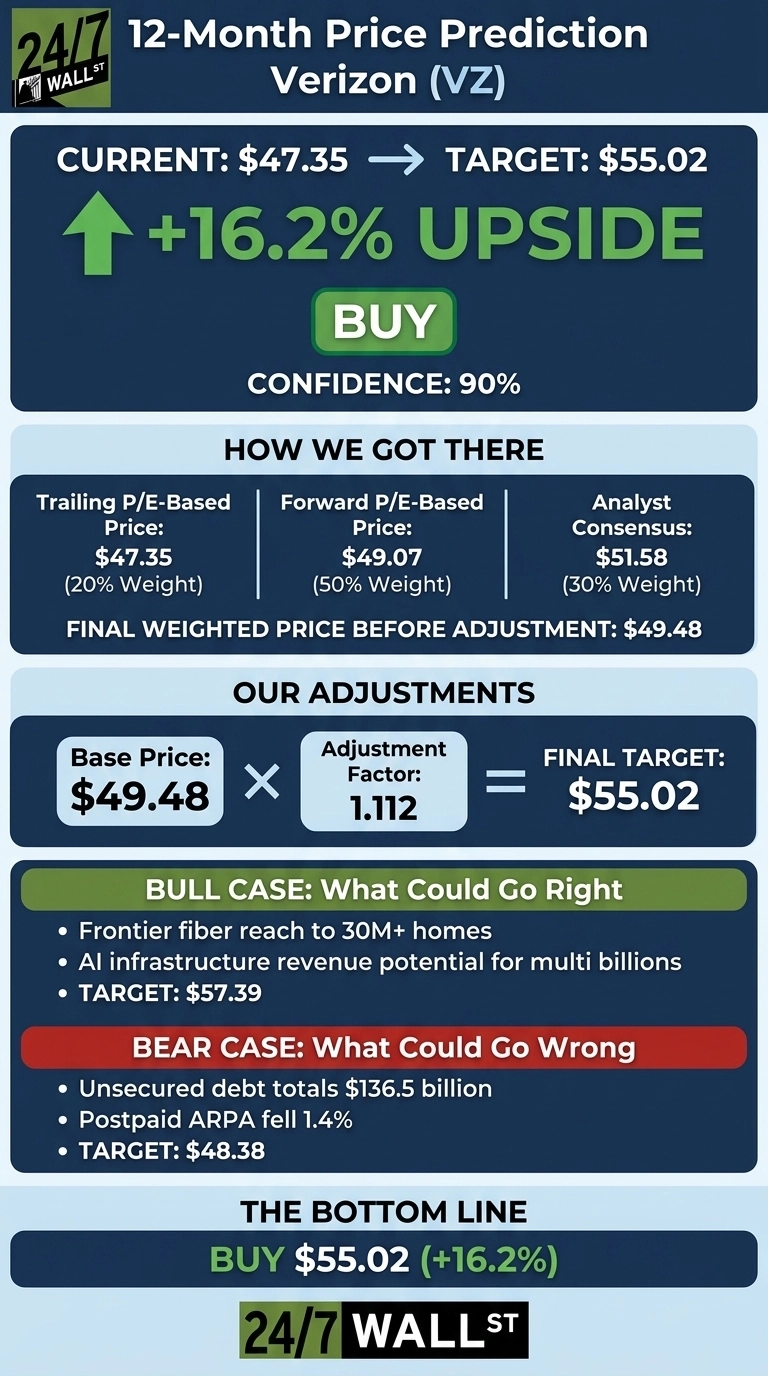
Verizon (NYSE:VZ | VZ Price Prediction) pays a dividend yielding 6.01%. It now has two new growth drivers on top of that: the Frontier fiber network and early AI infrastructure revenue. Our 24/7 Wall St. price target for Verizon is $55.02 over the next 12 months.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $47.35 |
| 24/7 Wall St. Price Target | $55.02 |
| Upside/Downside | 16.2% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model’s confidence is high. Verizon trades at about 9x forward earnings, and management raised full-year adjusted EPS guidance to $4.99 to $5.04. The yield pays shareholders while they wait for fiber and AI revenue to show up in the numbers.

Six Straight Beats, Yet Shares Cooled in September
VZ is up 21.46% year to date but has fallen 6.27% over the past month and 2.55% over the past week. It also lagged competitors on Tuesday (MarketWatch). Shares sit about 8.4% below the $51.67 52-week high and 29.5% above the $36.55 low.
Second-quarter adjusted EPS of $1.30 beat the $1.27 consensus, making it the sixth consecutive beat. Revenue fell 0.7% to $34.25 billion because Verizon by design pulled back on device subsidies. Service revenues rose 3.5%, and free cash flow grew 27.12%.

Why Bulls See $57 and Beyond
Verizon closed the Frontier deal on January 20, 2026, which extended its fiber reach to 30M+ homes and businesses. Management expects more than 32 million fiber passings by year-end and more than $1 billion in run-rate cost savings by 2028. Churn is almost 30% less on converged plans.
AI adds the second drivers. Earlier this year, management said hyperscaler talks carried “the potential for multi billions in revenues.” CEO Dan Schulman said in the second quarter that “with the emergence of AI infrastructure revenue, we are fundamentally reshaping Verizon’s growth trajectory.”
Among analysts, 2 rate the stock Strong Buy, 7 Buy and 16 Hold, with no Sell ratings. Our bull case is $57.39.

Debt and Softer ARPA Could Cap the Rally
Unsecured debt totals $136.5 billion, and leverage rose to 2.5x from 2.2x. Postpaid ARPA (average revenue per account) fell 1.4%, and GAAP net income dropped 21.07%.
That decline largely reflects $1.8 billion in pre-tax special items. Management also expects to repay substantially all of Frontier’s debt by the end of the year. Our bear case is $48.38.
Verizon Screens Cheaper Than AT&T and T-Mobile
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| Verizon | 9x | 6.01% |
| AT&T | 10x | 4.39% |
| T-Mobile | 12x | 2.46% |
AT&T (NYSE:T) is Verizon’s closest rival in fiber-plus-wireless bundles. It added 432,000 postpaid phones last quarter, ahead of Verizon’s 184,000. The market pays a slightly higher multiple for that momentum and gets a lower yield in return.
T-Mobile (NASDAQ:TMUS) is the growth contrast, with service revenue up 9%. Our target implies about 11x forward EPS, which sits between AT&T and T-Mobile. That places the 24/7 Wall St. price target at a reasonable spot within the peer group.
Verizon Price Prediction 2026-2030
Our 24/7 Wall St. price target of $55.02 carries a buy rating at 90% confidence. What tips the scale for me is free cash flow guidance of $21.94 billion to $22.14 billion, which well funds the dividend.
The setup looks compelling to me if Verizon keeps paying down Frontier debt on schedule and puts numbers on AI deals. I’d grow conservative if ARPA keeps slipping while leverage stalls. On balance, I think the risk-reward favors shareholders.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $47.88 |
| 2027 | $55.07 |
| 2028 | $61.74 |
| 2029 | $66.79 |
| 2030 | $71.86 |
These projections assume Verizon keeps executing on convergence and cutting debt. AI infrastructure contracts could push results above this path, while pricing pressure from rivals could pull them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.