The $600 Billion AI Opportunity Behind Oracle, We See 51% Upside
Oracle just posted its strongest quarter in years, yet the stock sits near a 52-week low while a $664 billion backlog quietly builds pressure. Something has to give, and the direction it breaks could mean everything for investors watching from…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
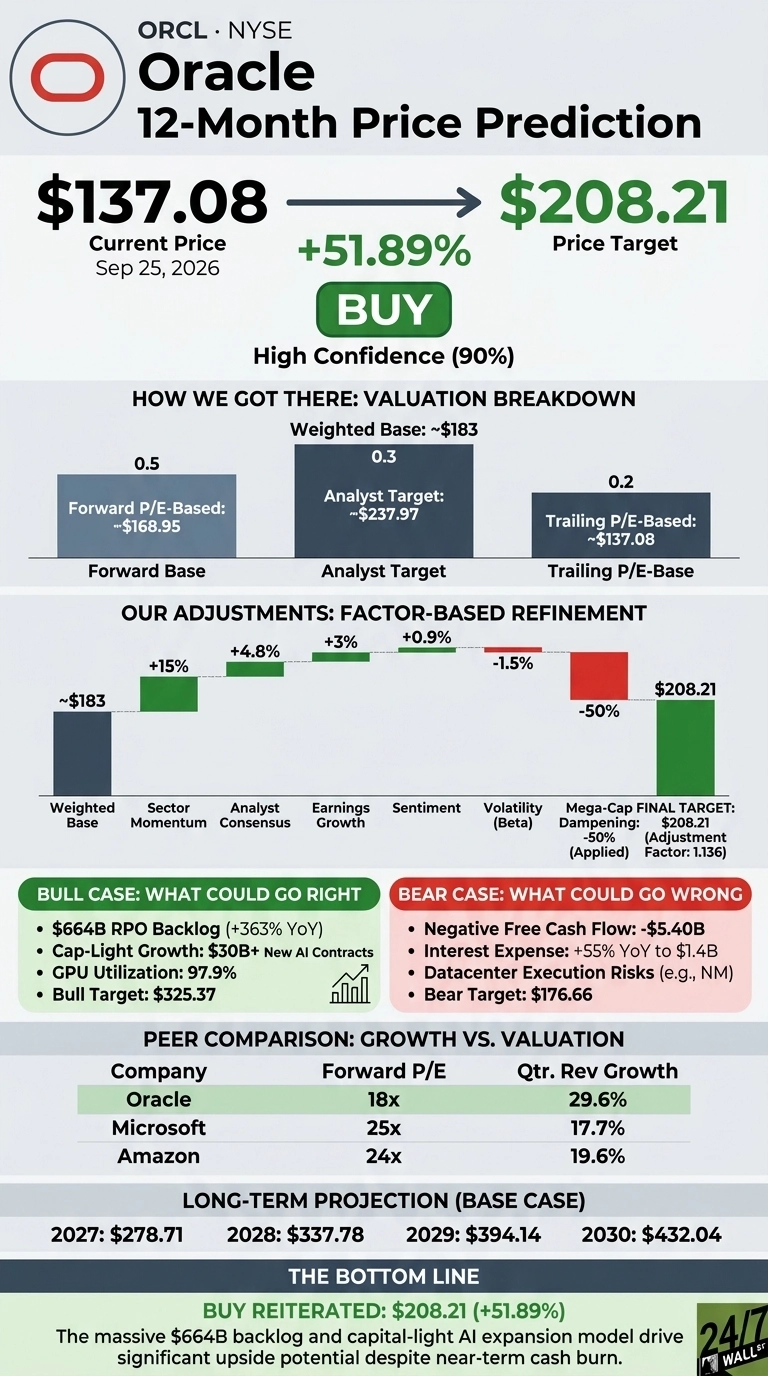
Oracle (NYSE:ORCL | ORCL Price Prediction) closed at $137.08 on September 25. Our 24/7 Wall St. price target for Oracle is $208.21 over the next 12 months. That means 51.89% upside, and the model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $137.08 |
| Price Target from 24/7 Wall St. | $208.21 |
| Upside/Downside | 51.89% |
| Recommendation | BUY |
| Confidence Level | 90% |

Oracle’s remaining performance obligations (RPO) reached $664 billion, up $209 billion year-over-year. RPO counts revenue customers have signed for but Oracle has yet to record.
Management expects around half to convert into sales over the next 36 months. The stock trades at 18 times forward earnings, or about 18x. That multiple leaves AI growth underpriced.

Record Quarter, 29% Slide: Why the Stock Hasn’t Followed
Oracle has fallen 7.12% in the past week, 7.91% over the past month and 28.98% year to date. The stock now trades about 57% off its 52-week high of $319.46 and 19.7% above its low of $114.50.
The latest pressure came from Oracle’s New Mexico data center. Oracle sent a force majeure notice on the project, a filing it says is “commonplace in developments of this scale”. The Wall Street Journal also reported that the site’s lease carries “hell-or-high-water” terms. On top of that, founder Larry Ellison pledged more Oracle shares for loans.
The fall has buried a strong earnings report. First-quarter fiscal 2027 revenue rose 29.6% to $19.34 billion, ahead of the $19.13 billion estimate. Non-GAAP EPS of $1.92 beat the $1.74 consensus. Cloud infrastructure revenue grew 121% to $7.39 billion.
Why Bulls See $325 Ahead
Oracle booked more than $30 billion in new AI contracts without adding capital of its own, using prepayments and bring-your-own-hardware deals. GPU utilization reached 97.9%, and renewals were priced at a 20% premium.
Management guides to at least $90 billion in fiscal 2027 revenue and $8.10 in EPS. Fiscal 2028 EPS estimates average $10.9972, with a high of $13.30. Analyst ratings stand at 8 Strong Buy, 28 Buy, 7 Hold and 1 Sell. Our bull case reaches $325.37.

Cash Burn and Debt Are the Risks Worth Watching
Capital spending of $28.5 billion left free cash flow at -$5.40 billion. Interest expense rose 55% to $1.4 billion. Oracle plans to raise about $40 billion through debt and equity, and software license revenue fell 15%.
After customer prepayments, net cash CapEx came to $18 billion. Management expects each project to turn “something like 100% to post-tax EBITDA” into free cash flow once it starts up. Our bear case of $176.66 still sits above today’s price.
Oracle Trades at a Discount to Microsoft and Amazon
Microsoft (NASDAQ:MSFT) competes for AI workloads through Azure at about 25x forward earnings with 17.7% quarterly revenue growth.
Amazon (NASDAQ:AMZN) runs AWS at about 24x forward earnings with 19.6% revenue growth. Oracle is growing faster than both at a lower multiple. Our target means about 17x earnings, which looks conservative.
| Company | Forward P/E | Quarterly Revenue Growth |
|---|---|---|
| Oracle | 18 | 29.6% |
| Microsoft | 25 | 17.7% |
| Amazon | 24 | 19.6% |
Backlog Tips the Scale Toward Upside
The 24/7 Wall St. price target of $208.21 carries a buy rating at 90% confidence. The deciding factor is the $664 billion backlog at an 18x multiple.
More contracts coming without new Oracle capital, with net CapEx remaining within the $70 billion limit, would support the case. It weakens if data center delays spread beyond New Mexico. At current prices, risk/reward leans toward upside.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $208.21 |
| 2027 | $278.71 |
| 2028 | $337.78 |
| 2029 | $394.14 |
| 2030 | $432.04 |
These projections assume Oracle executes its existing plan. The rate at which RPO converts to revenue could push results far higher or lower than the projections, as could data center funding costs.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.