The SoFi Growth Story Is Getting Harder to Ignore
SoFi just posted record loan originations and raised its full-year guidance, yet the stock sits nearly 40% in the red for the year. Something about that disconnect deserves a closer look.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
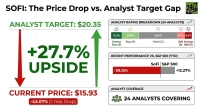
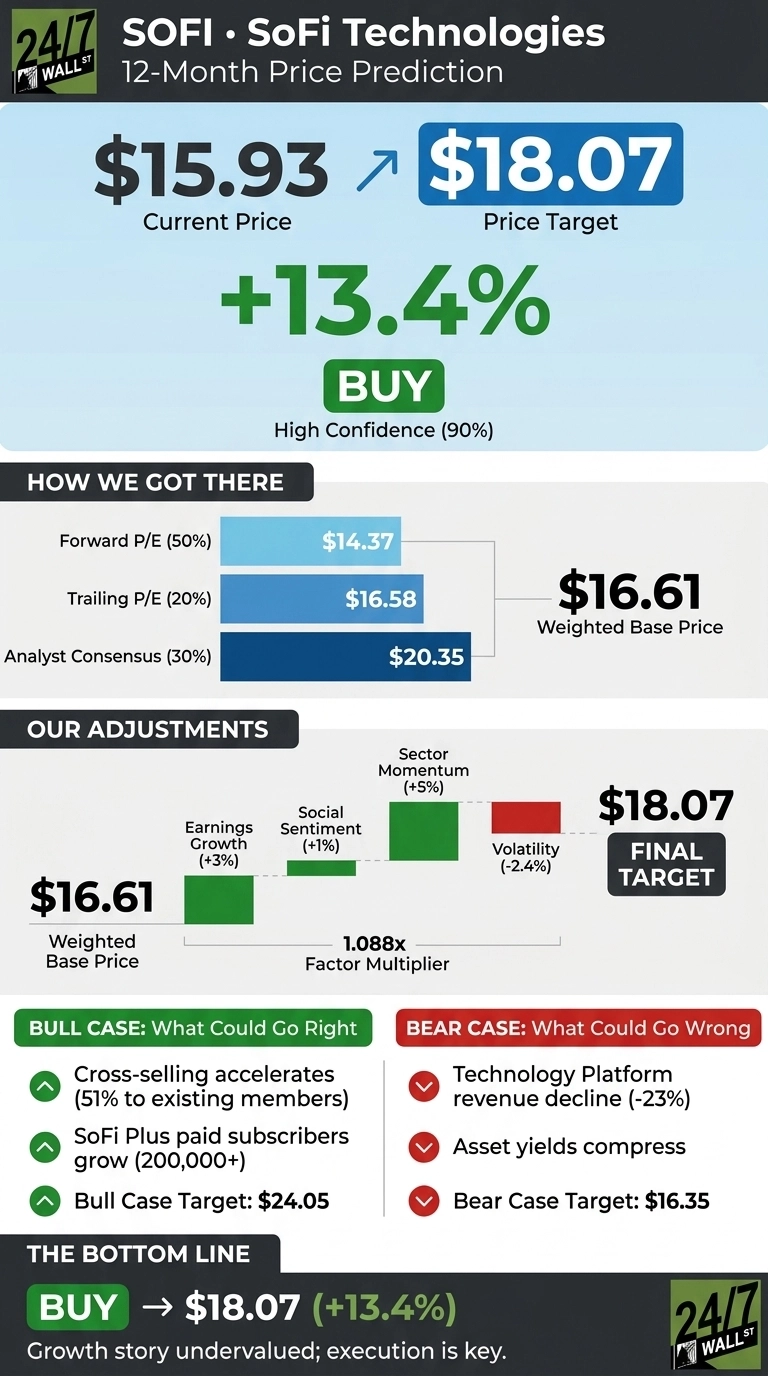
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) keeps reporting records, and the stock keeps falling. Our 24/7 Wall St. price target for SoFi is $18.07 over the next 12 months. That means 13.4% upside from the midday price of $15.93.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $15.93 |
| 24/7 Wall St. Price Target | $18.07 |
| Upside | 13.4% |
| Model Rating | BUY |
| Confidence Level | 90% |
Our model rates SoFi a buy with high confidence. Revenue guidance rose, members grow faster than 30% each year, and credit remains steady, yet the stock has moved the opposite direction. At today’s price, most negative sentiment appears priced in.

Record Growth Meets a 39% Drawdown
Shares fell 6.07% over the past week and 15.45% over the past month. They are down 39.15% year to date. The stock sits 51.3% below its 52-week high of $32.73 and just 7.1% above its low of $14.88.
The business tells a different story. Second-quarter EPS came in at $0.12, beating the $0.1092 estimate. Revenue of $1.22 billion exceeded expectations by 8.24%. Loan originations hit a record $14.8 billion, up 69%, and management raised full-year adjusted net revenue guidance to $4.75 billion to $4.85 billion.

Why Bulls See $24 and Beyond
Cross-selling is the core of the bull case. In the second quarter, 51% of new products went to existing members, up from 35% a year earlier. Selling more to current members brings down the cost of getting each new product.
SoFi Plus passed 200,000 paid subscribers, and CEO Anthony Noto said he would be “disappointed if we are not at 1 million SoFi Plus members generating annual revenue of $120 million a year from now.”
Management’s medium-term target calls for adjusted EPS to grow at a 38% to 42% compound annual rate. Our bull case of $24.05 means 51% upside. The analyst community is more divided: 8 analysts rate the stock a buy or strong buy, while 12 rate it a hold.

Credit and Tech Platform Risks Worth Watching
Technology Platform revenue fell 23% after a large client left. Asset yields slid 32 basis points. Bulls counter that segment revenue rose 13% sequentially, suggesting the client loss is fading. Personal loan charge-offs improved to 2.62% from 2.83%. The bear case of $16.35 sits only slightly above today’s price.
How SoFi Stacks Up Against Affirm and Upstart
Affirm (NASDAQ:AFRM) has a market cap of $20.34 billion, nearly matching SoFi’s $20.57 billion. Affirm trades at a trailing P/E of 11, well below SoFi’s forward multiple of 21. SoFi’s deposit base provides cheaper funding than Affirm’s warehouse and securitization model.
Upstart (NASDAQ:UPST) competes directly in personal loans. Revenue grew 41.75%, but EPS of $0.16 missed the $0.5457 estimate. SoFi has beaten EPS expectations for five straight quarters.
| Company | Market Cap | Latest EPS vs. Estimate |
|---|---|---|
| SoFi | $20.57B | $0.12 vs. $0.1092 |
| Affirm | $20.34B | $0.37 vs. $0.8376 |
| Upstart | $2.23B | $0.16 vs. $0.5457 |
SoFi commands a premium valuation but delivers more consistent earnings than either peer. Against this group, the target appears reasonable.
SoFi Price Prediction 2026-2030
Our $18.07 target carries a buy rating and 90% confidence. Growth looks undervalued at current levels.
I would turn more constructive if cross-selling speeds up and charge-offs stay near current levels, and more conservative if rate hikes squeeze margins or credit losses rise.
Here is where our model projects SoFi could trade, assuming current trends hold.
| Year | Base Case | Bull Case |
|---|---|---|
| 2026 | $16.88 | $18.30 |
| 2027 | $18.86 | $22.96 |
| 2028 | $19.76 | $28.07 |
| 2029 | $20.47 | $31.21 |
| 2030 | $21.46 | $37.77 |
These projections assume SoFi keeps executing on its current strategy. Reaching its return targets could raised results well above these numbers, while a credit downturn could drove them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.