LeBron James Has a Fix for Nike as It Heads Into Its Worst Year Since Jordan Retired
Nike is staring down its worst stock performance in decades while rivals steal its customers and its own earnings hide a financial lifeline most investors missed. LeBron James thinks he knows exactly where the brand went wrong.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

LeBron James still moves money for whoever he plays for. After he joined the Philadelphia 76ers, the team’s ticket sales on StubHub (NYSE:STUB | STUB Price Prediction) jumped 585%, and the Sixers drew 38% of all NBA ticket search traffic. Nike (NYSE:NKE) has paid him since 2003, and it heads into tonight’s earnings report in much worse shape.
Nike traded at $35.09 late Thursday. That leaves the stock down 43.46% year to date and 48.01% over the past 12 months. CNBC reported that Nike is on track for its worst year since 1993, the year Michael Jordan first retired.

LeBron’s Fix Goes Straight to What Nike Lost
At the CNBC Sport x Boardroom Game Plan Summit on July 16, Boardroom’s Rich Kleiman asked James how Nike could recover:
“You’ve got to get back into the roots. You’ve got to get back to being out in the inner city, having runners. When I was coming up, you had people who were literally out in the communities talking to these younger generations, asking them what they like, what they don’t like.”
He ended with a warning:
“It was such a cool factor. So we can’t lose our cool.”
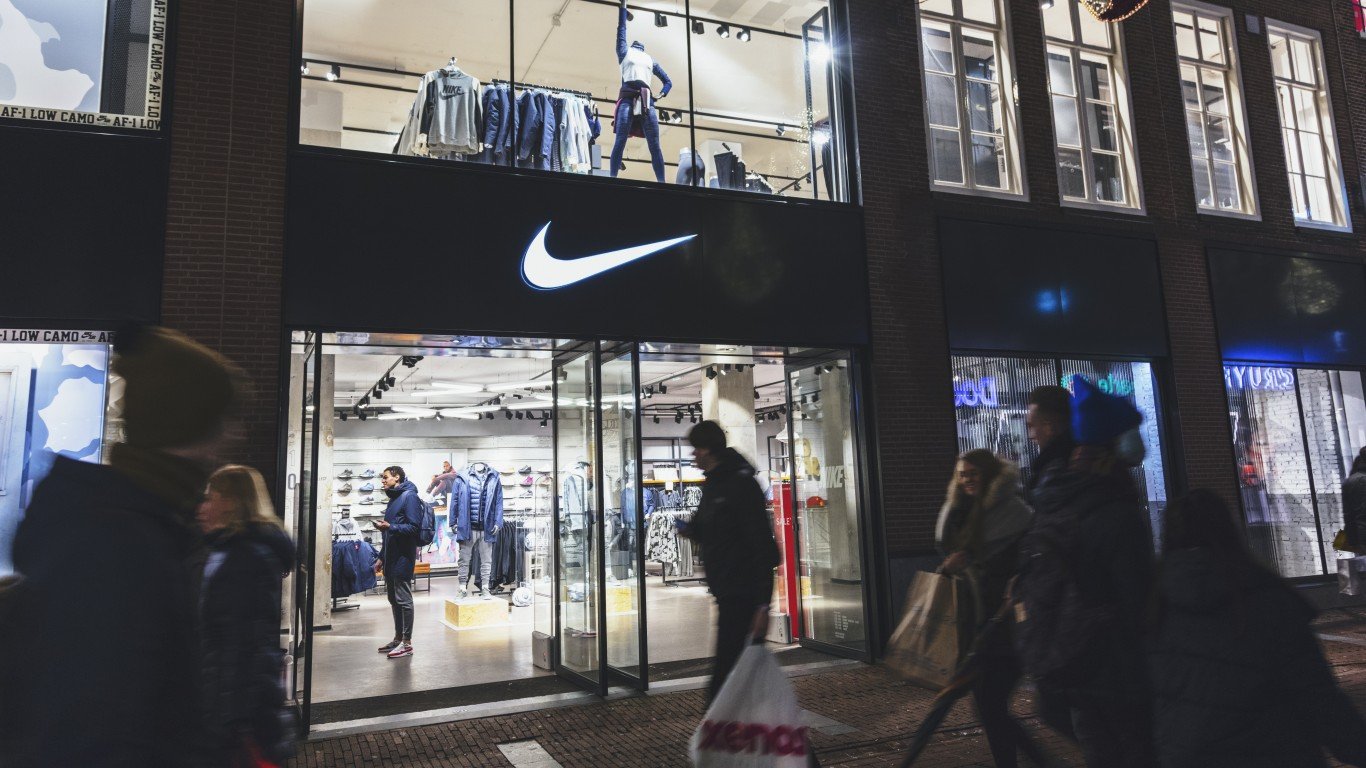
On Thursday, CNBC paired the clip with Wharton marketing professor Americus Reed, who argued that Nike leaned too hard on direct-to-consumer channels and celebrity deals while letting community relationships slip. A sellout shoe is a transaction; loyalty is separate. Pulling back from retail stores removed the emotion and storytelling that build deeper bonds with shoppers. Reed’s point: a brand “has to live and breathe within the community.”
Nike’s Recent Profits Lean on a Tariff Refund
In its June 30 report, Nike posted revenue of $10.97 billion, down 1.1% from a year earlier. Diluted EPS came in at $0.72, but $0.52 of that came from a $986 million tariff-recovery benefit. Without the refund, full-year EPS would have been $1.58. Digital sales fell 12%, Greater China dropped 17% on a currency-neutral basis, and Converse sank 32%.

CEO Elliott Hill named the weakest spots:
“We know we’re not living up to our full potential, particularly in Nike Sportswear and Jordan Streetwear, where sell-through remains challenged.”
Sportswear and Jordan Streetwear make up about half of Nike’s revenue. Running is strongest, with five consecutive quarters of double-digit growth. Hill: “When we lead with sport, we win.”
Rivals Reed Named Are Taking Share
Reed singled out Hoka and On Holding (NYSE:ONON) as the brands winning shoppers’ attention. On Holding grew Q2 2026 revenue 13.49%, or 21.6% in constant currency. Its gross margin reached 65.4%, and direct sales rose 26.0%. On Holding also signed Kylian Mbappé away from Nike as it moves into soccer. Co-CEO David Allemann described the strategy:
“We are proving that a brand can achieve global scale without compromising its premium brand positioning.”
At Deckers Outdoor (NYSE:DECK), Hoka’s net sales rose 7.7% to $703.50 million, and gross margin came in at 56.4%. Nike’s full-year gross margin, excluding the tariff benefit, was 40.8%.
What to Watch After the Bell
Management guided for revenue to fall by a low to mid-single digits percentage. CFO Matt Friend said “profitability will bottom before sales” in China. Analysts are conservative: 25 rate the stock a hold, with a $45.63 price target. Watch whether sell-through improves in Sportswear and Jordan, and whether running’s momentum spreads to basketball. Hill warned that “progress will continue to be uneven.”

Data Sources
- CNBC: Wharton’s Americus Reed on Nike: Reed’s view on transactions versus loyalty, the effect of direct-to-consumer, and the worst-year-since-1993 comparison.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)