My Nvidia Price Target Looks Beyond the Next Few Quarters
NVIDIA just posted quarterly revenue that would have counted as a strong full year not long ago, yet the stock still trades at a fraction of what its earnings growth suggests it deserves. Something has to give, and the path…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The quarter NVIDIA (NASDAQ:NVDA | NVDA Price Prediction | NVDA Price Prediction) just reported would have counted as a strong full year not long ago. Revenue reached $96.22B in Q2 fiscal 2027, up 105.8% year over year. Data Center generated $89.02B, and Networking alone contributed $40.31B.
As Jensen Huang summed it up: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.” The stock is up 23.71% year to date, far behind that pace. So can NVIDIA hit $350 in 2027?

Why NVIDIA Shares Lag Its Own Earnings Growth
Over the past year, shares gained 29.49% while quarterly net income rose 125.9%. The worries behind that gap are real. Management noted “extreme pricing conditions in memory” and expects gross margin to bottom at 71% to 72% in Q4. Supply commitments jumped to $279B.
Guidance includes no China data center compute revenue, and days sales outstanding stretched to 60 days from 45. Management even admitted that “some will call this circular financing.”
Recent gains are modest: 1.23% in a week and 5.93% in a month. With a beta of 2.217, any doubt about AI spending hits these shares harder than it hits the broader market.
Wall Street Sees 42.4% Upside. Our Model Says 17.7%
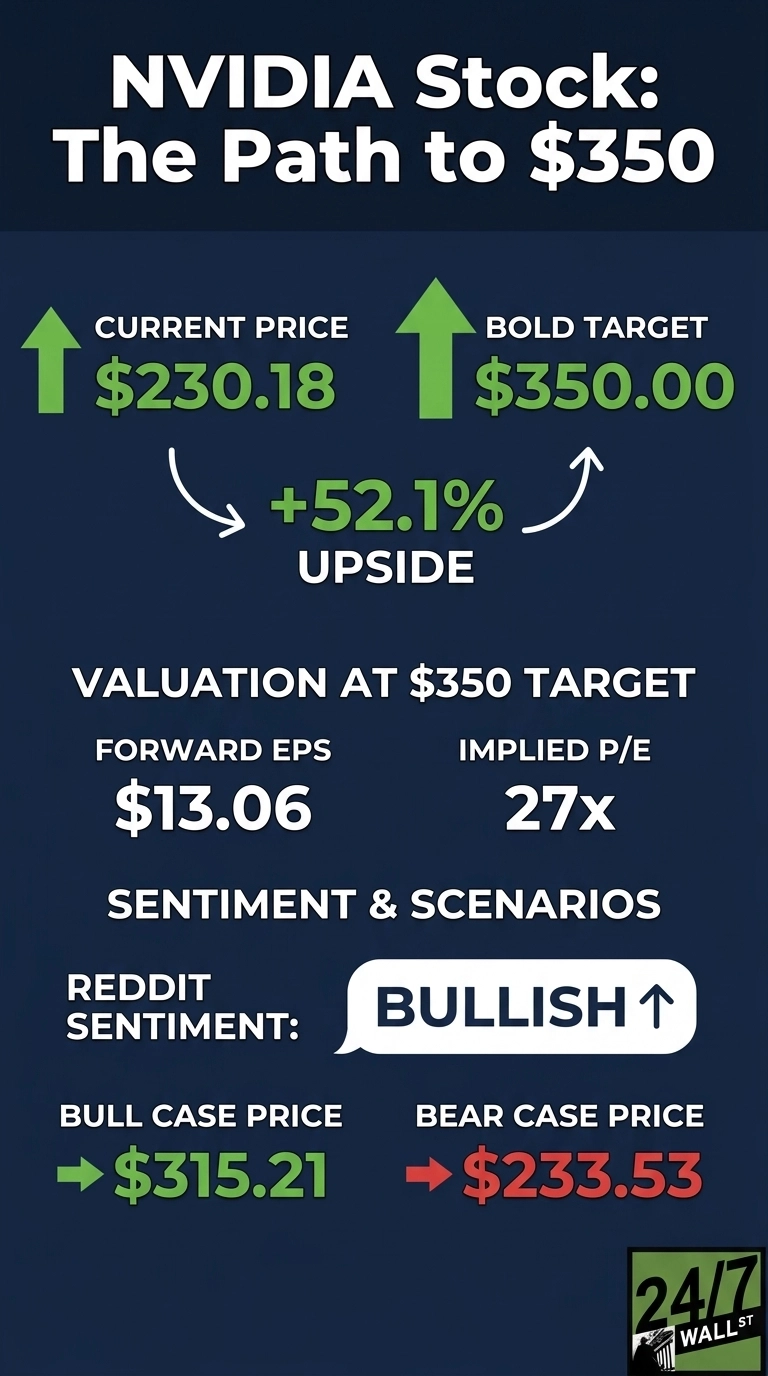
The consensus target is $327.70, which implies 42.4% upside. Ratings stand at 9 Strong Buys, 48 Buys, 2 Holds and 1 Sell. The base case is $270.40 (17.68% upside), inside a range that runs from $233.53 to $315.21, with high confidence of 0.9.

Mega-cap muting holds the earnings growth contribution to just 0.03. The analysts, who are 95% bullish, still lag on the longer horizon in my view. The fiscal 2028 EPS estimate climbed from $13.1277 to $15.6826 in 30 days, with 42 upward revisions and zero cuts.
What It Takes for NVIDIA to Reach $350
To get to $350 from today’s price of $230.18 would require a gain of 52.1%.
With forward EPS of $13.0579, a price of $350 implies a forward P/E of 27x. That sits below the 33x implied multiple in our valuation model. Measured against today’s 18x, the rerating needed is 9.2 turns.
I think that rerating is possible. Earnings growth also works in the stock’s favor. Management expects revenue to grow approximately 70% in fiscal 2028, even with supply constraints. At $350, the stock trades at just 22x fiscal 2028 consensus EPS.
Vera Rubin began production shipments in August, and AWS is deploying an additional 2 million GPUs. The board just expanded the buyback into the largest in history, and CNBC reads that as a sign the stock is too cheap for Huang to resist (CNBC; The New York Times). Huang says “demand is accelerating.”
If AI capital spending slows down, the $279B in supply commitments could become a burden.
Where NVIDIA Trades Today Versus Its Earnings Power
At 18x forward earnings, NVIDIA trades at a modest multiple for a company growing revenue at triple digits. Shares sit near the top of their 52-week range of $163.90 to $236.
Over 10 years, the stock has returned 13,592.4%. The current multiple prices in doubt that the earnings trend keeps contradicting.

Is $350 Realistic? My Verdict
Hitting $350 requires a 52.1% gain. I call it a stretch that can be reached.
Three things need to go right: Vera Rubin launches on schedule, gross margins recover after the Q4 low, and fiscal 2028 estimates keep rising. A sharp decline in hyperscaler spending would ruin the thesis.
All of that capex has to be powered, cooled, and networked by somebody, and we covered seven of those suppliers in a free AI infrastructure report. Returns at this level shouldn’t be expected every year, but we’ve outlined the blueprint for how NVIDIA could reach $350 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.