The Adobe Stock Debate Is About to Get Interesting
Adobe beat earnings for the fifth straight quarter, yet the stock sits 31% in the hole for the year while a generative AI rival just torched its retail sentiment. Something has to give, and the answer depends on a bet…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Adobe (NASDAQ:ADBE | ADBE Price Prediction) trades at $239.94. Our 24/7 Wall St. price target is $286.62 over the next 12 months, which means 19.45% upside. Our model rates the stock a buy, and its confidence level is high.
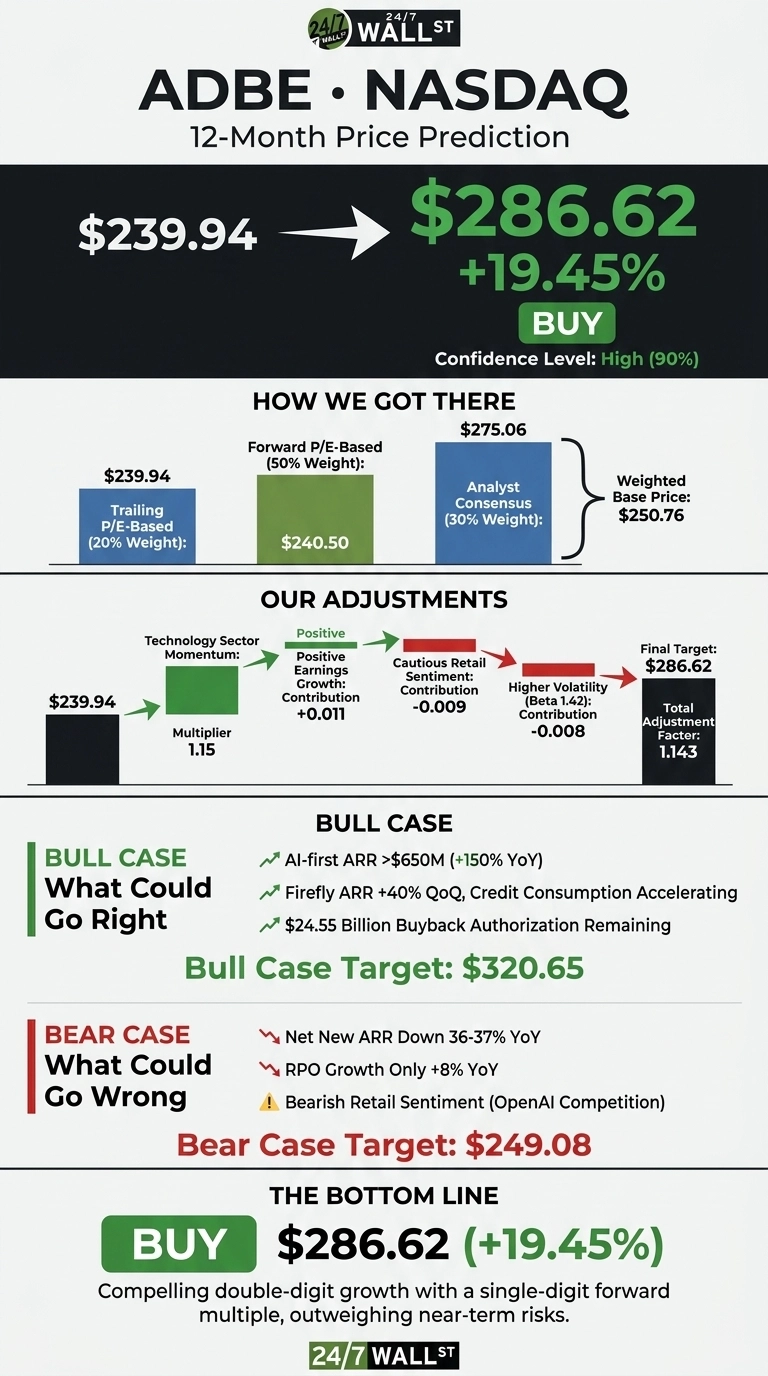
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $239.94 |
| Price Target from 24/7 Wall St. | $286.62 |
| Upside/Downside | 19.45% |
| Recommendation | BUY |
| Confidence Level | 90% |
The debate: can Adobe convert surging AI engagement into durable revenue faster than generative AI rivals erode its creative moat? At 9x forward earnings, the market is pricing in a decline the financials have yet to show.

Adobe Slid 31% in 2026 Despite a Q3 Beat
The stock is down 31.31% year to date and 17.89% over the past month, and it was flat over the past week. That leaves it about 34% below its 52-week high of $363.70 and 26% off its $190.12 low.
Fiscal Q3 revenue of $6.76B beat the $6.70B consensus, and non-GAAP EPS of $6.13 topped expectations for a 5th consecutive quarter. Management raised full-year non-GAAP EPS guidance to $24.45 to $24.50.
Retail sentiment turned bearish after OpenAI released ChatGPT Images 2.5. Investors also face a leadership change: Anil Chakravarthy takes over as CEO on December 1st.

Why Bulls See a Path to $320
AI-first ARR topped $650 million, up more than 150% year over year. Monthly active users passed 1 billion, and Firefly ARR grew 40% quarter over quarter. Adobe also has $24.55 billion left on its buyback authorization.
Analysts expect fiscal 2027 EPS of $27.6733, and their consensus target is $275.06. In our bull scenario, the stock reaches $320.65.

What Could Push Adobe Toward $249
Wall Street remains cautious, with 23 Hold ratings against 5 Sell or Strong Sell ratings. One analyst noted net new ARR fell “36, 37%” year over year, while remaining performance obligations grew only 8%.
Management prioritizes freemium user acquisition and delays pricing actions, which bulls see as investment in future conversion. Our bear case is at $249.08.

Adobe Trades at a Steep Discount to Salesforce and Autodesk
Salesforce (NYSE:CRM) competes directly with Adobe Experience Cloud for enterprise customer-experience budgets. The stock changes hands at 14x forward earnings, with quarterly revenue growth of 10.8%. Adobe is growing faster at a lower multiple.
Autodesk (NASDAQ:ADSK) is the closest subscription design-software peer. It commands 18x forward earnings, with revenue growth of 16.1%.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Adobe | 9x | 12.9% |
| Salesforce | 14x | 10.8% |
| Autodesk | 18x | 16.1% |
Our target means a forward multiple still below both peers. Against this group, the 24/7 Wall St. price target looks conservative.
Adobe Price Prediction 2026-2030
The 24/7 Wall St. price target of $286.62 comes with a buy rating and 90% confidence. What tips the scale for me is Adobe’s single-digit forward multiple sitting alongside double-digit growth.
The setup looks compelling if freemium users start converting into ARR during the seasonally strong fourth quarter. Caution makes sense if net new ARR keeps shrinking under the new CEO. I think the market is too pessimistic here.
Looking further ahead, here is where our model projects Adobe could trade by the end of each year, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $250.23 |
| 2027 | $294.47 |
| 2028 | $325.33 |
| 2029 | $371.47 |
| 2030 | $404.07 |
Adobe would need to keep executing on its agentic AI strategy for these projections to hold. Faster Firefly monetization could add significant upside, while losing creative share to generative AI rivals is the biggest downside risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.