ExxonMobil’s Dividend Story Is Only Part of the Bull Case
ExxonMobil has surged more than 38% this year on record Permian output, a 43-year dividend growth streak, and free cash flow that rivals any major oil company on earth, yet one valuation signal suggests the best of the rally may…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our 24/7 Wall St. price target for ExxonMobil (NYSE:XOM | XOM Price Prediction) is $132.90 over the next 12 months. That compares with a current price of $164.01.
| Metric | Value |
|---|---|
| Current Price | $164.01 |
| Price Target from 24/7 Wall St. | $132.90 |
| Upside/Downside | -18.97% |
| Model Rating | SELL |
| Confidence Level | 90% |

ExxonMobil gets a sell rating with high confidence from the model. The main reason is valuation: after a big run, the shares price in more earnings than consensus forecasts support. The rating reflects price only. The business itself keeps getting stronger.
Why We Could Be Wrong About ExxonMobil
The bull case rests on Guyana, where Exxon has already recovered its $55 billion investment, so more of that output now becomes into free cash flow. Treat our target as one data point among many.
A 38% Rally Built on Disruption and Execution
The stock is up 38.52% year to date and 51.08% over the past year. Shares trade near the top of a 52-week range of $107.28 to $174.09.
In the second quarter, Exxon gets $14.5 billion, generated more than $17 billion of free cash flow and cut net debt by more than $7 billion. First-quarter adjusted EPS of $1.16 beat the $1.01 estimate.
Why Bulls See $170 and Beyond
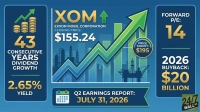
The $1.03 quarterly dividend continues a 43-year growth run. Guyana produced about 900,000 barrels per day gross, and a fifth FPSO (floating production vessel) is due to start up by year-end. Permian output hit a record of more than 1.8 million barrels of oil equivalent per day.
Structural cost savings reached $16.3 billion against a $20 billion goal for 2030, and a $20 billion buyback plan is in place for 2026. Management expects “two times the level of free cash flow in 2030 than we saw in 2025.”
The consensus analyst target is $173.41, with 10 of analysts rating the stock a buy or better. Our own bull scenario reaches $171.79 over five years.

Oil Price Normalization Could Undo the Premium
The stock trades at a trailing P/E of 23, while the price-to-free-cash-flow ratio is at 28.58. The effective tax rate rose to 40% in the first quarter.
Our bear case points to $122. First-quarter GAAP profit was weighed down by a $3.88 billion derivative timing charge, but underlying earnings rose to $8.77 billion.

How ExxonMobil Compares to Chevron and Shell
Chevron (NYSE:CVX) is the closest U.S. integrated peer with Guyana exposure through Hess. The stock’s trailing P/E is 33 and the yield is 3.14%. By that measure, Exxon’s multiple looks moderate.
Shell (NYSE:SHEL) offers a contrast in LNG and integrated operations. Its second-quarter EPS of $1.92 missed the $3.18 estimate, though free cash flow reached $17.5 billion.
| Company | Market Cap | Q2 2026 Free Cash Flow |
|---|---|---|
| ExxonMobil | $672.05B | >$17B |
| Chevron | $400.2B | $18.1B |
| Shell | $272.4B | $17.5B |
Exxon generates free cash flow similar to its peers while carrying the largest market value of the group. Against these peers, our target looks somewhat conservative.
ExxonMobil Price Prediction 2026-2030
The 24/7 Wall St. price target of $132.90 carries a sell model rating at 90% confidence. What tips the scale is the forward earnings outlook as oil prices return to normal.
I would become more constructive if Guyana’s free cash flow inflection shows up in earnings forecasts. Until then, the price already reflects much of the good news.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $132.90 |
| 2027 | $132.58 |
| 2028 | $120.04 |
| 2029 | $116.43 |
| 2030 | $115.91 |
ExxonMobil needs to keep executing its current strategy for these projections to hold. A longer disruption in the Strait of Hormuz, or new finds in Guyana, could move results significantly higher.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.