Prediction: LLY Has Another Massive Growth Opportunity Beyond Weight Loss
Eli Lilly built its reputation on weight loss drugs, but a fast-growing portfolio in oncology, immunology, and neuroscience just posted triple-digit gains, and Wall Street is only beginning to price in what comes next.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

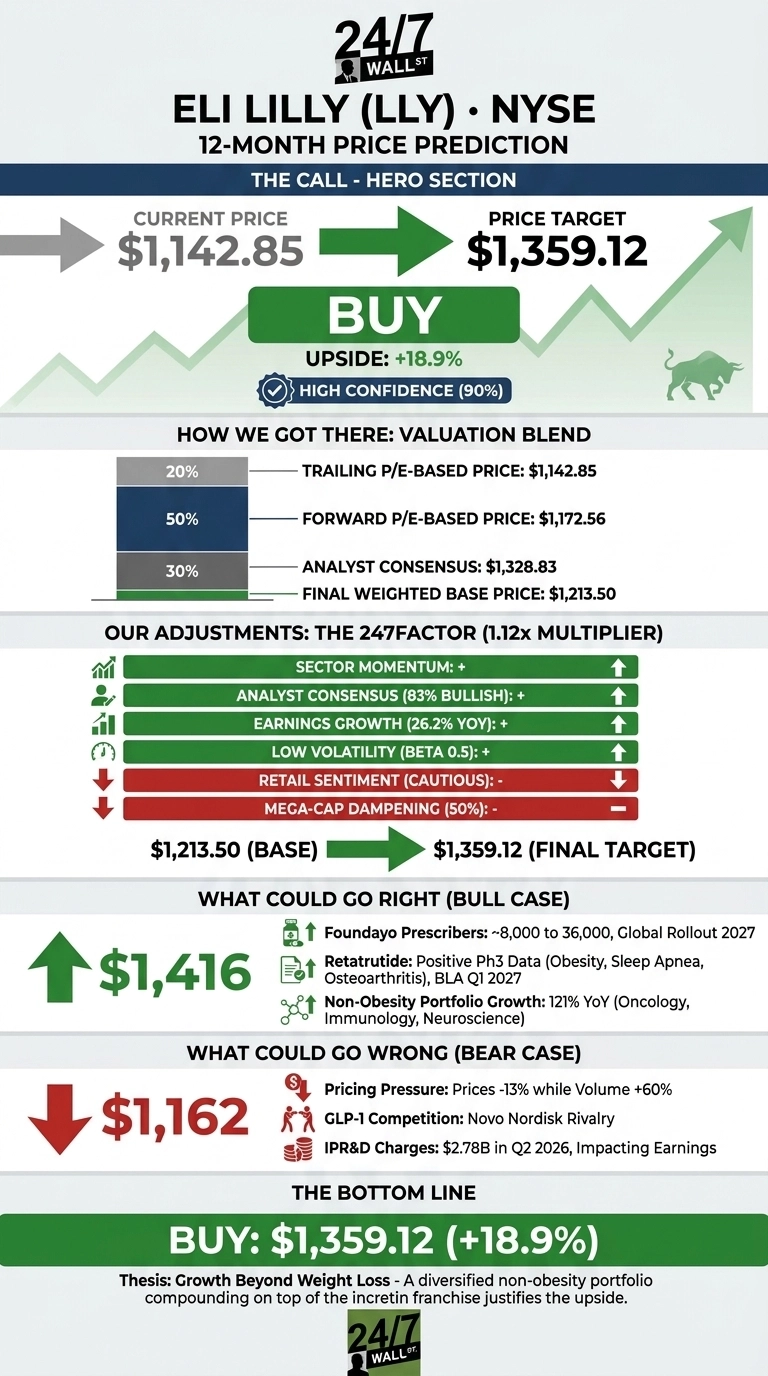
The 24/7 Wall St. price target for Eli Lilly (NYSE:LLY | LLY Price Prediction) is $1,359.12 over the next 12 months. With the stock at $1,142.85, that implies 18.92% upside. Lilly wins a buy rating from the model, with high confidence.
| Metric | Value |
|---|---|
| Current Price | $1,142.85 |
| Price Target from 24/7 Wall St. | $1,359.12 |
| Upside/Downside | 18.92% |
| Model Rating | BUY |
| Confidence Level | 90% |
Mounjaro and Zepbound built the story. The next leg comes from an oral GLP-1, a next-generation incretin, and a non-obesity portfolio that is growing quickly. Lilly’s oncology, immunology, and neuroscience medicines grew 121% year over year last quarter.

Record Growth Meets a Pullback From the Highs
Shares sit 11.6% below the 52-week high of $1,292.65 and 46.7% above the low of $778.94. LLY is down 2.3% since mid-July, up 10.1% since mid-January, and up 39.5% from mid-October 2025.
Q2 revenue reached $22.97B, up 47.67% and ahead of the $20.69B estimate. EPS of $8.38 beat the $6.58 consensus even after taking on $3.03 of acquired IPR&D charges. Management raised full-year revenue guidance to $85B-$87B and set non-GAAP EPS guidance at $35.50-$36.50.
Why Bulls See $1,416 as Lilly Moves Beyond Obesity
Foundayo, the oral GLP-1, brought in $98M last quarter. Prescribers rose from about 8,000 to 36,000, and the pill is under review in over 40 additional countries.
A U.S. type 2 diabetes decision is expected later this year. Retatrutide has Phase 3 data in obesity, sleep apnea, and knee osteoarthritis, where pain fell by 75%, and a U.S. filing is planned for Q1 2027.
Outside cardiometabolic drugs, Ebglyss grew 131%, Jaypirca rose 56%, and Inluriyo holds more than 50% of new U.S. oral SERD prescriptions.
In early testing, Verve’s VERVE-102 gene editor cut LDL cholesterol by up to 62% with one dose. Analyst ratings stand at 6 Strong Buy and 19 Buy, with a consensus target of $1,328.83. The bull case reaches $1,416.26.

Pricing Pressure Is the Risk to Watch
Volume rose 60% last quarter while prices fell 13%. Mounjaro and Zepbound still make up most of revenue, and tariffs and competition from Novo Nordisk (NYSE:NVO) remain live risks.
Q2 also carried $2.78B in IPR&D charges. Those were one-time costs of buying pipeline assets, though, and point to future growth. The bear case of $1,161.70 still sits above today’s price.
Lilly’s Premium Over Novo Nordisk and AbbVie Is Earned
Novo Nordisk is Lilly’s direct GLP-1 rival. The stock changes hands at about 12x forward earnings, but quarterly revenue grew just 2.1% and earnings fell 20.6%. The discount shows lost share.
AbbVie (NYSE:ABBV) is the benchmark for a diversified immunology franchise, trading at 16x forward earnings on 10.2% revenue growth.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Eli Lilly | 26x | 47.67% |
| Novo Nordisk | 12x | 2.1% |
| AbbVie | 16x | 10.2% |
Lilly is growing several times faster than either peer, so I think a 26x multiple supports the 24/7 Wall St. price target as reasonable.

Growth Beyond Weight Loss Justifies the Upside
The 24/7 Wall St. price target is $1,359.12, the model rates LLY a buy, and confidence is 90%. The deciding factor is a non-obesity portfolio compounding on top of the incretin franchise.
A Foundayo diabetes approval and on-schedule retatrutide filing would strengthen the case. It gets weaker if price cuts start to exceed volume growth. Right now, volume growth is exceeding price declines.
Eli Lilly Price Prediction 2026-2030
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,190.88 |
| 2027 | $1,410.20 |
| 2028 | $1,590.91 |
| 2029 | $1,714.65 |
| 2030 | $1,879.00 |
Lilly needs to keep executing on its current strategy for these projections to hold. Retatrutide’s regulatory path and U.S. drug pricing policy could move them sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.