Analysts Just Upgraded Marvell. Here’s What They See Coming Next
Wall Street just flooded Marvell with price target hikes after a single Investor Day presentation, and the earnings framework at the center of the bullish case is raising eyebrows even among analysts who support the stock.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
TD Cowen analyst Sean O’Loughlin upgraded Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) to Buy from Hold and raised his price target to $350 from $245. The upgrade led a wave of price target increases after the chipmaker’s October 6, 2026 Investor Day, and Piper Sandler, Needham and BofA each went to $400.
The upgrade signals growing Wall Street confidence that Marvell’s AI connectivity franchise can lift earnings sharply by the end of the decade.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| MRVL | Marvell | TD Cowen | Upgrade | Hold | Buy | $245 | $350 |
| MRVL | Marvell | Piper Sandler | Target Raise | Overweight | Overweight | $270 | $400 |
| MRVL | Marvell | Needham | Target Raise | Buy | Buy | $300 | $400 |
| MRVL | Marvell | BofA | Target Raise | Buy | Buy | $365 | $400 |
| MRVL | Marvell | Stifel | Target Raise | Buy | Buy | $350 | $370 |
| MRVL | Marvell | JPMorgan | Target Raise | Overweight | Overweight | $305 | $360 |
| MRVL | Marvell | UBS | Target Raise | Buy | Buy | $335 | $350 |
| MRVL | Marvell | Cantor Fitzgerald | Target Raise | Neutral | Neutral | $330 | $350 |
| MRVL | Marvell | Morgan Stanley | Target Raise | Equal Weight | Equal Weight | $268 | $300 |
| MRVL | Marvell | Goldman Sachs | Target Raise | Neutral | Neutral | $220 | $270 |
Analyst’s Case: A $30 EPS Framework Resets Expectations
TD Cowen says Marvell’s growth drivers have “fully shifted” to its “strong” connectivity franchise, and it now views the concentration risk linked to custom XPU programs as largely de-risked.
The firm calls the forward outlook “aggressive but reasonable” and sees it generating over $30 in EPS within three years.
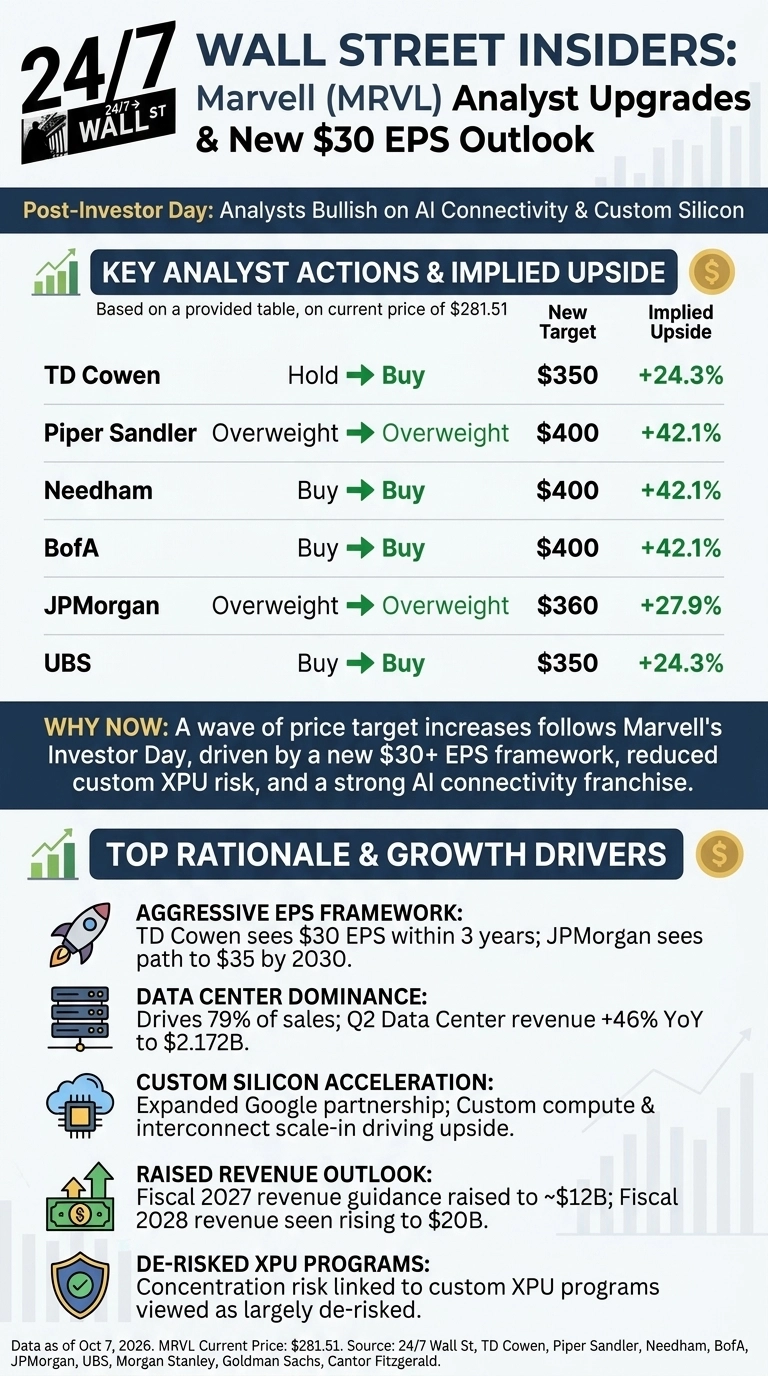
That figure anchors analyst notes. Marvell’s fiscal 2031 model targets $70B to $90B in revenue and more than $30 of non-GAAP EPS.
Piper Sandler said this was well above consensus estimates. UBS cited upside from custom compute, interconnect scale-in, and operating leverage.
JPMorgan sees a “credible path” to $35 of EPS by 2030. Needham pointed to fiscal 2028 revenue rising to $20B from $18B, driven by optics and switching.
Three firms stayed cautious. Morgan Stanley’s Joseph Moore said the targets run at least 20% above his forecasts but added he doesn’t “know that they needed to raise the bar this high.” Goldman Sachs and Cantor Fitzgerald held Neutral ratings.

Company Snapshot: Data Center Now Drives 79% of Sales
Second-quarter fiscal 2027 revenue reached $2.739B, up 36.5% YoY, beating the $2.707B consensus. Non-GAAP EPS was $0.94. Data Center revenue rose 46% to $2.172B, or 79% of the total. Management now expects fiscal 2027 revenue of roughly $12 billion.
Marvell also expanded its custom silicon partnership with Alphabet (NASDAQ:GOOGL) unit Google, including a warrant for up to 7% of Marvell shares linked to revenue milestones.

Why the Move Matters Now
Marvell stock traded at $281.51 premarket, up 231.74% year to date but below its $329.80 52-week high. It trades at 62x forward earnings.
The fiscal 2028 consensus EPS estimate rose to $6.7609 from $6.1726 90 days ago, with 33 upward revisions against 1 cut over 30 days.

What It Means for Your Portfolio
A beta of 2.26 means sharp moves was with the territory. Marvell reveals risks from customer concentration, hyperscalers building their own chips, China trade restrictions, wafer supply limits and $4.963B of long-term debt.
The key question is whether third-quarter results meet the $3.150B revenue guidance. The higher outlook merits a closer look (we considered what the early signs of the biggest AI chip winners looked like and put the pattern in a free playbook here), but near-term volatility remains a real risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.